
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
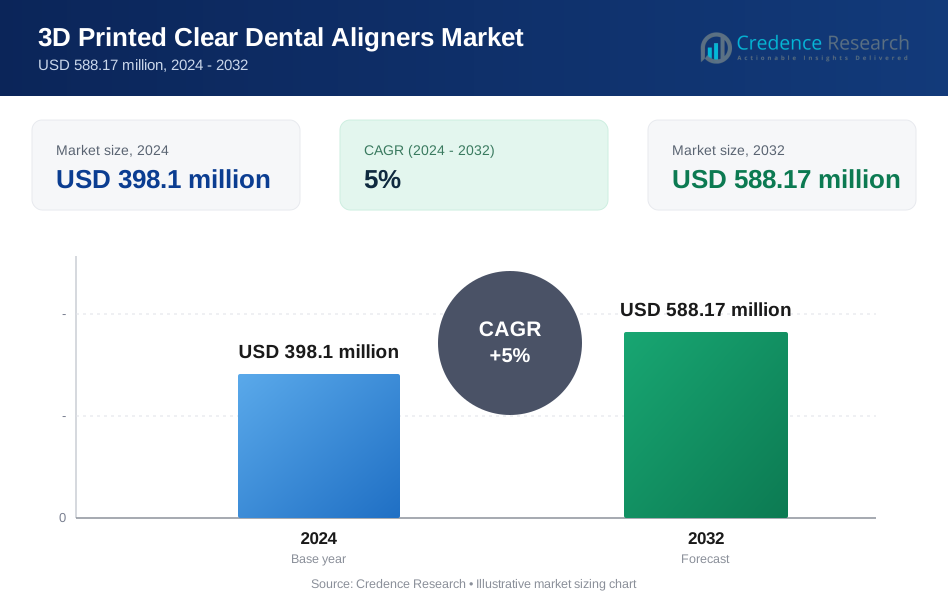
| 3D Printed Clear Dental Aligners Market Size 2024 | USD 398.1 million |
| 3D Printed Clear Dental Aligners Market, CAGR | 5% |
| 3D Printed Clear Dental Aligners Market Size 2032 | USD 588.17 million |
Market Overview
The 3D Printed Clear Dental Aligners Market is projected to grow from USD 398.1 million in 2024 to USD 588.17 million by 2032, at a compound annual growth rate (CAGR) of 5%.
The 3D Printed Clear Dental Aligners market is experiencing significant growth, driven by advancements in 3D printing technology, increasing demand for personalized orthodontic solutions, and a growing preference for aesthetically pleasing dental treatments. The ability of 3D printing to produce highly accurate, custom-fit aligners at reduced production times and costs has revolutionized the orthodontics industry. Rising awareness about dental health, coupled with the increasing adoption of minimally invasive procedures, is further fueling market demand. Trends such as the integration of AI-driven design and predictive analytics in aligner production are enhancing efficiency and patient outcomes. The surge in e-commerce platforms offering direct-to-consumer aligners and the growing acceptance of tele-orthodontics are also reshaping market dynamics. Additionally, the expanding base of tech-savvy consumers and the global rise in disposable income contribute to the sustained growth of this market. As innovation accelerates, the 3D Printed Clear Dental Aligners market is set to witness robust expansion in the coming years.
Geographically, North America dominates the 3D Printed Clear Dental Aligners market, accounting for around 40% of the global share, driven by advanced healthcare infrastructure and high demand for aesthetic dental solutions. The United States leads with a strong presence of key players such as Align Technology, Inc., SmileDirectClub, and Dentsply Sirona. In contrast, the Asia-Pacific region is the fastest-growing, expected to capture 25% of the market by 2032, spurred by economic growth and increasing demand for dental aesthetics in countries like China and India. Leading players like 3D System Inc., ClearCorrect LLC (Straumann Group), and Formlabs are expanding their reach in the region. Europe also plays a crucial role, with companies like FORESTADENT and Graphy Inc. contributing to market expansion, particularly in high-income countries.
Market Drivers:
Technological Advancements in 3D Printing:
The rapid evolution of 3D printing technology is a primary driver of the 3D Printed Clear Dental Aligners market. Innovations in materials, printing speed, and precision have enabled manufacturers to produce highly customized, accurate, and durable aligners. For instance, advancements in multi-material and multi-color printing have significantly enhanced the capabilities of 3D printers. The adoption of advanced 3D printers in dental laboratories has significantly reduced production times and costs, making aligners more accessible to both providers and patients. These advancements are also paving the way for improved scalability, allowing manufacturers to meet increasing global demand efficiently.
Rising Demand for Aesthetic and Personalized Orthodontics:
The growing preference for minimally invasive and aesthetically pleasing dental solutions is driving the adoption of clear dental aligners. Patients increasingly seek orthodontic treatments that offer comfort, convenience, and discretion, fueling demand for customized aligners. For instance, the increasing focus on aesthetics is enabling the market to grow globally. 3D printing technology meets this demand by enabling the creation of aligners tailored to individual dental structures. The ability to produce precise and personalized solutions not only enhances patient satisfaction but also strengthens the market’s growth trajectory.
Increasing Awareness of Dental Health:
A heightened awareness of dental health and its connection to overall well-being is encouraging more individuals to pursue orthodontic treatments. Campaigns promoting oral hygiene, combined with a rising prevalence of malocclusions, have boosted the adoption of dental aligners. For instance, the World Health Organization (WHO) reports that oral diseases affect nearly 3.5 billion people globally. Additionally, the integration of 3D printing in aligner production addresses the growing need for efficient and cost-effective treatments, further driving market expansion.
Expanding Digital and Direct-to-Consumer Models:
The emergence of digital orthodontics and direct-to-consumer business models has transformed the 3D Printed Clear Dental Aligners market. Tele-orthodontics platforms and e-commerce channels provide patients with affordable and convenient access to aligners, bypassing traditional clinical settings. For instance, the adoption of digital technologies in dental practices has significantly enhanced treatment accuracy and patient satisfaction. This shift has broadened the consumer base while reducing barriers to adoption. The convenience of remote consultations, coupled with the efficiency of 3D printing, ensures continued market growth.
Market Trends:
Integration of Artificial Intelligence and Predictive Analytics:
The 3D Printed Clear Dental Aligners market is witnessing a surge in the adoption of artificial intelligence (AI) and predictive analytics in treatment planning and aligner design. AI-powered tools enable orthodontists to simulate treatment outcomes with high accuracy, enhancing the precision of aligners. For instance, AI-driven software can create precise treatment simulations for clear aligners, predicting tooth movement and treatment outcomes. Predictive analytics helps in forecasting patient progress, allowing for timely adjustments and improved treatment efficacy. These technologies streamline workflows, reduce production errors, and enhance patient satisfaction, establishing a competitive edge for providers.
Growth of Direct-to-Consumer Models:
Direct-to-consumer (DTC) models have revolutionized the way clear aligners are marketed and delivered. E-commerce platforms and tele-orthodontics allow patients to access affordable and personalized aligners without visiting traditional clinics. For instance, the cash-pay direct dental care model emphasizes transparency, affordability, and streamlined access to dental services. These platforms leverage 3D printing to produce high-quality aligners efficiently, meeting the growing demand for convenience and cost-effectiveness. The DTC approach also fosters market penetration in regions where traditional orthodontic services are less accessible, broadening the customer base.
Advancements in Biocompatible Materials:
The development of innovative, biocompatible materials for 3D printing has enhanced the performance and comfort of clear dental aligners. These materials offer improved flexibility, durability, and transparency, ensuring aligners are both effective and aesthetically pleasing. For instance, advancements in nano and biomaterials have significantly improved the efficacy of dental implants. Advances in material science also support longer wear times and reduced patient discomfort, aligning with the growing demand for superior-quality orthodontic products.
Increasing Adoption of Digital Workflows:
The digital transformation of orthodontics is a significant trend shaping the 3D Printed Clear Dental Aligners market. End-to-end digital workflows, encompassing intraoral scanning, CAD/CAM software, and 3D printing, are replacing traditional processes. For instance, digital workflows allow for more accurate treatment planning and improved patient outcomes. This shift reduces production time, enhances accuracy, and minimizes waste, making aligner manufacturing more sustainable. The integration of digital workflows also supports better collaboration between dental professionals and technicians, ensuring optimal treatment outcomes.
Market Challenges Analysis:
High Initial Costs and Limited Accessibility:
One of the significant challenges in the 3D Printed Clear Dental Aligners market is the high initial cost associated with adopting advanced 3D printing technology. Dental practices and laboratories often require substantial investments in equipment, software, and skilled personnel to integrate 3D printing into their workflows. These costs can be a barrier, particularly for small and mid-sized clinics, limiting the widespread adoption of this technology. Additionally, the affordability of aligners for end-users remains a concern in price-sensitive markets, where traditional orthodontic treatments may still dominate due to lower upfront costs. Limited accessibility to high-quality 3D printing materials and infrastructure in developing regions further hampers market penetration.
Regulatory Compliance and Material Limitations:
The stringent regulatory landscape governing medical devices poses another challenge for the 3D Printed Clear Dental Aligners market. Manufacturers must adhere to rigorous quality standards and certification processes, which can be time-consuming and costly. These regulatory hurdles may delay the introduction of innovative products, impacting market dynamics. Furthermore, while advancements in biocompatible materials have improved aligner quality, limitations still exist regarding long-term durability and environmental impact. The need for sustainable and recyclable materials is becoming increasingly critical, as the market seeks to align with global environmental goals. Addressing these material challenges while maintaining compliance adds complexity to the production process, potentially slowing growth in the short term.
Market Segmentation Analysis:
By Material
The 3D Printed Clear Dental Aligners market is segmented by material into thermoplastics and other biocompatible materials. Thermoplastics, such as polyurethane and polyethylene terephthalate glycol (PETG), dominate the market due to their flexibility, transparency, and durability. These materials provide the necessary strength to effectively realign teeth while ensuring patient comfort. Advancements in material science are enabling the development of innovative biocompatible materials that enhance performance, reduce discomfort, and extend aligner lifespan. However, the industry faces challenges in producing eco-friendly and recyclable materials to address growing environmental concerns. As sustainability becomes a focus, material innovation will remain a critical driver of market growth.
By Printing Technology
Segmentation by printing technology includes stereolithography (SLA), fused deposition modeling (FDM), and selective laser sintering (SLS), with SLA emerging as the preferred method. SLA technology offers high precision and smooth surface finishes, making it ideal for creating custom dental aligners. Its ability to produce complex geometries with accuracy has made it a standard in the industry. FDM, while cost-effective, is less commonly used due to its lower resolution. SLS, with its ability to process various materials, is gaining traction for research and specialty applications. Continued advancements in printing technology will play a pivotal role in reducing production costs and improving aligner quality.
Segments:
Based on Material:
- Polyethylene Terephthalate Glycol (PET-G)
- Polyurethane Resin (PU)
- Thermoplastic Polyurethane (TPU)
- Polycarbonate Resin
- Others
Based on Printing Technology:
- Stereolithography (SLA)
- Digital Light Processing (DLP)
- Material Jetting
- Others
Based on End User:
- Dental Hospitals
- Dental Offices and Oral Surgery Clinics
- Dental Laboratories
- Dental Group Practices
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the leading position in the 3D Printed Clear Dental Aligners market, accounting for approximately 40% of the global market share in 2024. This dominance is attributed to its advanced healthcare infrastructure, early adoption of cutting-edge technologies, and a strong focus on dental aesthetics and oral health. The United States, in particular, is the largest contributor, driven by a high prevalence of malocclusions, increasing disposable income, and a growing preference for minimally invasive orthodontic treatments. The region boasts a robust network of dental clinics, laboratories, and technology providers, which supports efficient aligner production and delivery. Direct-to-consumer models and tele-orthodontics platforms have gained significant traction, making aligners more accessible and affordable for a broader demographic. Moreover, favorable reimbursement policies, combined with substantial investments in research and development, strengthen the competitive landscape. The presence of key market players, coupled with ongoing technological advancements in 3D printing materials and methods, further positions North America as a hub for innovation and growth in the global market.
Asia-Pacific
Asia-Pacific is emerging as the fastest-growing region in the 3D Printed Clear Dental Aligners market, with its share expected to reach approximately 25% of the global market by 2032. This rapid growth is fueled by economic development, rising disposable incomes, and a burgeoning middle-class population that increasingly prioritizes dental aesthetics and oral health. Countries such as China, India, and Japan are driving regional growth due to their large patient bases, increasing awareness of orthodontic treatments, and expanding urbanization. The adoption of digital dentistry and advanced 3D printing technologies in urban centers has accelerated the production and delivery of high-quality aligners. Localized manufacturing, along with strategic partnerships between global and regional players, is addressing cost sensitivity and improving access to aligners in emerging markets. However, challenges such as limited infrastructure in rural areas, varying regulatory frameworks, and cost barriers persist. Despite these challenges, government initiatives to modernize healthcare systems, increasing private sector investments, and growing consumer demand are expected to sustain Asia-Pacific’s strong growth trajectory, solidifying its position as a vital contributor to the global market landscape.
Key Player Analysis:
- Align Technology, Inc.
- SmileDirectClub
- ClearCorrect LLC (Straumann Group)
- 3D System Inc.
- DynaFlex
- Prodways Group
- Graphy Inc.
- Abbott
- Formlabs
- Dentsply Sirona
Competitive Analysis:
The 3D Printed Clear Dental Aligners market is highly competitive, with several leading players driving innovation and market growth. Align Technology, Inc., SmileDirectClub, ClearCorrect LLC (Straumann Group), and Dentsply Sirona are major contributors to the market, capitalizing on their advanced technological capabilities and established brand reputations. Companies like 3D Systems Inc., Formlabs, and FORESTADENT focus on enhancing 3D printing technologies and materials to improve the accuracy, comfort, and affordability of aligners. Additionally, smaller yet significant players such as Graphy Inc. and Prodways Group are leveraging cutting-edge solutions to cater to niche markets. For instance, Align Technology has introduced new software innovations to accelerate digital practice transformation, enhancing the Invisalign treatment experience. The competition is intensified by the growing shift towards direct-to-consumer models, which disrupt traditional orthodontic delivery channels. As demand for customized and cost-effective solutions rises, key players are investing in research and development, forming strategic partnerships, and expanding into emerging markets to maintain competitive advantages.
Recent Developments:
- In January 2024, Align Technology, Inc. acquired Cubicure GmbH, a leader in direct 3D printing solutions, to expand its portfolio of 3D-printed products.
- In April 2023, LuxCreo, Inc. received U.S. FDA Class II 510(k) clearance for its LuxAlign, a comprehensive end-to-end workflow for 3D printed clear aligners.
- In March 2023, SMILE HEALTH ORTHODONTICS announced the addition of 3D printed clear aligners and 3D printed LightForce ceramic braces to its treatment offerings.
Market Concentration & Characteristics:
The 3D Printed Clear Dental Aligners market is moderately concentrated, with a mix of large, established players and smaller, emerging companies. The market is dominated by key players like Align Technology, Inc., SmileDirectClub, and ClearCorrect LLC (Straumann Group), which hold substantial market shares due to their advanced technologies, strong brand presence, and widespread distribution networks. These companies drive innovation in product development and lead the adoption of digital orthodontics. However, the market also features a growing number of niche players like LuxCreo, Inc. and 3D System Inc., which are contributing to technological advancements and specialized solutions. The competitive landscape is characterized by continuous innovation, particularly in 3D printing technologies, materials, and end-to-end digital workflows. Furthermore, the rise of direct-to-consumer models and tele-orthodontics is reshaping the market dynamics, enabling new entrants to compete with traditional orthodontic practices, fostering a dynamic and rapidly evolving market environment.
Report Coverage:
The research report offers an in-depth analysis based on Printing Technology, Material, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The 3D Printed Clear Dental Aligners market is expected to continue growing, driven by increasing consumer demand for aesthetic and personalized orthodontic solutions.
- Technological advancements in 3D printing, such as improved precision and faster production times, will enhance product quality and reduce costs.
- The adoption of AI and machine learning in aligner design and treatment planning will further streamline workflows and improve treatment outcomes.
- The expansion of direct-to-consumer business models will make aligners more accessible to a broader range of patients.
- There will be a shift towards more sustainable and eco-friendly 3D printing materials to align with environmental goals.
- Regional growth in Asia-Pacific, driven by increasing disposable incomes and urbanization, will significantly contribute to market expansion.
- Strategic partnerships and acquisitions, such as Align Technology’s acquisition of Cubicure GmbH, will drive innovation and market consolidation.
- The integration of tele-orthodontics and remote monitoring solutions will further shape the market by providing convenient treatment options.
- Consumer awareness and acceptance of clear aligners will continue to rise, benefiting from widespread marketing and education campaigns.
- Regulatory frameworks for 3D printed dental devices will evolve, ensuring higher quality standards and fostering greater industry trust.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the 3D Printed Clear Dental Aligners market?
What factors are driving the growth of the 3D Printed Clear Dental Aligners market?
What are the key segments within the 3D Printed Clear Dental Aligners market?
What are some challenges faced by the 3D Printed Clear Dental Aligners market?
Who are the major players in the 3D Printed Clear Dental Aligners market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 3D Printed Clear Dental Aligners Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global 3D Printed Clear Dental Aligners Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 398.1 million → 2032: USD 588.17 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 3D Printed Clear Dental Aligners Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. 3D Printed Clear Dental Aligners Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 3D Printed Clear Dental Aligners Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 3D Printed Clear Dental Aligners Market Drivers
- 3.3 3D Printed Clear Dental Aligners Market Restraints & Challenges
- 3.4 3D Printed Clear Dental Aligners Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 3D Printed Clear Dental Aligners Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 3D Printed Clear Dental Aligners Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, 3D Printed Clear Dental Aligners category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 3D Printed Clear Dental Aligners Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. 3D Printed Clear Dental Aligners Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the 3D Printed Clear Dental Aligners market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 3D Printed Clear Dental Aligners Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 3D Printed Clear Dental Aligners Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 3D Printed Clear Dental Aligners Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in 3D Printed Clear Dental Aligners (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New 3D Printed Clear Dental Aligners Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global 3D Printed Clear Dental Aligners Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America 3D Printed Clear Dental Aligners Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe 3D Printed Clear Dental Aligners Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific 3D Printed Clear Dental Aligners Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America 3D Printed Clear Dental Aligners Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East 3D Printed Clear Dental Aligners Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa 3D Printed Clear Dental Aligners Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. 3D Printed Clear Dental Aligners Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
