
Car Wheel Cap Market Overview:
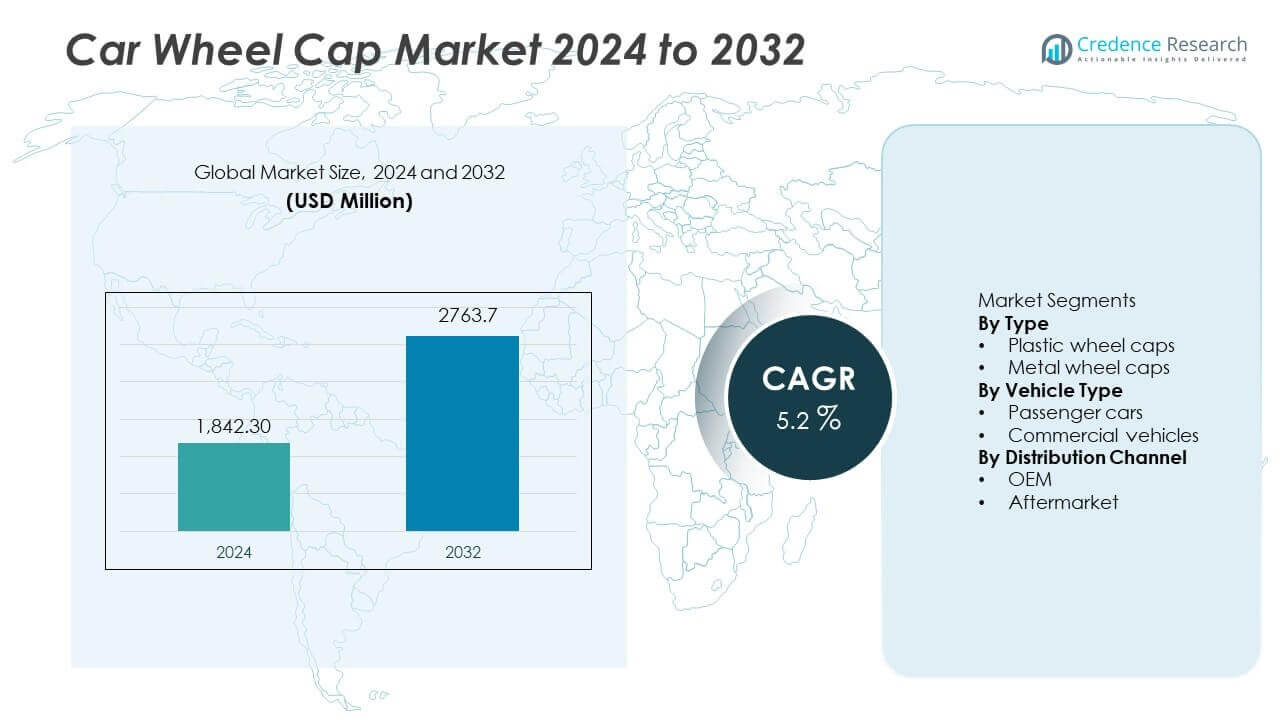
The global Car Wheel Cap market was valued at USD 1,842.30 million in 2024. It is expected to reach USD 2,763.7 million by 2032. This growth reflects a CAGR of 5.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Car Wheel Cap Market Size 2024 | USD 1,842.30 million |
| Car Wheel Cap Market, CAGR | 5.2% |
| Car Wheel Cap Market Size 2032 | USD 2,763.7 million |
Car Wheel Cap Market Insights
- Rising passenger car output drives demand, with passenger cars holding a 74% segment share and plastic wheel caps leading by type with a 68% share.
- Styling focus and cost control shape trends, as OEM channels dominate distribution with a 61% share, while aftermarket growth supports customization demand.
- Competitive intensity remains high, with global automakers relying on standardized designs, cost efficiency, and long-term supplier contracts to protect margins.
- Asia Pacific leads regional demand with a 42% market share, followed by North America at 24% and Europe at 22%, while Latin America and Middle East & Africa show steady replacement-led growth.
Car Wheel Cap Market Segmentation Analysis:
By Type
The By Type segment shows clear dominance of plastic wheel caps, which account for 68% market share. Plastic variants lead due to lower manufacturing costs, lighter weight, and strong design flexibility. Automakers prefer plastic wheel caps because these components support mass production and easier customization. High resistance to corrosion and improved surface finishes further strengthen adoption. Plastic caps also allow frequent style updates aligned with vehicle model refresh cycles. In contrast, metal wheel caps hold a smaller share due to higher material costs and weight concerns. Strong demand from entry-level and mid-range vehicles continues to support plastic wheel caps as the dominant sub-segment.
- For instance, Toyota uses injection-molded ABS wheel caps produced in cycle times below 60 seconds per unit for compact models.
By Vehicle Type
Within the By Vehicle Type segment, passenger cars dominate with a 74% market share. High global passenger vehicle production directly supports wheel cap demand. Consumers increasingly value exterior aesthetics, which drives replacement and upgrade purchases. Frequent use of wheel caps in hatchbacks, sedans, and compact SUVs strengthens this segment. Passenger cars also experience higher aftermarket replacement rates due to wear and styling preferences. Commercial vehicles contribute a smaller share, as fleet buyers prioritize durability over appearance. Rising personal vehicle ownership in emerging economies remains the key growth driver supporting passenger cars as the leading sub-segment.
- For instance, Volkswagen utilizes modular platform architectures to integrate standardized components across various vehicle models, which streamlines assembly lines and reduces manufacturing complexity.
By Distribution Channel
The By Distribution Channel segment is led by OEM sales with a 61% market share. Vehicle manufacturers integrate wheel caps during assembly to maintain design consistency and cost control. OEM supply ensures standardized fit, quality assurance, and brand alignment. Bulk procurement by automakers further strengthens OEM dominance. Aftermarket sales remain steady, driven by replacement demand and customization trends. However, price sensitivity and compatibility issues limit aftermarket penetration. Growth in new vehicle production and strong OEM relationships with component suppliers continue to drive OEM leadership across global markets.
Key Growth Drivers
Rising Global Passenger Vehicle Production
Growing passenger car production strongly drives the car wheel cap market. Automakers install wheel caps as standard exterior components. Higher output directly increases OEM demand volumes. Expanding urban populations support private vehicle ownership growth. Entry-level and mid-range vehicles rely heavily on wheel caps for cost control. Manufacturers favor wheel caps over alloy wheels in price-sensitive segments. Frequent model launches also raise component sourcing needs. Asia Pacific leads production growth across compact cars. Stable demand from Europe and North America supports replacement cycles. Continuous vehicle output expansion sustains long-term wheel cap consumption across regions.
- For instance, Hyundai Motor Company manufactured more than 4,200,000 passenger vehicles globally in a single year, requiring standardized wheel cap integration across multiple models.
Increasing Focus on Vehicle Aesthetics and Styling
Consumers place rising importance on vehicle appearance and personalization. Wheel caps offer a low-cost visual upgrade option. Automakers use caps to enhance exterior appeal without raising prices. Design variation supports brand identity and model differentiation. Buyers often replace worn caps to maintain vehicle look. Urban users value clean and modern wheel designs. Styling demand remains strong among first-time buyers. Compact and mid-size cars show high adoption rates. Visual enhancement needs drive steady aftermarket activity. Aesthetic preferences continue shaping product design and material selection strategies.
- For instance, Ford Motor Company introduced multiple wheel cap finish options across compact and mid-size passenger cars, with individual cap designs utilizing lightweight materials and enhanced aerodynamics to meet efficiency targets.
Cost Advantages Over Alloy Wheels
Wheel caps provide strong cost benefits versus alloy wheels. Manufacturers reduce overall vehicle production expenses. Lower raw material usage supports pricing control. Plastic wheel caps improve fuel efficiency through reduced weight. Cost-sensitive markets strongly prefer capped steel wheels. Fleet operators also choose caps for economic reasons. Easy replacement lowers maintenance spending. OEMs benefit from bulk sourcing efficiencies. Price stability attracts mass-market vehicle segments. Cost leadership remains a critical growth driver across emerging automotive economies.
Key Trends & Opportunities
Growth in Aftermarket Customization Demand
Customization trends create strong opportunities in the aftermarket channel. Consumers seek affordable styling upgrades post-purchase. Wheel caps allow easy design changes without technical complexity. Online retail expands access to diverse styles and finishes. Young car owners drive demand for sporty appearances. Seasonal replacements also support sales volumes. Custom branding options attract niche buyers. E-commerce platforms improve product visibility and reach. Urban markets show rising DIY replacement behavior. Aftermarket innovation creates incremental revenue beyond OEM supply chains.
- For instance, genuine vehicle component replacements may be available through authorized service centers, providing owners with authentic components designed for straightforward installation and a precise fit.
Advancements in Lightweight and Durable Materials
Material innovation opens new growth opportunities for wheel cap suppliers. High-grade polymers improve strength and finish quality. UV-resistant coatings extend product life cycles. Lightweight designs support vehicle efficiency goals. Improved molding techniques allow sharper aesthetics. Durable materials reduce cracking and fading issues. Automakers demand consistent quality across climates. Sustainable plastic blends gain attention among manufacturers. Technology-driven upgrades strengthen supplier competitiveness. Material advancement supports premium positioning within mass-market price ranges.
- For instance, Mahindra & Mahindra Ltd. utilizes reinforced ABS wheel caps designed to withstand extreme temperature fluctuations and ensure durability across diverse climates.
Key Challenges
Durability and Performance Limitations
Wheel caps face challenges related to durability under harsh conditions. Poor road quality increases breakage risk. Extreme temperatures cause material deformation over time. Low-cost products often suffer from poor fitment. Frequent replacements increase consumer dissatisfaction. Commercial vehicle use exposes caps to higher stress. Inferior finishes lead to fading and surface damage. Quality inconsistency affects brand perception. Manufacturers must balance cost and performance. Addressing durability concerns remains critical for long-term market credibility.
Intense Price Competition and Low Differentiation
The market experiences strong price-based competition among suppliers. Many products offer similar designs and functions. Low entry barriers increase supplier fragmentation. Price pressure reduces profit margins across regions. OEM buyers demand continuous cost reductions. Aftermarket sellers compete heavily on discounts. Limited differentiation restricts premium pricing ability. Counterfeit products further disrupt pricing structures. Brand loyalty remains weak in several markets. Companies must invest in design and quality to sustain margins.
Regional Analysis
North America
North America holds 24% market share in the car wheel cap market. Strong passenger car ownership supports steady demand. OEM installations dominate due to stable vehicle production levels. Consumers focus on durability and clean styling. Replacement demand remains consistent due to seasonal wear. Pickup trucks and compact SUVs support volume sales. The aftermarket benefits from frequent part replacements. Established supply chains improve product availability. High labor costs push automakers toward cost-effective components. Design standardization across models further supports wheel cap adoption.
Europe
Europe accounts for 22% market share in the car wheel cap market. Compact cars and hatchbacks dominate regional fleets. Automakers prioritize cost control and lightweight components. Wheel caps support emission reduction goals through weight savings. Strong replacement cycles drive aftermarket demand. Urban vehicle usage increases cosmetic wear. Regulatory pressure encourages standardized exterior components. OEM demand remains stable across Germany, France, and Italy. Consumer focus on aesthetics supports design upgrades. The market benefits from steady vehicle registrations and renewal trends.
Asia Pacific
Asia Pacific leads with 42% market share in the car wheel cap market. High vehicle production in China and India drives volume growth. Entry-level and mid-range cars dominate regional sales. Automakers favor wheel caps for cost efficiency. Rapid urbanization supports private vehicle ownership. Plastic wheel caps see strong penetration. Aftermarket demand grows due to high vehicle density. Local suppliers benefit from scale advantages. Price sensitivity shapes purchasing decisions. The region remains the primary growth engine for global demand.
Latin America
Latin America holds 7% market share in the car wheel cap market. Passenger car demand supports steady consumption. Economic recovery improves vehicle sales in Brazil and Mexico. Cost-sensitive buyers prefer wheel caps over alloys. OEM demand remains moderate but stable. Harsh road conditions increase replacement frequency. Aftermarket sales benefit from wear-related demand. Imports dominate supply in several countries. Limited local manufacturing affects pricing structures. Gradual improvement in vehicle production supports market stability.
Middle East & Africa
The Middle East & Africa region represents 5% market share in the car wheel cap market. Vehicle imports drive demand across Gulf countries. Passenger cars dominate usage patterns. High temperatures impact product durability. Replacement demand supports aftermarket sales. Fleet vehicles contribute to steady consumption. OEM installations grow with rising vehicle registrations. Price sensitivity influences product selection. Limited local manufacturing restricts customization options. Gradual infrastructure development supports long-term vehicle demand growth.
Car Wheel Cap Market Segmentations:
By Type
- Plastic wheel caps
- Metal wheel caps
By Vehicle Type
- Passenger cars
- Commercial vehicles
By Distribution Channel
- OEM
- Aftermarket
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape features Toyota Motor Corporation, Volkswagen AG, Hyundai Motor Company, General Motors Company, Ford Motor Company, Stellantis N.V., Honda Motor Co., Ltd., Nissan Motor Co., Ltd., Tata Motors Limited, and Mahindra & Mahindra Ltd. The market shows moderate fragmentation with strong OEM dominance. Automakers source wheel caps through long-term supplier contracts to ensure cost control. Design standardization supports scale efficiency and faster model rollouts. Leading players focus on material optimization to reduce weight and improve durability. Plastic wheel caps remain central to volume strategies. Regional suppliers compete on pricing and fit accuracy. Aftermarket competition intensifies through customization options and faster distribution. Technology upgrades emphasize surface finish, UV resistance, and snap-fit precision. Price competition remains strong across mass segments. Brand differentiation stays limited at the component level. Strategic focus centers on production efficiency, supplier consolidation, and stable OEM relationships.
Key Player Analysis
- Toyota Motor Corporation
- Volkswagen AG
- Hyundai Motor Company
- General Motors Company
- Ford Motor Company
- Stellantis N.V.
- Honda Motor Co., Ltd.
- Nissan Motor Co., Ltd.
- Mahindra & Mahindra Ltd.
- Tata Motors Limited
Recent Developments
- In March 2025, Toyota Kirloskar Motor launched the Hilux Black Edition with new 18-inch black alloy wheels and matching customized hub caps in India.
- In 2025, Volkswagen offers genuine valve caps and wheel accessories with embossed VW logos to protect valve stems on models like Taigun.
Report Coverage
The research report offers an in-depth analysis based on Type, Vehicle Type, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Vehicle production growth will continue to support steady wheel cap demand across mass-market segments.
- Passenger cars will remain the primary consumption base due to high ownership levels.
- Plastic wheel caps will maintain dominance because of cost and weight advantages.
- OEM channels will retain leadership through standardized vehicle assembly practices.
- Aftermarket sales will expand with rising customization and replacement needs.
- Design innovation will focus on improved aesthetics and surface durability.
- Lightweight materials will gain importance to support efficiency targets.
- Emerging markets will drive volume growth through entry-level vehicle sales.
- Competitive pressure will encourage cost optimization and supplier consolidation.
- Consistent replacement demand will support long-term market stability.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Global Passenger Vehicle Production
Increasing production of passenger vehicles, especially in emerging markets, directly boosts demand for car wheel caps as these are standard exterior components installed by OEMs. Higher vehicle output translates to greater OEM procurement volumes and sustained market growth.
Increasing Focus on Vehicle Aesthetics and Styling
Consumers are placing more emphasis on the appearance and personalization of their vehicles, making wheel caps a popular, cost-effective way to enhance exterior styling. This trend drives both OEM integration and aftermarket replacement and upgrade purchases.
Cost Advantages Over Alloy Wheels
Plastic wheel caps offer significant cost and weight savings compared to alloy wheels, making them the preferred choice for entry-level and mid-range vehicles. Automakers and fleet operators favor wheel caps to control production costs and improve fuel efficiency.
Growth in Aftermarket Customization Demand
The rise of customization trends and online retail channels has expanded the aftermarket for wheel caps, as consumers seek affordable and easy-to-install styling upgrades. This supports incremental sales beyond the OEM channel, especially among younger and urban car owners.
Advancements in Lightweight and Durable Materials
Innovations in high-grade polymers and UV-resistant coatings have improved the durability and finish of wheel caps, supporting longer product life and better aesthetics. These material advancements help suppliers meet OEM requirements and appeal to quality-conscious consumers.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Car Wheel Cap market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Car Wheel Cap market projected to grow between 2024 and 2032?
Which Car Wheel Cap market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Car Wheel Cap market?
Who are the leading companies in the Car Wheel Cap market?
Which region commanded the largest share of the Car Wheel Cap market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Plastic wheel caps
- 1.2.2 Metal wheel caps
- 1.3 By Vehicle Type
- 1.3.1 Passenger cars
- 1.3.2 Commercial vehicles
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,842.30 million → 2032: USD 2,763.7 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Car Wheel Cap Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Car Wheel Cap Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Car Wheel Cap Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Car Wheel Cap Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Car Wheel Cap Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Car Wheel Cap Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Car Wheel Cap Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Car Wheel Cap Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,842.30 million → 2032: USD 2,763.7 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Car Wheel Cap Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Plastic wheel caps
- 12.3.7.2 Metal wheel caps
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Vehicle Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Passenger cars
- 12.4.7.2 Commercial vehicles
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Car Wheel Cap Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Car Wheel Cap Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Car Wheel Cap Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Toyota Motor Corporation
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Volkswagen AG
- 17.4 Hyundai Motor Company
- 17.5 General Motors Company
- 17.6 Ford Motor Company
- 17.7 Stellantis N.V.
- 17.8 Honda Motor Co., Ltd.
- 17.9 Nissan Motor Co., Ltd.
- 17.10 Mahindra & Mahindra Ltd.
- 17.11 Tata Motors Limited
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

