
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Africa Green Data Center Market Size 2024 | USD 2,675.08 million |
| Africa Green Data Center Market, CAGR | 17.45% |
| Africa Green Data Center Market Size 2032 | USD 9,686.56 million |
Market Overview
The Africa Green Data Center Market is projected to grow from USD 2,675.08 million in 2024 to an estimated USD 9,686.56 million by 2032, with a compound annual growth rate (CAGR) of 17.45% from 2025 to 2032. This significant expansion reflects the continent's increasing demand for sustainable digital infrastructure, driven by rapid digitalization, rising data consumption, and a growing emphasis on energy-efficient technologies.
Key drivers of this growth include government incentives, such as tax breaks and the establishment of Special Economic Zones (SEZs), which encourage investments in green data centers. Additionally, the deployment of submarine cables and inland connectivity enhancements are improving internet access, further fueling demand. The trend towards modular and scalable data center solutions is also gaining traction, offering energy-efficient options that align with sustainability goals.
Geographically, South Africa leads the market, with significant developments also occurring in Kenya, Nigeria, and Egypt. Major players shaping the Africa Green Data Center landscape include Teraco Data Environments (Digital Realty), Open Access Data Centres, Telecom Egypt, and Africa Data Centres. These companies are investing in expanding their presence to meet the growing demand for green data infrastructure across the continent
Market Insights
- The Africa Green Data Center Market is expected to grow from USD 2,675.08 million in 2024 to USD 9,686.56 million by 2032, with a CAGR of 17.45% from 2025 to 2032, driven by digitalization and energy efficiency trends.
- The global Green Data Center Market is expected to grow from USD 59,645.02 million in 2024 to USD 239,470.06 million by 2032, at a CAGR of 18.98% from 2025 to 2032.
- Government incentives such as tax breaks, the establishment of Special Economic Zones (SEZs), and enhanced connectivity through submarine cables fuel market growth.
- Increasing demand for sustainable infrastructure across industries, alongside the rise of cloud computing, AI, and big data analytics, is driving green data center investments.
- High energy costs and unreliable power supply in certain African regions remain challenges for green data center expansion and operations.
- Limited access to renewable energy sources and upfront investment costs for green infrastructure hinder widespread adoption, particularly in underserved regions.
- South Africa leads the market, with significant growth also occurring in Kenya, Nigeria, and Egypt, due to their strategic locations and strong digital infrastructure.
- Other regions in Sub-Saharan Africa are expected to see gradual growth as the demand for localized green data centers increases, helping bridge the digital divide.
Report Scope
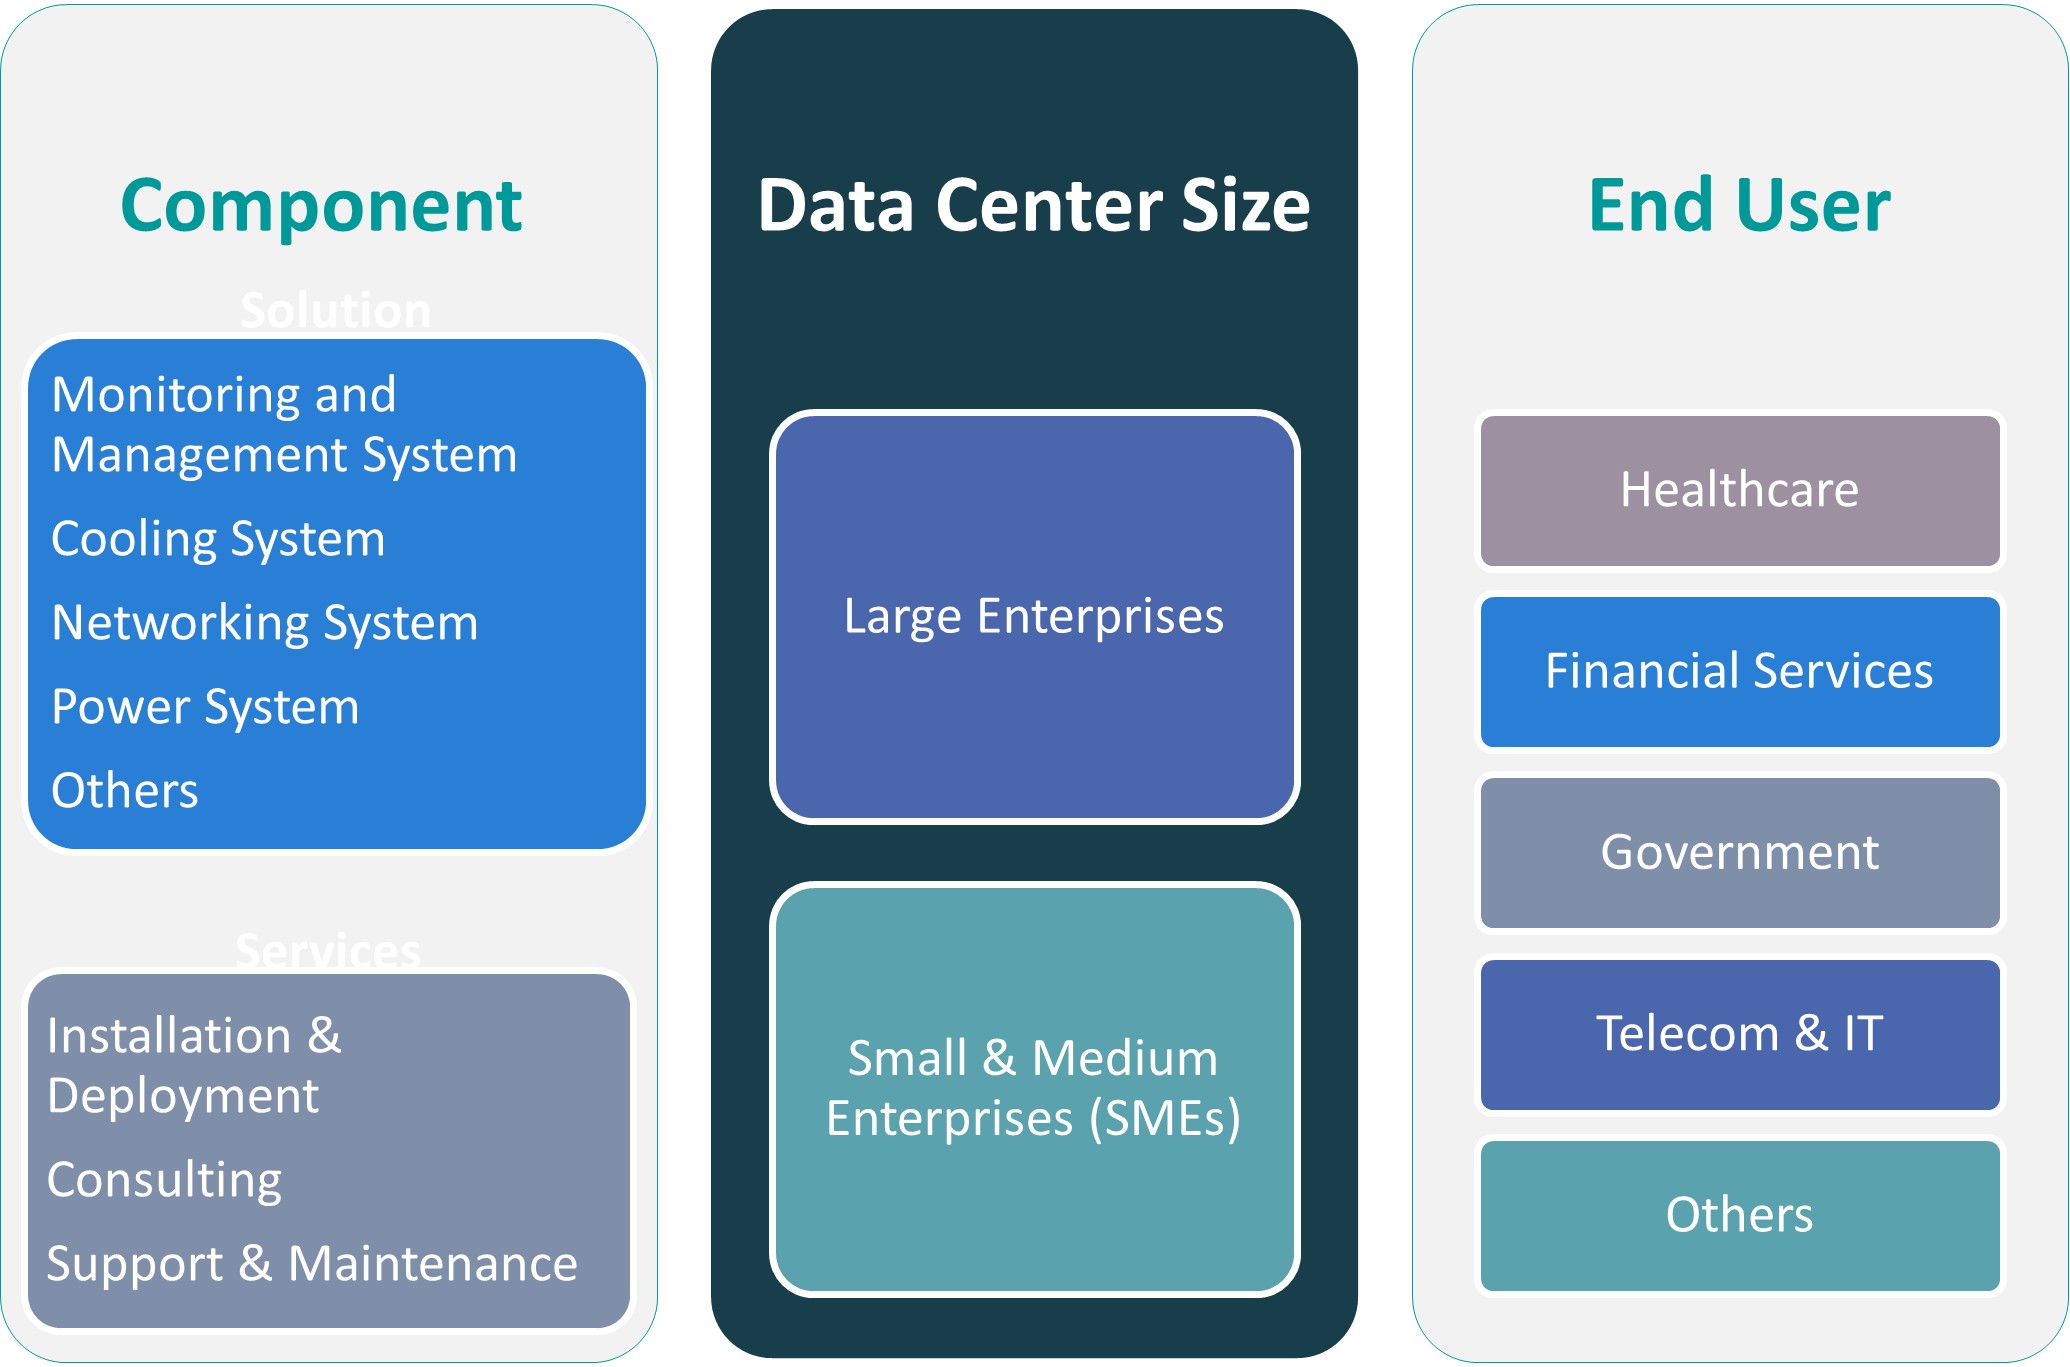
This report segments the Africa Green Data Center Market as follows:
Market Drivers
Strategic Government Initiatives and Incentives
Supportive government policies, tax incentives, and infrastructure development programs are playing a crucial role in accelerating the growth of green data centers in Africa. Several African nations have recognized the strategic importance of data center infrastructure in economic development and are introducing initiatives to attract foreign and local investment in the sector. Countries like South Africa, Kenya, Nigeria, and Egypt are offering benefits such as land grants, reduced import duties on IT equipment, and streamlined regulatory processes to encourage the development of environmentally sustainable data facilities. Additionally, governments are collaborating with international development organizations and private players to build renewable energy capacity that supports green data center operations. The establishment of Special Economic Zones (SEZs) and Technology Parks is further facilitating the growth of these facilities by providing essential resources and connectivity in a centralized location. Such initiatives reduce entry barriers for investors and create a favorable ecosystem for green infrastructure to thrive. These policy-driven efforts ensure that Africa remains an attractive destination for data center investment while aligning with sustainable development objectives.
Expansion of Renewable Energy Infrastructure
The development of renewable energy sources such as solar, wind, hydro, and geothermal is significantly contributing to the rise of green data centers in Africa. The continent possesses vast untapped renewable energy potential, and numerous countries are actively investing in clean energy to diversify their power mix and improve energy reliability. The availability of abundant solar radiation in regions like North Africa and Sub-Saharan Africa offers an ideal environment for solar-powered data centers. Furthermore, renewable energy projects are receiving support from global financial institutions, development banks, and sustainability-focused investors. As data centers are highly power-dependent, access to clean, stable, and cost-effective energy sources is essential for sustainable operation. By integrating renewable energy into their operations, green data centers in Africa not only reduce operational expenditure but also minimize dependence on fossil fuels, ensuring long-term energy security. This alignment with environmental goals makes such facilities more attractive to multinational corporations and cloud providers committed to carbon neutrality. In the long term, the synergy between green data centers and renewable energy infrastructure is expected to catalyze broader economic and technological advancement across the continent.
Rising Demand for Energy-Efficient and Sustainable Infrastructure
The growing emphasis on energy conservation and carbon emission reduction is a pivotal driver behind the expansion of green data centers in Africa. As global and regional awareness of climate change intensifies, organizations are under increasing pressure to adopt environmentally sustainable practices. Traditional data centers are energy-intensive, consuming vast amounts of electricity and contributing significantly to greenhouse gas emissions. In contrast, green data centers are designed to optimize power usage through advanced cooling systems, renewable energy integration, and energy-efficient hardware, thereby minimizing environmental impact. In Africa, where energy costs are high and power supply can be inconsistent, the need for energy-efficient infrastructure is even more critical. For instance, green data centers in Africa are leveraging renewable energy sources like solar and wind to ensure reliability and reduce operating costs. These facilities also support corporate social responsibility (CSR) goals, enhancing the reputation of companies that adopt them. Moreover, global climate pacts and sustainable development goals (SDGs) are pushing both public and private sectors to prioritize green infrastructure, making green data centers a strategic investment.
Digital Transformation and Data Localization Policies
Africa is undergoing a digital revolution marked by a surge in internet penetration, mobile device usage, cloud computing, and smart technologies. This rapid digital transformation is driving a massive increase in data generation, requiring advanced data storage and processing infrastructure. Governments and businesses across the continent are actively digitizing services, including healthcare, finance, education, and public administration, creating a booming demand for robust data centers. Additionally, data sovereignty and localization policies are emerging in various African nations to ensure that citizen and enterprise data is stored within national borders. For instance, cloud service providers and telecom operators are investing in local green data centers that comply with regulatory frameworks while providing efficient and secure services. Many of these facilities are being built with green technologies to align with global ESG (Environmental, Social, and Governance) goals, further driving momentum in the green data center segment.
Market Trends
Rise of Hyperscale and Colocation Facilities
The Africa Green Data Center Market is witnessing a significant surge in hyperscale and colocation facility developments. Driven by the exponential growth in cloud computing, big data analytics, and enterprise digitization, major technology providers are investing heavily in large-scale green infrastructure. Hyperscale data centers offer massive computing capacity and are typically designed with advanced energy management systems, including renewable energy integration, liquid cooling technologies, and smart energy-efficient architecture. At the same time, colocation facilities provide space and services for multiple businesses within a shared green-certified environment, reducing the environmental footprint compared to independently operated data centers. Companies such as Africa Data Centres (ADC), Teraco (Digital Realty), and Open Access Data Centres (OADC) are leading this expansion with multiple sustainable projects across strategic African hubs such as Johannesburg, Nairobi, Lagos, and Cairo. These facilities support growing demand from cloud service providers like AWS, Microsoft Azure, and Google Cloud, which are also emphasizing carbon neutrality and sustainability in their regional infrastructure strategies. Moreover, financial institutions, healthcare organizations, and e-commerce platforms are increasingly opting for colocation services to scale efficiently while meeting green compliance standards. As the digital economy expands and businesses prioritize environmentally responsible IT operations, hyperscale and colocation facilities built on green principles are becoming central to Africa’s data center ecosystem.
Integration of Advanced Cooling and Efficiency Technologies
A critical trend shaping the Africa Green Data Center Market is the integration of advanced cooling technologies and intelligent energy management systems to enhance operational efficiency. In hot and humid climates typical of many African regions, conventional air-cooling methods result in excessive energy consumption and high operating costs. As a response, green data centers are adopting cutting-edge cooling solutions such as liquid immersion cooling, direct-to-chip cooling, evaporative cooling, and free air cooling, depending on local climate suitability. These technologies significantly reduce Power Usage Effectiveness (PUE) ratios and extend equipment life by maintaining optimal thermal conditions.In addition to cooling innovations, facilities are incorporating AI-based energy management systems to monitor and optimize energy consumption in real time. Machine learning algorithms can forecast power usage patterns, identify inefficiencies, and dynamically adjust cooling and power distribution systems to ensure minimal waste. Furthermore, smart grid integration enables data centers to tap into clean energy when available, further reducing dependency on fossil fuels. Such innovations not only enhance sustainability metrics but also improve cost-efficiency, offering competitive advantages to operators in the evolving African market. This trend reflects a broader shift toward intelligent, automation-driven infrastructure that balances performance with environmental stewardship. As technology matures and becomes more accessible, the widespread adoption of these efficiency-enhancing tools is expected to become a defining feature of Africa’s next-generation green data centers.
Adoption of Renewable Energy-Powered Data Centers
One of the most prominent trends in the Africa Green Data Center Market is the increasing adoption of renewable energy sources to power data center operations. For instance, a leading data center operator in Kenya has integrated geothermal energy into its facilities, leveraging the country's abundant geothermal resources to supply approximately 85% of the center's power needs sustainably. Similarly, in South Africa, a major data center provider has installed solar photovoltaic panels capable of generating 2 megawatts of clean energy annually, significantly reducing reliance on grid electricity. Operators are also investing in advanced battery storage systems that can store up to 500 kilowatt-hours, addressing power intermittency and ensuring operational continuity. Countries like Morocco are also making strides, with wind energy projects being integrated into data center operations to support hyperscale facilities. For instance, a Moroccan data center partnered with a renewable energy provider to source 100% of its electricity from wind farms, equating to an annual reduction of over 10,000 metric tons of CO2 emissions. This trend is further bolstered by international investors prioritizing green infrastructure in their funding criteria, driving the adoption of renewable energy-powered data centers across the continent.
Expansion of Edge and Modular Data Centers
The rising demand for low-latency services, real-time analytics, and localized computing has fueled the expansion of edge and modular data centers across Africa. For instance, a telecom company in Nigeria has deployed modular data centers in secondary cities, each consuming only 30 kilowatts of power while supporting up to 500 terabytes of localized data processing. These prefabricated units are equipped with advanced cooling systems, reducing energy consumption by nearly 40%, and renewable energy sources, such as solar panels, generating up to 200 kilowatt-hours per day. In Kenya, an Internet Service Provider (ISP) has established edge data centers powered by hydroelectric energy to support IoT applications and real-time data processing for smart agriculture projects, processing over 100,000 data points daily. Similarly, in South Africa, a cloud service operator has implemented modular green data centers to support e-health initiatives, ensuring compliance with data localization regulations while optimizing performance for mission-critical applications like telemedicine and patient record analytics. The deployment of 5G networks across the continent is further accelerating the need for edge computing capabilities. For instance, a leading telecom provider in the region has integrated multimode dark fiber to interconnect edge facilities with central data centers, enabling seamless data transmission at speeds exceeding 100 gigabits per second. These efforts are bridging the digital divide and enhancing the reach of digital transformation in Africa, particularly in underserved and rural areas.
Market Challenges
Inadequate Power Infrastructure and High Energy Costs
The Africa Green Data Center Market faces significant challenges, particularly the inadequacy of reliable power infrastructure across several regions. For instance, many African countries struggle with unstable electricity grids, frequent power outages, and limited access to high-capacity energy sources, especially in rural and semi-urban areas. This unreliable power supply poses significant risks to data center uptime, making energy redundancy and backup systems essential for operation. However, these systems-especially when powered by diesel generators-often contradict the environmental objectives of green data centers. Additionally, energy costs in Africa are considerably higher than the global average, particularly in countries with limited or underdeveloped energy infrastructure. For instance, renewable energy presents a viable solution, but the initial capital investment for deploying solar farms, wind turbines, or geothermal plants-especially at scale-is substantial. Many developers and operators lack access to affordable financing for these green energy solutions, slowing adoption and expansion. Furthermore, even when renewable energy sources are available, integrating them into national grids can be complex due to outdated transmission and distribution networks. This power-related constraint not only limits the scalability of green data centers but also raises their operational costs, which can hinder competitiveness compared to other global markets. Addressing this challenge will require coordinated efforts from governments, utilities, and private stakeholders to modernize power infrastructure, promote clean energy investments, and introduce policies that support the long-term financial viability of green energy solutions in data center operations.
Limited Technical Expertise and Skilled Workforce
Another significant challenge in the Africa Green Data Center Market is the shortage of skilled professionals with expertise in designing, building, and managing sustainable data center operations. Green data centers require specialized knowledge in areas such as energy-efficient architecture, renewable energy integration, thermal management, and advanced IT infrastructure. However, many African countries face a talent gap in these critical fields due to limited educational programs, training initiatives, and professional development opportunities. The lack of experienced engineers, data center architects, and energy management specialists often results in increased dependence on foreign consultants and international firms. This reliance can lead to higher costs and project delays, as well as limited knowledge transfer to local professionals. Moreover, the absence of localized standards and certification programs tailored to the unique environmental and technical conditions in Africa exacerbates the challenge of building a qualified domestic workforce capable of supporting long-term green data center growth. To address this challenge, public and private stakeholders must invest in workforce development initiatives, including vocational training, university partnerships, and professional certification programs focused on green technologies and data center engineering. Encouraging local participation in international sustainability and IT infrastructure forums can also help bridge the knowledge gap. Without a well-trained workforce, the continent risks lagging in the adoption of globally competitive green data center practices, undermining the broader goals of sustainability, digital inclusion, and economic transformation.
Market Opportunities
Untapped Digital Infrastructure Potential Across Emerging Economies
Africa presents a substantial opportunity for green data center development due to its underpenetrated digital infrastructure and increasing digital connectivity. As internet penetration, mobile device usage, and cloud adoption continue to rise, there is growing demand for local data hosting, processing, and storage solutions. Countries such as Ethiopia, Uganda, Ghana, and Rwanda are witnessing rapid growth in digital services but lack the data center capacity to support these needs sustainably. Green data centers provide an optimal solution by combining digital infrastructure development with environmental responsibility. With large tracts of land available for scalable deployment and abundant solar and wind resources, the continent is ideally positioned to develop energy-efficient, eco-friendly data center ecosystems that can serve local, regional, and international clients.
Strategic Investment Opportunities Driven by ESG and Localization Trends
The convergence of environmental, social, and governance (ESG) investment strategies and rising data localization requirements across Africa offers a compelling opportunity for investors and technology providers. Governments are increasingly enforcing data sovereignty laws, encouraging the establishment of locally hosted infrastructure to ensure data privacy and national security. At the same time, international corporations and hyperscalers are seeking to align with global climate goals by expanding their presence in green-certified facilities. These factors create a favorable climate for foreign direct investment, public-private partnerships, and multilateral financing to support the development of sustainable data centers. Market entrants that prioritize sustainability, innovation, and compliance with local regulations stand to benefit significantly from early-mover advantages in this rapidly evolving sector.
Market Segmentation Analysis
By Component
The green data center market in Africa is segmented by various components, including solutions and services. The monitoring and management system holds a significant share, as data center operators prioritize real-time monitoring of power usage, cooling efficiency, and resource optimization. These systems play a critical role in minimizing energy consumption and ensuring that facilities remain energy-efficient. Cooling systems are another key component in green data centers, as they help reduce energy consumption, especially in regions with hot climates. Advanced cooling techniques such as free-air cooling, liquid cooling, and evaporative cooling are being implemented to improve efficiency. The networking system is also a crucial part of the data center's infrastructure, providing high-speed communication and connectivity. Power systems, which include backup power solutions and integration with renewable energy sources, are essential for the continuous operation of green data centers. Additionally, other components like fire suppression systems and security infrastructure contribute to the overall performance and sustainability of the facilities. On the services side, installation and deployment services are in high demand, as companies require expertise in setting up sustainable infrastructure. Consulting services are gaining traction, helping businesses optimize their data center operations to meet green certifications. Support and maintenance services ensure the long-term functionality and efficiency of these facilities.
By Data Center Type
Data centers in Africa are categorized into large enterprises and small and medium enterprises (SMEs). Large enterprises dominate the market, driven by the increasing demand for cloud computing, big data analytics, and storage solutions. These large-scale data centers are often built to handle massive amounts of data, providing cost-efficient, high-performance computing capabilities. SMEs are also contributing to the growth of the market, albeit at a smaller scale. As digital transformation accelerates, SMEs are looking for scalable, energy-efficient data center solutions that align with their sustainability goals. The rise of modular and edge data centers is also empowering SMEs to access green infrastructure without significant upfront investments, making it an attractive option for smaller businesses seeking localized and cost-effective solutions.
Segments
Based on Component
- Solution
- Monitoring and Management System
- Cooling System
- Networking System
- Power System
- Others
- Services
- Installation & Deployment
- Consulting
- Support & Maintenance
Based on Data Center Type
- Large Enterprises
- Small & Medium Enterprises (SMEs)
Based on End User
- Healthcare
- Financial Services
- Government
- Telecom & IT
- Others
Based on Region
- South Africa
- Kenya
- Nigeria
- Egypt
- other
Regional Analysis
South Africa (40%)
South Africa remains the dominant region in the African Green Data Center Market, holding a significant share of approximately 40% of the total market. The country’s well-developed infrastructure, stable power supply, and strategic location make it a prime destination for large-scale data center investments. Johannesburg and Cape Town are emerging as major hubs for green data centers, with several global cloud providers and tech giants setting up sustainable facilities. South Africa's government has implemented favorable policies that promote renewable energy and energy-efficient data center practices, which has further attracted international players. The country is also positioning itself as the gateway to Sub-Saharan Africa, offering excellent connectivity to neighboring regions.
Kenya (15%)
Kenya is another significant player, holding a market share of around 15%. The East African nation has witnessed rapid growth in cloud adoption, mobile penetration, and data storage requirements, particularly driven by the fintech, e-commerce, and mobile industries. Nairobi has become a regional data center hub, with several international companies establishing green-certified facilities. The Kenyan government’s focus on renewable energy, especially geothermal, solar, and wind power, has played a vital role in enabling the development of sustainable data centers in the region.
Key players
- Raxio Group
- Teraco Data Environments
- MainOne
- Huawei Technologies
- DCB
Competitive Analysis
The Africa Green Data Center Market is highly competitive, with key players such as Raxio Group, Teraco Data Environments, MainOne, Huawei Technologies, and DCB leading the way. Raxio Group has established a strong foothold in East Africa, offering high-quality, sustainable data center solutions. Teraco Data Environments remains the market leader in South Africa, focusing on high-capacity, energy-efficient data centers and strong network connectivity. MainOne is a significant player in West Africa, capitalizing on its strategic location and extensive fiber infrastructure to support cloud and digital services. Huawei Technologies plays a vital role in offering cutting-edge infrastructure and cloud services, driving the adoption of advanced technologies in green data centers across Africa. DCB, while smaller, continues to grow by offering specialized data center services with an emphasis on energy efficiency and local market knowledge. The combined efforts of these players will accelerate the growth and sustainability of Africa's digital infrastructure
Recent Developments
- In December 2023, Vertiv acquired CoolTera Ltd., a provider of liquid cooling infrastructure solutions. This acquisition strengthens Vertiv's capabilities in high-densitcompute cooling, aligning with the industry's shift towards energy-efficient data center technologies.
- In July 2024, Huawei unveiled three green data center facility solutions at the Global Smart Data Center Summit. These include the AeroTurbo fans, IceCube polymer heat exchangers, and iCooling AI energy efficiency cooling solutions, designed to optimize cooling efficiency and reduce energy consumption.
- In May 2024, Microsoft launched its first hyperscale cloud data center region in Mexico, located in Querétaro. This facility aims to provide scalable, highly available, and resilient cloud services, supporting digital transformation and sustainable innovation in the region.
- In June 2024, HPE partnered with Danfoss to introduce the HPE IT Sustainability Services – Data Center Heat Recovery. This turnkey heat recovery module helps organizations manage and repurpose excess heat, contributing to more sustainable IT infrastructures.
- In November 2024, Google announced a partnership with SB Energy Global to supply 942 MW of renewable energy to power its data center operations in Texas. This initiative supports Google's commitment to operate on carbon-free energy and aligns with its sustainability goals.
- In January 2025, AWS announced plans to invest approximately $11 billion in Georgia to expand its infrastructure, supporting cloud computing and AI technologies. This investment is expected to create at least 550 new high-skilled jobs and enhance the state's digital innovation capabilities.
- In May 2024, IBM announced a partnership with Schneider Electric to develop and deploy energy-efficient data center solutions, focusing on reducing carbon emissions and improving operational efficiency.
Market Concentration and Characteristics
The Africa Green Data Center Market is moderately concentrated, with a mix of local and international players vying for market share. Leading firms such as Teraco Data Environments, Raxio Group, and MainOne dominate the market, especially in regions like South Africa, Kenya, and Nigeria. These players are well-established, leveraging robust infrastructure, strong financial backing, and regional expertise to cater to the growing demand for sustainable, energy-efficient data centers. However, there is also space for emerging companies and new entrants to capitalize on the expanding opportunities in underserved markets across Sub-Saharan Africa. The market is characterized by increasing competition, technological innovation, and a focus on renewable energy integration, as companies strive to meet environmental sustainability goals while addressing the region's digital infrastructure needs. With strong government support and the rising adoption of cloud services, the market is expected to see both consolidation and new entries in the coming years.
Report Coverage
The research report offers an in-depth analysis based on Component, Data Center Type, End User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The rising demand for cloud computing, AI, and big data analytics will drive significant growth in green data centers. This trend is fueled by digital transformation across industries such as finance, healthcare, and telecom.
- Africa's vast renewable energy potential, including solar, wind, and geothermal, will play a pivotal role in powering green data centers. Increased investments in solar-powered and wind energy solutions are expected to reduce operational costs and environmental impact.
- Governments across Africa are focusing on green infrastructure through favorable policies and incentives. The implementation of data sovereignty laws and renewable energy targets will further promote sustainable data center development.
- Global data center operators, including Amazon Web Services and Google Cloud, are expected to increase investments in Africa’s green data centers. Their commitment to sustainability will encourage more players to adopt energy-efficient solutions.
- The growth of IoT, 5G, and real-time analytics will accelerate the need for edge and modular data centers in Africa. These decentralized facilities will enhance local data processing and reduce latency while remaining energy-efficient.
- Advancements in cooling technologies, such as liquid immersion and evaporative cooling, will continue to reduce energy consumption in Africa’s green data centers. These systems will optimize resource usage, particularly in hot climates.
- The market will witness consolidation as key players form strategic partnerships to meet growing demand. Collaborations between data center operators, telecom providers, and energy companies will enhance service delivery.
- Countries with stringent data localization regulations will push companies to invest in local green data centers. This trend will drive more data center projects across the continent, ensuring compliance with national data sovereignty laws.
- Energy efficiency will be a key competitive factor in the African market. Companies will increasingly pursue certifications like LEED and ISO 50001 to demonstrate their commitment to sustainability and attract eco-conscious clients.
- The growth of the green data center industry will contribute to job creation across Africa. Increased demand for skilled workers in data center management, energy efficiency, and IT infrastructure will promote local talent development and technical expertise.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Strategic Government Initiatives and Incentives
Supportive government policies, tax incentives, and infrastructure programs - such as Special Economic Zones and reduced import duties - are attracting both local and foreign investment in green data centers, lowering entry barriers and fostering a favorable ecosystem for sustainable infrastructure.
Expansion of Renewable Energy Infrastructure
Africa's vast solar, wind, hydro, and geothermal resources are increasingly being harnessed to power data centers, reducing operational costs and carbon emissions while ensuring long-term energy security and attracting multinational clients committed to sustainability.
Rising Demand for Energy-Efficient and Sustainable Infrastructure
With high energy costs and unreliable power supply in many regions, organizations are prioritizing green data centers that leverage advanced cooling, renewable integration, and energy-efficient hardware to minimize environmental impact and operating expenses.
Digital Transformation and Data Localization Policies
Rapid digitalization across sectors and emerging data sovereignty regulations are driving demand for local, green-certified data centers that comply with national laws and support secure, efficient digital services.
Growth of Hyperscale, Colocation, and Edge Facilities
The surge in cloud computing, IoT, and real-time analytics is fueling investment in hyperscale, colocation, and modular edge data centers, which are designed for energy efficiency and scalability, supporting Africa's evolving digital economy.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Africa Green Data Center Market in 2023, 2032, and its CAGR?
What are the key drivers of growth in the Africa Green Data Center Market?
. Which regions are leading the Africa Green Data Center Market?
Who are the major players in the Africa Green Data Center Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Healthcare
- 1.2.2 Financial Services
- 1.2.3 Government
- 1.2.4 Telecom & IT
- 1.2.5 Others
- 1.3 By Component
- 1.3.1 Solution
- 1.3.2 Monitoring and Management System
- 1.3.3 Cooling System
- 1.3.4 Networking System
- 1.3.5 Power System
- 1.3.6 Others
- 1.3.7 Services
- 1.3.8 Installation & Deployment
- 1.3.9 Consulting
- 1.3.10 Support & Maintenance
- 1.4 By Data Center Type
- 1.4.1 Large Enterprises
- 1.4.2 Small & Medium Enterprises (SMEs)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,675.08 million → 2032: USD 9,686.56 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Africa Green Data Center Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Africa Green Data Center Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Africa Green Data Center Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Africa Green Data Center Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Africa Green Data Center Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Africa Green Data Center Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Africa Green Data Center Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Africa Green Data Center Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,675.08 million → 2032: USD 9,686.56 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Africa Green Data Center Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Healthcare
- 12.3.7.2 Financial Services
- 12.3.7.3 Government
- 12.3.7.4 Telecom & IT
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Solution
- 12.4.7.2 Monitoring and Management System
- 12.4.7.3 Cooling System
- 12.4.7.4 Networking System
- 12.4.7.5 Power System
- 12.4.7.6 Others
- 12.4.7.7 Services
- 12.4.7.8 Installation & Deployment
- 12.4.7.9 Consulting
- 12.4.7.10 Support & Maintenance
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Data Center Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Large Enterprises
- 12.5.7.2 Small & Medium Enterprises (SMEs)
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Africa Green Data Center End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Africa Green Data Center Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Country-Level Shares, 2024
- 14.2 Country Market Size Comparison, 2024
- 14.3 Country Market Forecasts, 2024-2032
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 Africa Green Data Center Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Africa Green Data Center Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Teraco Data Environments
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Raxio Group
- 18.4 MainOne
- 18.5 Huawei Technologies
- 18.6 DCB
- 18.7 Africa Data Centres
- 18.8 Open Access Data Centres
- 18.9 Telecom Egypt
- 18.10 Vertiv
- 18.11 Schneider Electric
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

