
Agricultural and Farm Machinery Market Overview:
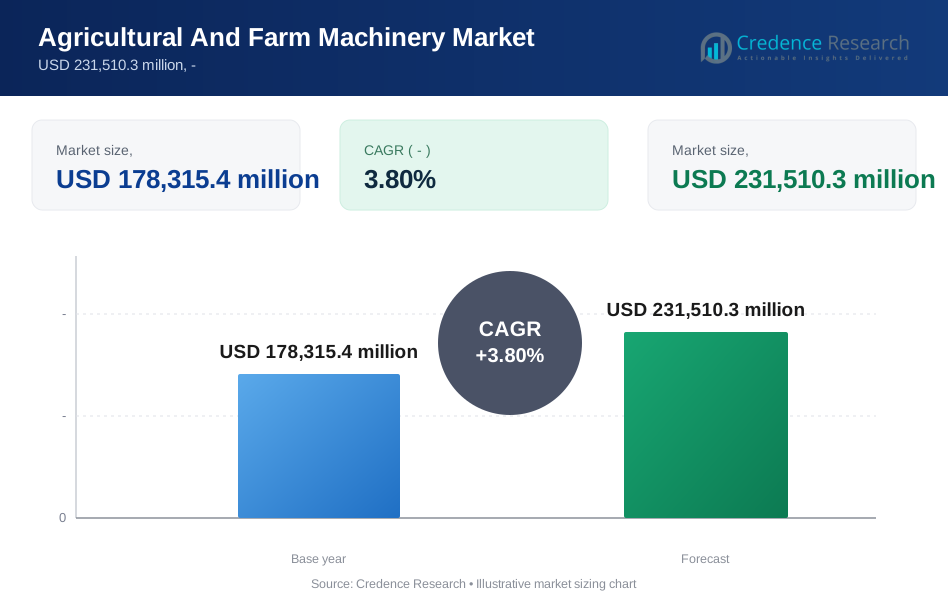
The Agricultural and Farm Machinery Market is projected to grow from USD 178,315.4 million in 2025 to an estimated USD 231,510.3 million by 2032, with a compound annual growth rate (CAGR) of 3.8% from 2025 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Agricultural and Farm Machinery Market Size 2025 | USD 178,315.4 million |
| Agricultural and Farm Machinery Market, CAGR | 3.8% |
| Agricultural and Farm Machinery Market Size 2032 | USD 231,510.3 million |
Agricultural and Farm Machinery Market Insights:
- Strong demand for tractors, harvesters, planting tools, and irrigation systems drives machinery adoption among farms seeking higher productivity and reduced labor dependence.
- Precision agriculture, connected platforms, and predictive maintenance capabilities strengthen user confidence in deploying advanced machinery across varied field conditions.
- High upfront costs, limited financing access, and slow replacement cycles restrict faster uptake among smallholder farms in developing regions.
- Asia Pacific leads global demand due to rapid mechanization and strong government support for machinery access across expanding crop belts.
- North America shows strong traction for autonomous and sustainable machinery models that improve efficiency and reduce environmental impact.
- Europe remains competitive through strict environmental rules, advanced farming practices, and ongoing transition to fuel-efficient and digitally integrated machines.

Agricultural and Farm Machinery Market Drivers
Growing Shift Toward Precision Agriculture to Improve Productivity and Reduce Input Losses
Precision tools raise farm output by guiding data-based decisions across large fields. Farmers use GPS guidance, variable-rate technology, and remote sensors to reduce waste and control soil variability. Demand grows where users want machines that cut fuel use and lower fertilizer loads. The Agricultural and Farm Machinery Market gains momentum when farms deploy automated tractors and connected sprayers. Farmers trust these machines to stabilize yields under changing land conditions. Drone-based scouting supports faster detection of stress in high-value crops. Crop monitoring platforms help producers plan daily tasks with higher accuracy. It strengthens machinery purchases due to clear gains in field efficiency.
- For instance,John Deere’s See & Spray™ Ultimate technology utilizes computer vision and machine learning to distinguish weeds from crops in real-time; internal testing and field data demonstrate that this system can reduce herbicide use by up to 77% while maintaining a spray accuracy of over 95% at speeds of up to 12 mph.
Rapid Mechanization Across Developing Economies Driven by Labor Shortages and Higher Food Needs
Farm operators adopt machinery to manage growing labor gaps during planting and harvest seasons. Rising rural migration increases pressure on farms to complete core tasks within narrow time windows. Tractors, harvesters, and power tillers enable farmers to handle larger areas with fewer workers. The Agricultural and Farm Machinery Market expands in countries where governments support mechanized programs. Subsidy schemes speed adoption among small and mid-scale growers. Local manufacturing improves access to affordable models that match regional field conditions. Training centers help operators use new machines safely and correctly. It creates an ecosystem that supports long-term machinery penetration.
- For instance,Mahindra & Mahindra has aggressively expanded its "Tringo" farm equipment rental platform in India, which has successfully digitized over 100,000 farmers, providing access to high-HP tractors that have increased land preparation efficiency by 40% for smallholders who previously relied on manual labor or draught animals.
Increasing Focus on Sustainable Farming and Lower Carbon Emissions Through Cleaner Machinery
Sustainability programs push farms to shift toward electric, hybrid, or low-emission engines. Manufacturers launch cleaner machines to meet strict environmental rules in major food-producing nations. Battery-powered tractors appeal to growers who want quiet, low-maintenance alternatives. The Agricultural and Farm Machinery Market progresses when farmers want durable designs that reduce environmental impact. Sensors track fuel consumption and highlight areas where emissions decline further. Biofuel-ready engines gain acceptance among large farms that need dependable power output. Research groups test renewable energy systems on prototype machines to support green transitions. It helps the sector align with rising sustainability targets.
Digital Integration Across Machinery Platforms to Improve Decision Support and Farm Coordination Digital tools unify machinery, agronomic data, and logistics on centralized platforms. Users link tractors, sprayers, and seeders with cloud systems for real-time performance insights. Predictive maintenance alerts reduce breakdowns and protect expensive assets. The Agricultural and Farm Machinery Market benefits where connected devices streamline daily field plans. Dealers offer remote diagnostics to guide users during urgent machine faults. Automated recordkeeping improves compliance for regulated crops. Telemetry tools support better cost control over fuel, labor, and machine hours. It strengthens the role of digital ecosystems in modern farm operations.
Agricultural and Farm Machinery Market Trends
Expansion of Autonomous and Semi-Autonomous Machinery to Reduce Human Intervention in Field Tasks
Manufacturers introduce autonomous tractors to help farms complete soil prep, seeding, and spraying with little manual control. Advanced sensors guide navigation in open fields and complex terrains. Machine vision improves obstacle detection under low-light or dusty conditions. The Agricultural and Farm Machinery Market witnesses steady demand for platforms that reduce operator fatigue. Remote oversight allows a single worker to manage multiple machines during long work cycles. Software upgrades refine route planning and task precision over time. Trials in large farms show strong performance during continuous operations. It reinforces the growth of autonomous solutions across major cropping regions.
- For instance,John Deere’s 8R Autonomous Tractor utilizes six pairs of stereo cameras and a 360-degree obstacle detection system that processes images at 100 milliseconds per frame, allowing the machine to operate with a spatial accuracy of within 1 inch without a driver present in the cab.
Rising Adoption of Robotics for Harvesting, Weeding, and High-Value Crop Management
Robotic tools address repetitive jobs that require high accuracy and steady performance. Berry and vegetable growers use mechanical pickers to improve speed and protect product quality. Vision-guided weeders cut chemical use and safeguard soil health across diverse fields. The Agricultural and Farm Machinery Market gains traction where robots support specialty crop producers. Compact robotic carriers transport loads across orchards and vineyards. Light detection systems help robots identify ripe produce during peak harvest windows. New prototypes improve grip strength for delicate crops. It pushes robotics deeper into commercial farming operations.
- For instance,Carbon Robotics’ Autonomous LaserWeeder leverages 30 high-powered CO2 lasers and thermal energy to eliminate weeds at a rate of 200,000 weeds per hour, providing a solution that reduces weed control costs by up to 80% compared to traditional hand-labor or chemical methods.
Integration of Advanced Materials in Machinery Design for Durability and Lower Maintenance Needs
Manufacturers deploy stronger alloys, composites, and reinforced polymers to extend machine life. Lighter frames improve maneuvering in tight field spaces and reduce operator strain. Corrosion-resistant parts support machinery exposed to humid or chemical-heavy environments. The Agricultural and Farm Machinery Market grows where users want robust machines that stay reliable under heavy workloads. High-strength blades and components maintain sharpness during continuous tillage. Upgraded hydraulic systems improve load tolerance during transport. New coatings protect moving parts from abrasion. It supports longer equipment cycles with fewer service breaks.
Growth in Smart Implements Capable of Real-Time Adjustments Based on Soil and Crop Conditions
Smart implements adapt seeding depth, spray rates, or tillage intensity during each pass. Sensors read soil moisture, density, and surface residue to guide immediate adjustments. On-board controllers help growers match machine output with field variation. The Agricultural and Farm Machinery Market shifts where farmers prioritize data-driven control. Agronomic algorithms refine decisions for specific field types. Cloud updates keep implements aligned with modern farming rules. dealers promote smart package bundles that include compatible sensors and monitors. It encourages farms to upgrade to more responsive machinery systems.
Agricultural and Farm Machinery Market Challenges Analysis
High Upfront Costs, Limited Financing Access, and Slow Replacement Cycles Affect Machinery Purchases
Farm operators hesitate when machine prices strain budgets during tight seasons. Financing programs remain weak in many rural regions, which restricts timely purchases. The Agricultural and Farm Machinery Market experiences slower momentum when farmers postpone upgrades. Long machine life reduces replacement frequency in cost-sensitive markets. Repair expenses rise when older tractors and implements stay in use. Price volatility in steel and components influences equipment affordability. Smallholders face difficulty securing loans for premium technologies. It creates an uneven adoption pattern across regions.
Skill Gaps, Low Digital Literacy, and Infrastructure Constraints Limit Technology Deployment
Farm workers need training to operate advanced machines without errors. Digital tools require stable connectivity that many rural belts cannot guarantee. The Agricultural and Farm Machinery Market faces barriers when users lack confidence in modern software. Limited dealer networks restrict timely access to spare parts. Farms struggle when technicians are unavailable for machine faults during peak seasons. Software-enabled machines demand stronger cybersecurity and reliable data storage. Resistance to new technology rises when users fear system complexity. It slows full-scale digital integration across farms.
Agricultural and Farm Machinery Market Opportunities
Growing Demand for Smart, Connected, and Automated Machinery Across Commercial Farms
Large farms want connected tractors and sprayers to manage tight planting and harvest windows. Smart dashboards guide operators through complex field plans and daily machine tasks. The Agricultural and Farm Machinery Market benefits when users deploy automation to cut waste. Predictive analytics highlight maintenance needs early to reduce downtime. Opportunities rise where farms adopt cloud platforms for unified equipment control. Remote support increases trust among growers who depend on timely advice. Specialized implements allow farms to target crop traits with higher precision. It supports future investment in advanced machinery ecosystems.
Rising Interest in Sustainable, Fuel-Efficient, and Electric Machinery Models
Producers focus on equipment that reduces soil disturbance and emissions. Electric tractors appeal to users who want lower noise, low maintenance, and reliable torque. The Agricultural and Farm Machinery Market gains from policies that reward green machinery adoption. Hybrid engines help large operations maintain power while reducing fuel loads. Biofuel-ready machines attract growers in regions with strong crop residue programs. Green financing programs support farmers who shift to cleaner fleets. Cleaner implements protect soil structure during repeated field passes. It positions sustainability at the center of machinery upgrades.
Agricultural and Farm Machinery Market Segmentation Analysis:
By Type of Machinery
Tractors hold a dominant presence in the Agricultural and Farm Machinery Market due to their central role in soil preparation, material handling, and transport. Users prefer models ranging from compact to high-horsepower variants to match diverse field sizes. Harvesters gain strong traction where farms seek faster throughput and reduced crop loss during peak seasons. Planting equipment supports uniform seed placement to improve crop stands across large and small farms. Tillage equipment remains essential for soil conditioning in regions with intensive farming. Irrigation equipment expands where farms need precise water control to stabilize yields under shifting climate patterns.
- For instance,CLAAS integrated the CEMOS (Electronic Machine Optimization System) into its LEXION combine harvesters; independent testing by DLG (German Agricultural Society) confirmed that this automated technology increases throughput by 12% while simultaneously reducing grain loss to less than 1% of the total harvest volume.
By Power Source
Power sources influence machinery preference across varied operations. Internal combustion engines maintain broad adoption due to their durability and strong torque output. Electric models gain interest in controlled environments and operations focused on reduced emissions. Hybrid machinery offers a balance between fuel savings and sustained performance during long cycles. Solar-powered equipment appeals to farms that seek low-energy tools for remote locations. The Agricultural and Farm Machinery Market uses these power categories to support a wide range of field tasks.
- For instance,Monarch Tractor launched the MK-V, a fully electric, driver-optional smart tractor equipped with a battery that provides over 14 hours of runtime; the platform delivers 40 hp (peak 70 hp) and provides twice the torque of a comparable diesel engine, allowing for zero-emission operations in vineyards and orchards.
By Application
Applications define the core use cases that guide machine selection across farm types. Crop production remains the largest segment, driven by demand for tractors, planting equipment, harvesters, and irrigation tools. Livestock farming relies on feed preparation, material handling, and pasture maintenance machinery. Aquaculture uses pumps, aeration systems, and handling tools to manage daily operations. Forestry applies specialized equipment for land clearing, thinning, and haulage. It supports varied production systems through machines built for specific field and environmental conditions.
By Functionality
Functionality segments reflect how machinery supports critical stages of the production cycle. Plowing prepares soil structure for better root development and moisture retention. Sowing equipment ensures uniform distribution of seeds across varied crop belts. Fertilizing tools help users apply nutrients with precision to improve plant growth. Harvesting machinery secures timely grain and forage collection during narrow crop windows. The Agricultural and Farm Machinery Market aligns each functional stage with specialized tools that improve efficiency and output stability.
Segmentation:
By Type of Machinery
- Tractors
- Harvesters
- Planting Equipment
- Tillage Equipment
- Irrigation Equipment
By Power Source
- Internal Combustion Engine
- Electric
- Hybrid
- Solar Powered
By Application
- Crop Production
- Livestock Farming
- Aquaculture
- Forestry
By Functionality
- Plowing
- Sowing
- Fertilizing
- Harvesting
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America maintains a strong position in the Agricultural and Farm Machinery Market, accounting for nearly 28% share due to high mechanization levels across the United States and Canada. Farmers use advanced tractors, harvesters, and digital systems to raise productivity under tight labor supply. Manufacturers introduce autonomous and electric models to support sustainability goals. The region benefits from strong dealership networks that ensure timely service and upgrades. Demand grows within large commercial farms that require continuous operational efficiency. It strengthens regional investment in connected machinery platforms.
Europe holds approximately 25% share, driven by strict environmental rules and advanced farming practices. Users prefer fuel-efficient tractors and precision tools that reduce input waste. Strong agricultural economies in Germany, France, and Italy support consistent equipment replacement cycles. The Agricultural and Farm Machinery Market gains support from EU-funded smart farming programs. Adoption rises where farms integrate guidance systems, robotics, and engineered implements. Manufacturers expand production centers across the region to improve access and reduce import dependence. It supports long-term modernization efforts in diverse crop belts.
Asia Pacific leads the global landscape with nearly 34% share, supported by large agricultural populations in China, India, and Southeast Asia. Rising food demand pushes growers to shift from manual methods to mechanized tools. Governments provide subsidies to encourage tractor, harvester, and irrigation equipment purchases. The region records rapid growth within small and mid-sized farms adopting entry-level machinery. Users shift toward compact tractors and affordable implements suited to fragmented landholdings. The Agricultural and Farm Machinery Market expands as domestic manufacturing capabilities rise. It accelerates regional deployment of machinery across both staple and high-value crops.
Key Player Analysis:
- Deere & Company (John Deere)
- AGCO Corporation
- CNH Industrial N.V.
- Kubota Corporation
- CLAAS KGaA mbH
- Mahindra & Mahindra
- Escorts Kubota
- S.T Tillers Tractors Ltd.
- JCB
- Arvind
- Same Deutz-Fahr (SDF Group)
- Vermeer Corporation
Competitive Analysis:
Competition in the Agricultural and Farm Machinery Market centers on technological innovation, product range, and global distribution strength. Leading companies such as John Deere, CNH Industrial, AGCO, Kubota, and CLAAS invest in autonomous systems, electric models, and smart implements to meet evolving farm needs. The market shifts toward digital ecosystems that combine machinery, sensors, and cloud platforms for real-time decision support. Manufacturers expand dealer networks to improve service delivery and strengthen customer loyalty. Pricing strategies remain important in regions with strong demand for affordable equipment. The Agricultural and Farm Machinery Market rewards companies that balance advanced features with operational durability. It encourages firms to pursue partnerships, software integration, and localized manufacturing to secure long-term advantage.
Recent Developments:
- In August 2025, CNH Industrial announced a refreshed lineup of agricultural equipment for the 2026 model year featuring redesigned tractors from 20 to over 700 horsepower with enhanced cabins, larger fuel tanks, precision AI technologies like agronomic sensors and FieldOps™ platform, and brands New Holland and Case IH.
- In August 2025, John Deere completed the full acquisition of GUSS Automation, a leader in autonomous orchard and vineyard sprayers enabling one operator to supervise up to eight machines via GPS and LiDAR for precision spraying.
Report Coverage:
The research report offers an in-depth analysis based on Type of Machinery, Power Source, Application, and Functionality. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand strengthens across major crop-producing regions as farms adopt connected machinery to improve operational accuracy and reduce resource loss.
- Users shift toward autonomous tractors that support long work cycles and limit dependence on seasonal labor shortages.
- Electric and hybrid models gain attention as sustainability programs push growers to adopt cleaner machinery fleets.
- Smart implements expand across mid-sized farms due to rising interest in variable-rate control and real-time soil insights.
- Digital service platforms grow because users want predictive maintenance and remote diagnostics to protect machinery uptime.
- Compact and affordable tractors gain higher traction in emerging markets where smallholder farms seek mechanization.
- Irrigation equipment adoption rises with increasing pressure to manage water resources through precise delivery systems.
- Harvesting equipment upgrades accelerate as farms require faster throughput to manage variable weather windows.
- Partnerships among manufacturers and software firms rise to integrate advanced data tools into core machinery lines.
- Global production footprints diversify to reduce supply disruptions and support faster regional equipment access.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Agricultural and Farm Machinery Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Agricultural and Farm Machinery Market projected to grow between 2025 and 2032?
Which Agricultural and Farm Machinery Market segment held the largest share in 2025?
What are the primary factors fueling the growth of the Agricultural and Farm Machinery Market?
Who are the leading companies in the Agricultural and Farm Machinery Market?
Which region commanded the largest share of the Agricultural and Farm Machinery Market in 2025?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Agricultural And Farm Machinery Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Agricultural And Farm Machinery Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 178,315.4 million → forecast year: USD 231,510.3 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Agricultural And Farm Machinery Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Agricultural And Farm Machinery Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Agricultural And Farm Machinery Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Agricultural And Farm Machinery Market Drivers
- 3.3 Agricultural And Farm Machinery Market Restraints & Challenges
- 3.4 Agricultural And Farm Machinery Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Agricultural And Farm Machinery Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Agricultural And Farm Machinery Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Agricultural And Farm Machinery category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Agricultural And Farm Machinery Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Agricultural And Farm Machinery Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Agricultural And Farm Machinery market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Agricultural And Farm Machinery Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Agricultural And Farm Machinery Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Agricultural And Farm Machinery Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Agricultural And Farm Machinery (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Agricultural And Farm Machinery Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Agricultural And Farm Machinery Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Agricultural And Farm Machinery Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Agricultural And Farm Machinery Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Agricultural And Farm Machinery Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Agricultural And Farm Machinery Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Agricultural And Farm Machinery Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Agricultural And Farm Machinery Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Agricultural And Farm Machinery Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
