
Chestnuts Market Overview:
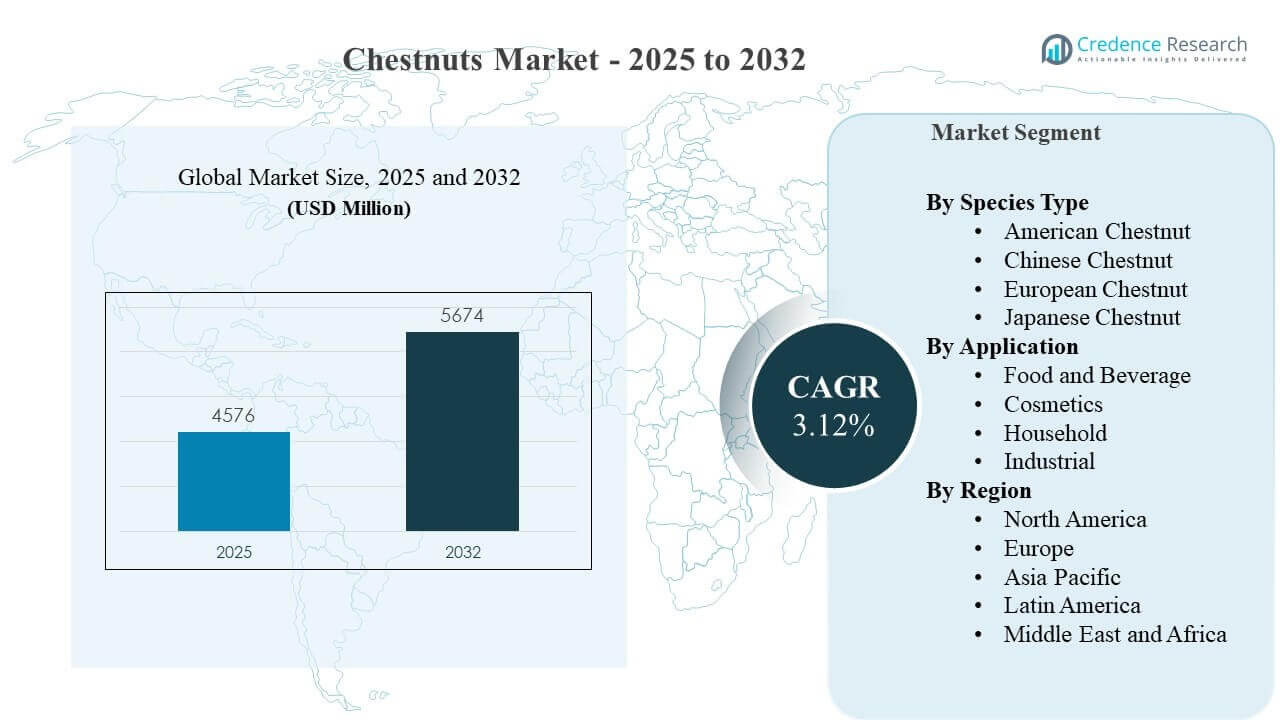
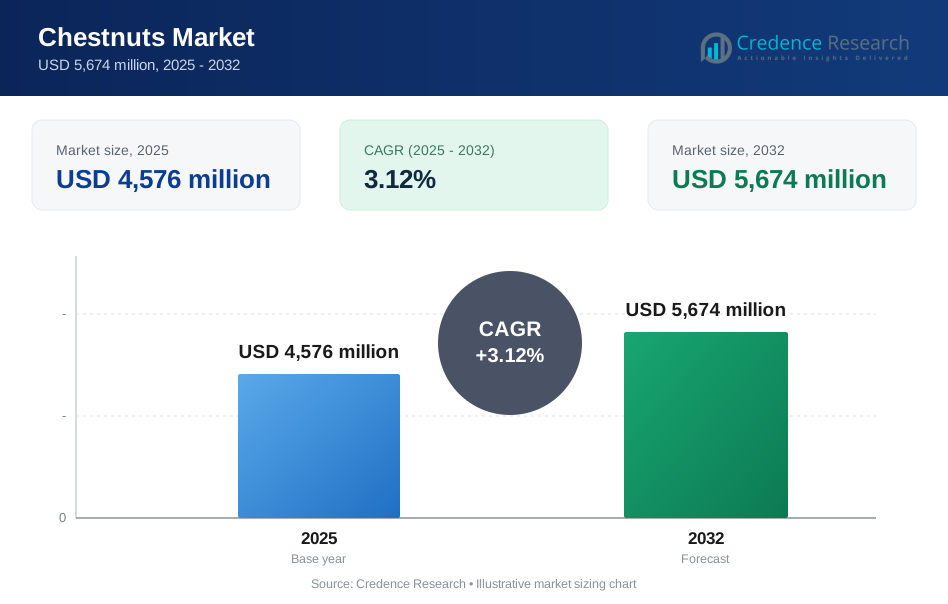
The global Chestnuts Market size was estimated at USD 4,576 million in 2025 and is expected to reach USD 5,674 million by 2032, growing at a CAGR of 3.12% from 2025 to 2032. Expanding demand for value-added chestnut formats such as peeled, frozen, purée, and flour is the strongest growth driver because these formats reduce preparation friction and make chestnuts easier to integrate into high-volume food applications. Asia Pacific remains the structural center of supply and processing, supporting scale-led availability and trade flows.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Chestnuts Market Size 2025 | USD 4,576 million |
| Chestnuts Market, CAGR | 3.12% |
| Chestnuts Market Size 2032 | USD 5,674 million |
Key Market Trends & Insights
- The Chestnuts Market is projected to increase from USD 4,576 million (2025) to USD 5,674 million (2032), representing a CAGR of 3.12% during 2025–2032.
- Asia Pacific led the regional landscape with a 75.9% share in 2025, reflecting concentration of cultivation, processing capacity, and domestic consumption.
- Food and Beverage remained the largest application with a 70.8% share in 2025, supported by bakery, confectionery, desserts, and seasonal snack demand.
- Chinese Chestnut accounted for the largest species share of 37.6% in 2025 due to supply depth and processing suitability for ingredient-grade formats.
- Europe represented 12.1% of 2025 revenue, sustained by established consumption cultures and premium value-added product positioning.
Segment Analysis
Chestnuts Market demand is primarily shaped by food-led consumption, where chestnuts function both as a seasonal snack and as an ingredient in bakery, confectionery, and prepared foods. Growth is increasingly supported by value-added processing that enables year-round availability and consistent product performance for manufacturers. Retail expansion and stronger cold-chain execution improve accessibility for fresh and ready-to-use formats, supporting higher purchase frequency. Premiumization is also visible in origin, grading, and packaging cues that influence consumer willingness to pay and retailer assortment decisions.
The category is also benefiting from ingredient diversification, particularly through chestnut flour and chestnut-derived ingredients used in plant-forward and wheat-reduced formulations. Ingredient adoption is strongest when suppliers can provide consistent specifications, stable shelf life, and dependable volumes. Foodservice demand contributes by favoring formats that improve kitchen throughput and portion consistency, especially in desserts and fillings. Overall, processing capability and quality control increasingly determine competitiveness more than commodity positioning alone.
By Species Type Insights
Chinese Chestnut accounted for the largest share of 37.6% in 2025. Chinese Chestnut leadership is supported by scale availability that improves supply continuity for both consumer packs and industrial ingredient formats. Processing suitability strengthens performance in peeled, frozen, and purée applications where yield consistency and defect control are essential. Commercial adoption is also supported when suppliers offer standardized grading and stable quality that reduces variability for downstream users.
By Application Insights
Food and Beverage accounted for the largest share of 70.8% in 2025. Food and Beverage leads because chestnuts are widely used in roasted snack formats, bakery and confectionery recipes, dessert fillings, and seasonal gifting. Demand is further strengthened by convenient processed formats that reduce preparation time and expand usage occasions beyond harvest-linked windows. Product innovation in spreads, purées, and flour supports broader manufacturing adoption and recurring procurement patterns.
Chestnuts Market Drivers
Rising demand for value-added chestnut formats in packaged foods
Chestnuts Market growth is shifting from seasonal fresh buying toward value-added formats such as peeled, frozen, vacuum-packed, purée, and flour. These formats cut preparation time and deliver consistent performance for bakery, confectionery, desserts, and snack manufacturing. Food and Beverage leadership in 2025 keeps demand steady because chestnuts serve as both an ingredient and a finished snack. Format innovation extends consumption beyond roasting occasions and improves modern retail availability nationwide today.
- For instance, Qinhuangdao Yanshan Chestnut Co., Ltd. reports 4,000 tons of fresh chestnut storage, 3,000 tons of low-temperature storage, and annual purchase, storage, and processing volume of more than 6,000 tons, while its portfolio includes IQF roasted peeled chestnuts, chestnut paste, and chestnut powder, demonstrating how processing scale supports year-round value-added supply.
Expansion of modern retail and cold-chain availability
Modern retail expansion improves visibility, shelf presence, and distribution reliability for chestnuts and chestnut-based products. Stronger cold-chain capability makes fresh and ready-to-eat formats more viable and reduces shrink from spoilage and quality loss. Retail-ready packaging supports differentiation through origin cues, grading, and convenience messaging that enables premium positioning. Better in-store execution encourages household stocking and increases repeat purchases across both seasonal peaks and off-season periods, year-round for shoppers everywhere consistently.
- For instance, Terminio Frutta states that it stores fresh chestnut products at 0 to 4°C and frozen products at -18 to -20°C, with cell temperatures monitored continuously by computer systems that can trigger alarms in case of anomalies, showing how digital cold-chain control supports reliable retail distribution.
Ingredient diversification aligned to plant-forward and wheat-reduced formulation needs
Chestnuts Market demand benefits from broader use of chestnut flour and chestnut-derived ingredients in recipes that prioritize clean labels and reduced wheat dependence. Chestnut flour adds texture and mild sweetness to bakery and snack formulations and supports premium product positioning. Adoption improves when suppliers deliver consistent milling, controlled moisture, and stable shelf-life specifications. As manufacturers expand plant-forward portfolios, chestnut ingredients receive greater product-development focus and wider commercialization opportunities globally today.
Supply-chain scale advantages and processing capacity concentration
Asia Pacific leadership reflects structural advantages in cultivation scale and processing capacity that support global chestnut availability. Scale strengthens cost efficiency and export stability, serving industrial buyers that require standardized specifications and dependable volumes. Processing depth enables multiple formats from the same raw input stream, widening portfolio breadth and customer reach. Concentrated peeling, freezing, and packing capability improves quality control and competitiveness in value-added, ingredient-led, and private-label channels worldwide globally.
Chestnuts Market Challenges
Chestnuts Market faces quality and shelf-life constraints because chestnuts are sensitive to storage conditions and can experience spoilage, insect damage, and moisture-related defects. Quality variability increases rejection rates and can weaken trust for industrial buyers that require consistent input specifications. Cost pressure rises when sorting, peeling, and defect control require labor-intensive processes or specialized equipment. These constraints can limit scalability and reduce margin stability across the value chain.
- For instance, Volmar Packaging states that vacuum-packed precooked chestnuts can be stored for 6 to 12 months, while vacuum-packed raw chestnuts can last up to 3 months when kept at 0°C to 4°C, showing that shelf-life performance depends heavily on packaging technology and tightly controlled storage conditions.
Supply volatility is another challenge because yields and availability can fluctuate due to harvest conditions, orchard health, and localized disruptions. When raw material availability tightens, processors can struggle to maintain consistent output of peeled, frozen, or ingredient-grade products. Price variability can reduce retail sell-through and encourage substitution toward other nuts or ingredients in recipes. Import dependence in smaller regions adds exposure to logistics constraints, transit time, and currency-linked price movement.
Chestnuts Market Trends and Opportunities
Chestnuts Market opportunity is rising in premium and functional positioning where brands emphasize origin, quality grading, and clean-label attributes. Innovation in spreads, purées, and ready-to-eat packs supports more frequent consumption occasions and improves year-round demand stability. Suppliers that provide consistent specifications for industrial use can expand share in bakery and confectionery supply chains. Packaging formats that preserve freshness and reduce waste can improve retailer confidence and broaden distribution.
Another trend is commercialization of convenience-led formats that reduce preparation barriers for households and foodservice operators. Ready-to-cook peeled products and frozen formats support faster kitchen throughput and consistent portioning. Digital retail and specialty e-commerce expand access in regions where traditional distribution is limited, enabling incremental demand outside peak season. Ingredient-led partnerships with food manufacturers can embed chestnuts into recurring product lines rather than relying on seasonal spikes.
- For instance, M.G.M. reports that its Prontarroste chestnuts are homogeneously laser-etched and packed in stay-fresh zipper bags under an uninterrupted cold chain, giving them about 3 months of shelf life with about 2% weight loss versus 10–20% for traditional fresh chestnuts,
Regional Insights
North America
North America held a 7.4% share in 2025, supported by specialty retail, premium snacking, and ingredient demand linked to bakery and natural-food channels. Demand is concentrated in urban markets where seasonal categories receive stronger merchandising and higher willingness to pay. Growth is supported by increased availability of peeled, frozen, and shelf-stable formats that reduce preparation barriers. Expansion is also aided by product innovation that positions chestnuts within better-for-you snacking and premium dessert applications.
Europe
Europe accounted for 12.1% of 2025 revenue, reflecting established culinary traditions and stronger penetration of value-added consumption. Demand is supported by roasted chestnut culture, confectionery applications, and prepared products used in desserts and fillings. Premiumization through origin cues and quality grading supports pricing power across specialty retail. Stable demand is also linked to packaged formats that sustain consumption beyond seasonal windows.
Asia Pacific
Asia Pacific led the Chestnuts Market with a 75.9% share in 2025 due to dominance across cultivation, processing, and domestic consumption. Scale supports consistent supply for both retail packs and industrial ingredient usage, strengthening export-linked availability. Processing capacity enables broad format coverage, including peeled and ready-to-use variants suited to high-throughput applications. The regional ecosystem supports cost efficiency and standardized specifications, reinforcing long-term leadership.
Latin America
Latin America represented 2.8% of 2025 revenue, reflecting a comparatively smaller production footprint and lower habitual consumption. Demand tends to be concentrated in select countries and premium niches where imports are accessible through modern retail. Shelf-stable and frozen formats can improve availability and reduce constraints related to seasonality and logistics. Growth potential is tied to retail expansion and greater adoption of ingredient formats for desserts and bakery.
Middle East & Africa
Middle East & Africa held a 1.8% share in 2025, with demand concentrated in higher-income urban markets and import-led channels. Consumption is typically seasonal and sensitive to price positioning and availability of premium formats. Limited local production scale keeps the market reliant on imports, increasing logistics exposure. Incremental growth is linked to modern retail development and gifting-oriented premium categories.
Competitive Landscape
Chestnuts Market competition is shaped by sourcing reliability, processing capability, and the ability to deliver consistent quality across multiple formats. Suppliers differentiate through value-added offerings such as peeled and frozen chestnuts, purées, spreads, and flours that align with bakery, confectionery, and snack manufacturing requirements. Quality control, grading standards, and storage performance are critical because defects and spoilage can materially affect customer acceptance. Distribution partnerships and private-label programs further influence market access and volume stability.
Chengde Shenli Food Co., Ltd. is positioned around processing-led participation, where scale operations and standardized output can support competitiveness in both domestic and export-linked channels. Chengde Shenli Food Co., Ltd. can strengthen positioning by expanding value-added penetration and format breadth rather than relying on raw commodity dynamics. Consistent grading, defect control, and packaging formats aligned to industrial buyers can increase repeat procurement. Channel partnerships with ingredient distributors and retail customers can further expand reach and stabilize demand.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Chengde Shenli Food Co., Ltd.
- Chestnut Growers, Inc.
- Qinhuangdao Yanshan Chestnut Food Co., Ltd.
- Roland Foods, LLC
- Royal Nut Company
- Shandong Zhifeng Foodstuffs Co., Ltd.
- V. Besana S.p.A.
- ConAgra Foods, Inc.
- Clément Faugier
- Route 9 Cooperative
- Battistini Vivai
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Developments
- In March 2026, Red River Foods, Inc. and Agroforestry Partners, LLC signed a memorandum of understanding to collaborate on developing the U.S. chestnut market. The partnership is aimed at expanding domestic chestnut supply, assessing customer demand, developing and testing chestnut products, planning production volumes, and diversifying supply across the value chain.
- In January 2026, Foray Bioscience entered a commercialization partnership with West Coast Chestnut for fabricated seed technology for select chestnut varieties. The agreement is designed to speed up chestnut propagation, reduce the time needed to scale new cultivars, and includes a multi-year forward purchase agreement for fabricated seeds.
Report Scope
| Report Attribute | Details |
| Market size value in 2025 | USD 4576 million |
| Revenue forecast in 2032 | USD 5674 million |
| Growth rate (CAGR) | 3.12% (2025–2032) |
| Base year | 2025 |
| Forecast period | 2026-2032 |
| Quantitative units | USD million |
| Segments covered | By Species Type Outlook: American Chestnut, Chinese Chestnut, European Chestnut, Japanese Chestnut; By Application Outlook: Food and Beverage, Cosmetics, Household, Industrial |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Key companies profiled | Chengde Shenli Food Co., Ltd.; Chestnut Growers, Inc.; Qinhuangdao Yanshan Chestnut Food Co., Ltd.; Roland Foods, LLC; Royal Nut Company; Shandong Zhifeng Foodstuffs Co., Ltd.; V. Besana S.p.A.; ConAgra Foods, Inc.; Clément Faugier; Route 9 Cooperative; Battistini Vivai |
| No.of Pages | 327 |
Segmentation
By Species Type
- American Chestnut
- Chinese Chestnut
- European Chestnut
- Japanese Chestnut
By Application
- Food and Beverage
- Cosmetics
- Household
- Industrial
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size and forecast for the Chestnuts Market?
What is the CAGR of the Chestnuts Market?
What is the largest segment in the Chestnuts Market?
What factors are driving growth in the Chestnuts Market?
Who are the leading companies in the Chestnuts Market?
Which region leads the Chestnuts Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 4,576 million → 2032: USD 5,674 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2025
- 2.6.2 Forecast Period: 2025-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Chestnuts Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Chestnuts Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2025-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2025-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Chestnuts Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2025-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Chestnuts Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Chestnuts Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Chestnuts Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Chestnuts Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Chestnuts Market Outlook, 2025-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 4,576 million → 2032: USD 5,674 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Chestnuts Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Chestnuts Geographic Market Outlook, 2025-2032
- 13.1 Regional Market Size and Share, 2025
- 13.2 Regional Market Forecast, 2025-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Chestnuts Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Chestnuts Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

