
Market Overview
The Agricultural Ventilation Fans Market is projected to grow from USD 1,200.00 Million in 2024 to an estimated USD 1,780.36 Million by 2032, with a CAGR of 6.80% from 2024 to 2032. Market growth is driven by rising investment in livestock welfare, greenhouse climate control and energy-efficient air movement systems. North America leads market demand because large poultry and livestock operations continue to upgrade ventilation infrastructure for productivity, compliance and year-round environmental control.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2026-2032 |
| Agricultural Ventilation Fans Market Size 2024 | USD 1,200.00 million |
| Agricultural Ventilation Fans Market, CAGR | 6.8% |
| Agricultural Ventilation Fans Market Size 2032 | USD 1,780.36 million |
Market Insights
- North America held the leading regional position in 2024 with 32.0% of global revenue, supported by intensive poultry, swine and dairy production systems.
- Exhaust fans led the type segment with an estimated 38.0% share because they remain core equipment for removing heat, moisture and harmful gases from confined farm buildings.
- Poultry dominated the application segment with about 41.0% share as broiler and layer facilities depend on tightly managed airflow to protect flock health and feed conversion.
- Major companies shaping competition include Munters, Big Ass Fans, Vostermans Ventilation, Ziehl-Abegg and Systemair.
- Key market trend centers on adoption of energy-efficient, variable-speed and digitally controlled fan systems that improve climate precision while lowering electricity consumption.
Market Segmentation Analysis
By Type (Exhaust, Circulation, HVLS, Tunnel)
Exhaust fans held the largest share of the type segment in 2024 at an estimated 38.0%. Their dominance reflects broad use across poultry houses, livestock barns, greenhouses and storage units where operators prioritize removal of hot air, humidity, dust and ammonia. Demand remains strongest in enclosed and semi-enclosed production systems that require dependable static pressure performance, simple maintenance and cost-effective large-scale deployment.
By Application (Poultry, Livestock, Greenhouse, Storage)
Poultry accounted for the largest application share in 2024 at approximately 41.0%. Commercial broiler and layer farms rely on continuous ventilation to manage bird density, litter moisture, temperature swings and disease pressure. Strong replacement cycles, integrator-led capital spending and growing emphasis on feed efficiency continue to support purchasing of tunnel, circulation and exhaust fan systems in modern poultry houses.
By Mounting (Wall, Ceiling, Roof)
Wall-mounted systems led the mounting segment in 2024 with an estimated 49.0% share. Their leading position comes from straightforward installation, compatibility with tunnel and cross-ventilation layouts and easier servicing in barns and poultry sheds. Operators favor wall units because they fit retrofit projects well and provide flexible sizing across both naturally ventilated and mechanically ventilated agricultural structures.
By End User (Farms, Integrators, Commercial Growers)
Farms represented the largest end-user segment in 2024 with around 52.0% share. Independent and family-operated farms purchase ventilation fans to protect animal comfort, reduce mortality and stabilize crop or stored-product quality. This segment remains dominant because individual farms span poultry, dairy, swine and greenhouse operations, creating broad recurring demand for both new installations and equipment replacement.
Key Growth Drivers
Rising pressure to manage heat stress and indoor air quality in livestock facilities
Agricultural producers increasingly treat ventilation as production-critical infrastructure rather than auxiliary equipment. Poultry, swine and dairy operations now run at higher stocking densities, tighter biosecurity standards and longer annual production cycles, which raises sensitivity to temperature, moisture, ammonia and airborne pathogens. Ventilation fans support lower mortality, better feed conversion and more stable weight gain by maintaining consistent airflow across enclosed buildings.
Heat stress has become a stronger purchasing trigger as hot days lengthen across major farming regions and seasonal peaks grow less predictable. Global poultry meat output remained above 140 million metric tons in 2024, which reinforces continuous investment in housing systems that protect flock performance at scale. Exhaust and tunnel fans benefit most because operators need dependable air exchange under demanding conditions, especially in broiler houses and swine barns where poor ventilation can quickly translate into measurable losses.Expansion of controlled-environment agriculture and greenhouse production
Demand for agricultural ventilation fans also rises with growth in protected cultivation, greenhouse vegetables, high-value flowers and indoor propagation systems. These applications require active air movement to control humidity, limit fungal pressure, improve pollination conditions and support more uniform crop development. Circulation and roof-mounted fans gain traction where growers want to reduce condensation, equalize temperatures and protect crop quality without excessive labor intervention.
Greenhouse economics increasingly favor climate-control upgrades because growers face stricter quality standards, high input costs and pressure to increase output per square meter. China alone maintains more than 2 million hectares of protected horticulture, highlighting the scale of ventilation needs in intensive crop production. Commercial growers are therefore investing in fans that integrate with shutters, evaporative cooling, sensors and automated controllers to improve crop consistency, reduce disease risk and extend seasonal production windows.Shift toward energy-efficient and automated ventilation systems
Power costs remain a central buying criterion for agricultural end users, especially in energy-intensive poultry, dairy and greenhouse sites that run fans for extended periods. This has accelerated demand for high-efficiency blades, variable-speed drives, EC motors and controls that modulate airflow according to temperature, humidity or gas concentration. Buyers increasingly evaluate total operating cost, motor life and maintenance intervals rather than choosing equipment on upfront price alone.
Automation strengthens this shift because farms want ventilation systems that respond quickly to changing barn or greenhouse conditions with limited manual intervention. Integrators and larger commercial operators now prefer platforms that connect fans with climate computers, alarm systems and remote monitoring tools. That preference supports premiumization across product lines and creates replacement demand for older fixed-speed equipment, particularly in regions where labor shortages and utility costs make precision control financially attractive.Key Trends & Opportunities
Energy-efficient fan architecture moves into mainstream farm purchasing
Product development increasingly centers on aerodynamic blade design, corrosion-resistant housings, direct-drive configurations and motors that reduce electricity use under variable load conditions. Farmers and integrators are comparing fan performance based on airflow per watt, noise profile and service life, not only nameplate capacity. This trend is especially visible in poultry and greenhouse projects where systems operate for long daily cycles and electricity costs directly affect margins.
Manufacturers are responding by promoting variable-speed operation and digitally controlled airflow management. In commercial ventilation applications, EC fan systems can reduce electricity consumption by more than 20% compared with conventional AC designs under part-load conditions, which strengthens adoption in cost-sensitive agricultural settings. As a result, premium models are moving from niche installations into broader retrofit programs, particularly where end users can justify higher initial spending through lower operating costs.End users favor application-specific ventilation layouts
Market demand is shifting away from generic fan selection toward application-led system design. Poultry houses require tunnel or cross-ventilation tailored to stocking density and seasonal heat loads, while dairy and swine units emphasize moisture removal, odor control and animal comfort. Greenhouse operators focus more on air mixing, condensation control and integration with shading, cooling pads and climate screens.
This trend supports broader product portfolios and tighter technical selling. Suppliers that offer sizing tools, static pressure guidance and climate-control compatibility gain advantage because customers increasingly expect system-level recommendations. Distribution channels are also changing, with dealers, contractors and integrators acting as solution advisers rather than simple equipment resellers. That shift raises the importance of application expertise, aftersales support and performance validation during installation.Replacement demand from aging ventilation infrastructure
A significant opportunity lies in replacing older agricultural fans that deliver poor energy performance, inconsistent airflow and higher maintenance needs. Many livestock and poultry facilities still operate legacy equipment installed before current expectations for efficiency, corrosion resistance and automated climate control. Replacement cycles are accelerating as producers compare repair costs against the productivity and energy benefits of newer systems.
Wall-mounted exhaust fans and tunnel ventilation units are well positioned for this upgrade wave because they can often fit existing building footprints with limited civil work. Suppliers that simplify retrofit installation, offer standardized dimensions and provide dealer-led service packages can capture demand from budget-conscious farm owners. This opportunity is strongest in mature agricultural markets where producers already understand ventilation economics and want rapid operational payback.Expansion in hot-climate and protein-growth markets
Emerging livestock and greenhouse markets across Asia Pacific, Latin America and Middle East & Africa create long-term growth opportunities for fan manufacturers. Rising protein consumption, larger commercial farm formats and hotter operating conditions increase the need for dependable airflow management in poultry sheds, livestock shelters and storage areas. Demand is not limited to premium systems, as basic durable exhaust and circulation fans also see strong uptake.
Success in these markets depends on channel strategy as much as product design. Companies that build regional dealer networks, local assembly options and service partnerships can address import costs, maintenance concerns and delivery times more effectively. There is also room for mid-tier product lines that balance efficiency with affordability, giving suppliers a path to serve both integrators and independent farms as agricultural modernization broadens.Key Challenges
Challenge: Price sensitivity and uneven capital spending
Agricultural ventilation fans serve end users whose purchasing decisions are closely linked to commodity prices, farm cash flow and seasonal weather conditions. Even when climate control offers clear productivity benefits, farmers often delay upgrades during periods of weak livestock margins or high feed costs. This creates irregular order patterns and intensifies competition around upfront price, especially in standard exhaust fan categories where product differentiation can appear limited.
Manufacturers therefore face pressure to balance efficiency upgrades with affordable system pricing. Premium materials, better motors and smart controls improve value, but they can lengthen payback periods for smaller farms that prioritize immediate budget constraints.Installation complexity and service coverage gaps
Ventilation performance depends heavily on proper sizing, placement, airflow balancing and integration with shutters, cooling pads or control systems. Poor installation can reduce energy efficiency and undermine climate results, which affects customer satisfaction even when fan hardware performs as designed. This issue is more visible in retrofit projects and in developing markets where technical service networks remain thin.
Suppliers must invest in training, channel support and aftersales capability to protect performance outcomes. Without strong local service, replacement parts availability and commissioning expertise, customers may choose lower-cost local alternatives or postpone larger ventilation upgrades.Regional Analysis
North America Agricultural Ventilation Fans Market Market Trends
North America accounted for 32.0% of global Agricultural Ventilation Fans Market revenue in 2024. Regional demand is anchored in large-scale poultry, swine and dairy operations that rely on controlled indoor environments to manage productivity and animal welfare. Wall-mounted exhaust and tunnel fans are widely used in broiler houses and hog barns, while HVLS units see broader uptake in dairy housing and equipment sheds. Buyers in this region place strong emphasis on airflow performance, energy efficiency and durability under heavy-duty operating cycles. Replacement demand is steady because many farms are upgrading older fixed-speed systems with automated ventilation controls and more efficient motors. Established dealer networks and a strong presence of commercial ventilation brands support faster adoption of premium products.
Asia Pacific Agricultural Ventilation Fans Market Market Trends
Asia Pacific accounted for 29.0% of global Agricultural Ventilation Fans Market revenue in 2024. The region benefits from expanding poultry production, rising protein consumption and rapid investment in larger enclosed farming systems across China, India and Southeast Asia. Demand is strongest for exhaust and tunnel fans in poultry and livestock facilities, while circulation fans gain ground in greenhouse cultivation and protected horticulture. Price sensitivity remains higher than in North America and Europe, which supports a broad market for mid-range products and locally assembled units. Competitive intensity is elevated because regional manufacturers compete alongside global brands on cost, lead time and service support. Adoption of automated climate control is increasing, but purchasing decisions still weigh affordability and maintenance simplicity heavily.
Europe Agricultural Ventilation Fans Market Market Trends
Europe accounted for 24.0% of global Agricultural Ventilation Fans Market revenue in 2024. Regional growth is shaped by strict energy-efficiency priorities, animal welfare standards and advanced greenhouse horticulture. Greenhouse-heavy markets support steady demand for circulation, roof-mounted and precision-controlled fan systems that help manage humidity and crop uniformity. Livestock operators also invest in durable low-noise ventilation equipment that aligns with tighter environmental and welfare expectations. Buyers in Europe typically evaluate total lifecycle cost more carefully, which favors premium solutions with efficient motors, corrosion resistance and control integration. Market competition remains strong, but product differentiation through performance certification, automation compatibility and retrofit suitability matters more than price alone.
Latin America Agricultural Ventilation Fans Market Market Trends
Latin America accounted for 8.0% of global Agricultural Ventilation Fans Market revenue in 2024. Poultry and livestock production in warm climates drives demand for robust ventilation systems that can operate reliably under high heat and humidity. Exhaust and tunnel fans dominate installations because they offer practical airflow management for commercial poultry houses and animal shelters. Distribution often runs through agricultural equipment dealers, local contractors and integrator procurement channels, making channel strength important for market access. Purchasing behavior is more price conscious, and project timing can fluctuate with farm profitability and currency conditions. Even so, modernization of commercial poultry and swine facilities continues to create steady replacement and new-build opportunities.
Middle East & Africa Agricultural Ventilation Fans Market Market Trends
Middle East & Africa accounted for 7.0% of global Agricultural Ventilation Fans Market revenue in 2024. Extreme ambient temperatures, expanding food security investments and growth in controlled-environment agriculture support demand across this region. Poultry farms and greenhouses require reliable ventilation for cooling, moisture control and stable production in harsh conditions. Import dependence remains relatively high in many markets, which affects pricing and lead times and increases the importance of local distributors and service partners. Buyers often prioritize rugged construction, corrosion resistance and compatibility with evaporative cooling systems. Adoption is improving as commercial farms expand, though uneven infrastructure and technical support still constrain wider penetration in some countries.
Market Segmentations
- By Type
- Exhaust
- Circulation
- HVLS
- Tunnel
- By Application
- Poultry
- Livestock
- Greenhouse
- Storage
- By Mounting
- Wall
- Ceiling
- Roof
- By End User
- Farms
- Integrators
- Commercial Growers
- By Geography
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Competitive Landscape
The Agricultural Ventilation Fans Market shows moderate to high competitive intensity, with global ventilation specialists and regional agricultural equipment suppliers competing on efficiency, durability and climate-control integration. Innovation remains centered on aerodynamic blade design, EC motor adoption, corrosion-resistant materials and smart controls that improve airflow precision and reduce operating costs. Product strategies increasingly target application-specific needs in poultry, livestock and greenhouse environments rather than one-size-fits-all offerings.
Distribution strength is critical, as dealers, installers, integrators and farm equipment partners influence specification and aftersales service. Partnerships with climate-control providers and agricultural system integrators help companies broaden project access and strengthen bundled sales. Competitive advantage increasingly depends on technical support, retrofit compatibility, delivery reliability and lifecycle value, not only unit price. Brands with strong channel coverage and proven performance in harsh farm environments hold the clearest position.
Key Player Analysis
- Munters
- Big Ass Fans
- Vostermans Ventilation
- Ziehl-Abegg
- Multifan
- Greenheck
- ebm-papst
- Canarm
- PennBarry
- Systemair
Recent Developments
- In January 2025, Munters advanced its connected climate-control offering for livestock applications by strengthening integration between ventilation hardware and digital monitoring capabilities used in modern farm buildings.
- In June 2025, ebm-papst continued expansion of high-efficiency EC fan solutions across ventilation applications, reinforcing market movement toward lower-power air movement systems suitable for agricultural environments.
- In February 2026, Systemair increased focus on regional distribution and localized ventilation supply capabilities, supporting faster delivery and broader access to commercial and agricultural airflow equipment in key markets.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Agricultural Ventilation Fans Market in 2024?
What factors are driving growth in the Agricultural Ventilation Fans Market?
What is a key trend in the Agricultural Ventilation Fans Market?
Which segments lead the Agricultural Ventilation Fans Market?
Who are the top players in the Agricultural Ventilation Fans Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
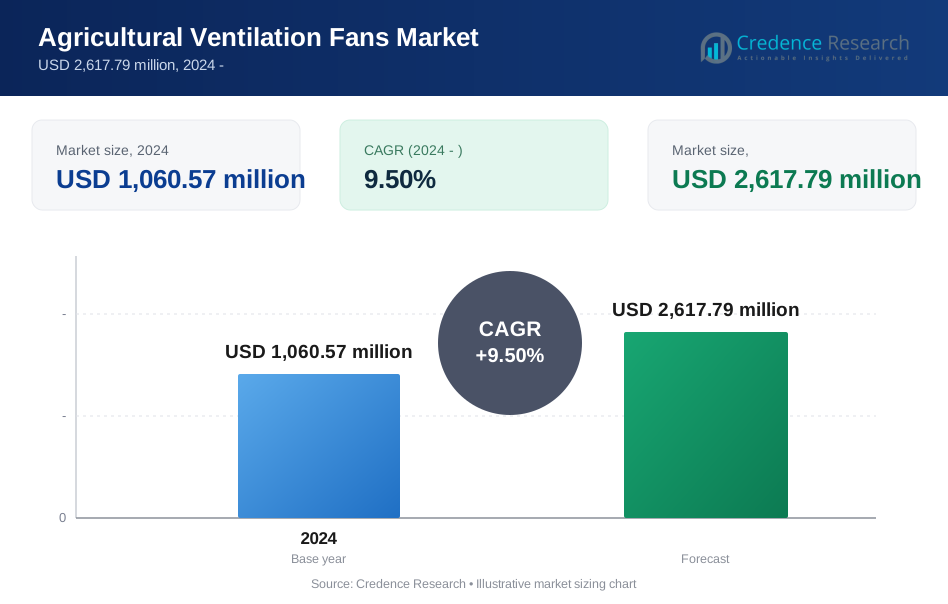
- 2.5.1 2024: USD 1,060.57 million → 2032: USD 2,617.79 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Agricultural Ventilation Fans Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Agricultural Ventilation Fans Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Agricultural Ventilation Fans Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Agricultural Ventilation Fans Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Agricultural Ventilation Fans Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Agricultural Ventilation Fans Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Agricultural Ventilation Fans Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Agricultural Ventilation Fans Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,060.57 million → 2032: USD 2,617.79 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Agricultural Ventilation Fans Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Agricultural Ventilation Fans Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Agricultural Ventilation Fans Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Agricultural Ventilation Fans Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

