
Asia Pacific Soil Remediation Market Overview:
The Asia Pacific soil remediation market was valued at USD 15,649 million in 2024 and is projected to reach USD 27,992.12 million by 2032, expanding at a compound annual growth rate (CAGR) of 7.54% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Asia Pacific Soil Remediation Market Size 2024 | USD 15,649 million |
| Asia Pacific Soil Remediation Market, CAGR | 7.54% |
| Asia Pacific Soil Remediation Market Size 2032 | USD 27,992.12 million |
Asia Pacific Soil Remediation Market Insights
- Market growth is driven by accelerating industrialization, stricter soil contamination regulations, and large-scale brownfield redevelopment, with physicochemical treatment emerging as the dominant technology segment due to faster remediation timelines and high effectiveness in heavily contaminated soils.
- Key trends include increasing adoption of sustainable and in-situ remediation solutions, rising use of organic amendments in agricultural soil restoration, and growing ESG-led remediation investments by industrial developers and multinational corporations.
- The competitive landscape features global and regional players competing on technology depth, regulatory expertise, and project execution capability, with advanced physicochemical and thermal solutions dominating high-value industrial and infrastructure projects.
- Regionally, East Asia leads with ~42% market share, followed by South Asia (~18%), Southeast Asia (~16%), Oceania (~14%), and Rest of Asia Pacific (~10%), reflecting varied regulatory maturity and industrial activity levels.
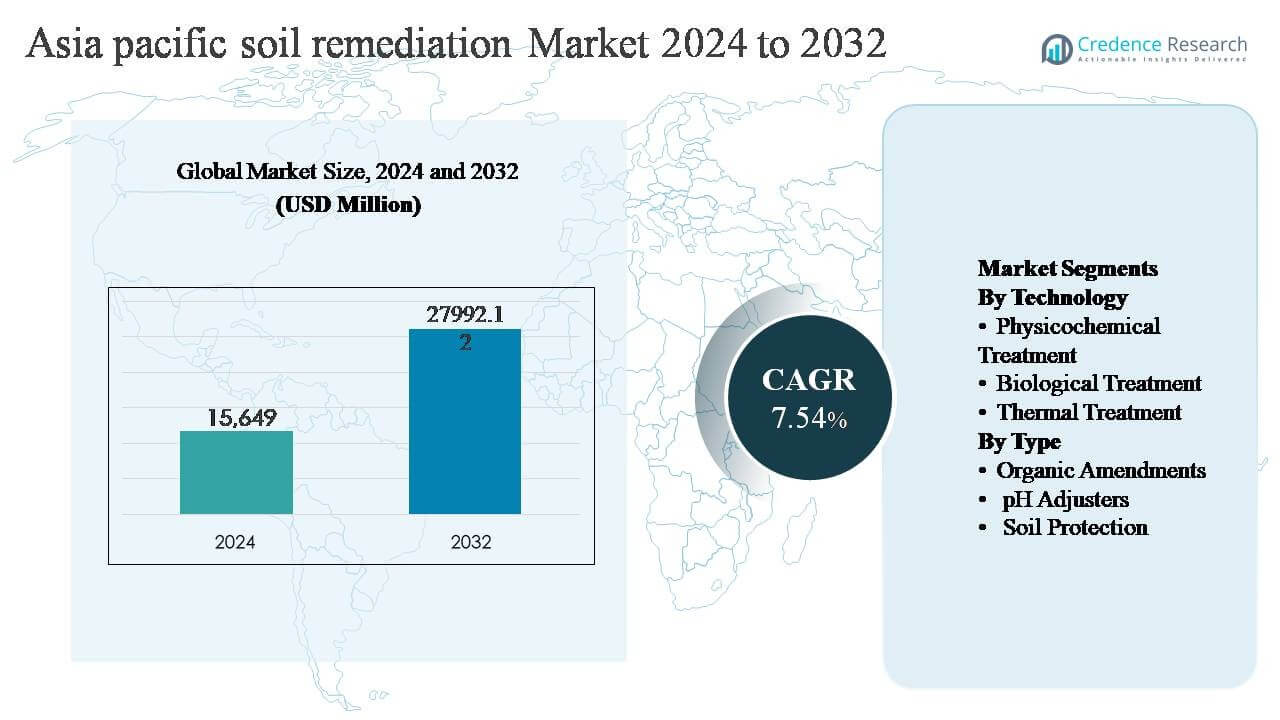
Asia Pacific Soil Remediation Market Segmentation Analysis:
By Technology
In the Asia Pacific soil remediation market, physicochemical treatment represents the dominant technology segment, accounting for the largest market share due to its rapid contaminant removal efficiency and suitability for heavily polluted industrial and mining sites. Techniques such as soil washing, chemical oxidation, and stabilization are widely adopted in China, India, and Southeast Asia, where legacy contamination from manufacturing and metal processing remains significant. Strong government-led brownfield redevelopment programs, faster project timelines, and predictable performance outcomes continue to drive preference for physicochemical methods over biological and thermal alternatives.
- For instance, Veolia implemented a large-scale soil washing and chemical stabilization project at an industrial redevelopment site in eastern China, where its mobile treatment system processed more than 180,000 tonnes of contaminated soil, integrating multi-stage particle separation units and reagent dosing systems capable of injecting over 2,500 kilograms of oxidizing agents per day to address heavy metals and hydrocarbon residues.
By Type
Among type-based solutions, organic amendments hold the leading market share in Asia Pacific soil remediation, driven by their cost-effectiveness, scalability, and compatibility with agricultural land restoration. Materials such as compost, biochar, and manure-based conditioners are extensively used to improve soil structure, immobilize contaminants, and restore fertility in degraded farmlands. Growing emphasis on sustainable agriculture, remediation of pesticide-contaminated soils, and soil carbon enhancement initiatives across India, China, and ASEAN countries supports sustained adoption, while pH adjusters and soil protection solutions see higher usage in niche industrial and infrastructure projects.
- For instance, DOWA Ecosystem Co., Ltd., through its subsidiary Dowa Environmental Management (Suzhou) Co., Ltd., provides specialized soil and groundwater remediation services in China. These services focus on treating industrial land and brownfields contaminated with heavy metals, notably cadmium and arsenic, using technologies such as soil washing and stabilization.
Key Growth Drivers
Rapid Industrialization and Legacy Soil Contamination
Rapid industrial expansion across Asia Pacific has resulted in extensive legacy soil contamination, making remediation a critical environmental priority. Large-scale manufacturing clusters, mining operations, petrochemical complexes, and informal industrial zones in China, India, Indonesia, and Vietnam have left behind soils contaminated with heavy metals, hydrocarbons, and persistent organic pollutants. Governments increasingly mandate remediation before land reuse for residential, commercial, or infrastructure development. Brownfield redevelopment policies, coupled with stricter land-use conversion regulations, directly stimulate demand for soil remediation services. In parallel, urban expansion pressures are pushing authorities to reclaim contaminated land within city boundaries rather than pursue greenfield development, further accelerating remediation activity across industrial and peri-urban zones.
- For instance,Clean Harbors, a leading provider of environmental and industrial services, maintains a significant operational presence in India through its Global Capability Center and local entities, supporting its global remediation services.
Strengthening Environmental Regulations and Compliance Enforcement
Environmental regulation across Asia Pacific has transitioned from voluntary guidelines to enforceable compliance frameworks, significantly driving soil remediation adoption. Countries such as China, Japan, South Korea, and Australia have implemented soil pollution control laws that require site assessment, risk classification, and remediation before land transfer or redevelopment. Penalties for non-compliance and mandatory disclosure of soil contamination have increased corporate accountability. Multinational corporations operating in the region also apply global environmental standards to local operations, driving remediation investments beyond minimum regulatory requirements. As regulatory enforcement capacity improves and environmental audits become routine, remediation demand continues to expand across industrial, agricultural, and infrastructure sectors.
- For instance, In Australia, SUEZ executed remediation works aligned with state Environmental Protection Authority (EPA) guidelines at former industrial land parcels, managing hazardous soil classification, secure transport, and licensed treatment of more than 95,000 tonnes of impacted material using certified containment and treatment facilities, enabling compliance-driven redevelopment for infrastructure and commercial projects.
Infrastructure Expansion and Urban Redevelopment Projects
Massive infrastructure and urban redevelopment initiatives across Asia Pacific are creating sustained demand for soil remediation. High-speed rail corridors, metro systems, industrial parks, logistics hubs, and smart city developments frequently intersect with previously contaminated land. Governments increasingly integrate soil remediation into early-stage project planning to avoid construction delays and long-term environmental risks. Public-private partnerships play a key role in financing remediation activities tied to infrastructure projects. The scale and continuity of these developments ensure long-term demand for remediation technologies, particularly physicochemical and in-situ solutions that align with tight construction timelines and large land parcels.
Key Trends & Opportunities
Shift Toward Sustainable and In-Situ Remediation Technologies
Asia Pacific is witnessing a clear shift toward sustainable, in-situ soil remediation solutions that minimize excavation, waste generation, and project costs. Biological treatment, phytoremediation, and the use of organic amendments are gaining traction, particularly in agricultural and peri-urban settings. Governments and landowners increasingly favor solutions that restore soil health while reducing carbon footprint and secondary pollution. This trend creates opportunities for technology providers offering bio-based treatments, soil conditioners, and microbial solutions adapted to local soil conditions. Long-term land productivity and environmental benefits are becoming as important as short-term contaminant removal.
- For instance, REGENESIS deployed in-situ bioremediation programs across multiple Asia Pacific sites using its proprietary electron-donor amendment technologies, injecting more than 4.5 million liters of liquid substrates into contaminated vadose and saturated zones through permanent injection networks to stimulate indigenous microbial degradation of chlorinated solvents and petroleum hydrocarbons.
Growth in Agricultural Soil Restoration Programs
Degradation of agricultural soils due to excessive fertilizer use, pesticide accumulation, and industrial runoff is creating new remediation opportunities. Several Asia Pacific governments are investing in soil health improvement programs to safeguard food security and rural livelihoods. Remediation solutions that improve nutrient balance, reduce heavy metal uptake, and enhance soil structure are increasingly deployed in farmlands. This trend expands the market beyond industrial remediation into large-scale agricultural applications, supporting steady demand for organic amendments, pH adjusters, and soil protection technologies tailored for crop productivity.
- For instance, TerraTherm, Inc. (a subsidiary of Cascade Environmental) has applied its in-situ thermal conduction heating (TCH) technology to restore land where soils were impacted by persistent organic pollutants (POPs), including sites adjacent to agricultural and industrial areas.
Rising Private Sector Participation and ESG Integration
Private sector involvement in soil remediation is increasing as environmental, social, and governance (ESG) criteria gain prominence. Developers, industrial operators, and investors increasingly incorporate soil remediation into sustainability strategies to reduce long-term environmental liabilities and enhance asset value. This shift opens opportunities for specialized remediation service providers, technology licensors, and environmental consultants. ESG-driven remediation investments are particularly visible in industrial parks, logistics facilities, and export-oriented manufacturing zones across Asia Pacific.
Key Challenges
High Remediation Costs and Project Financing Constraints
High remediation costs remain a significant challenge in the Asia Pacific soil remediation market, particularly for complex contamination sites requiring multi-technology approaches. Advanced physicochemical and thermal treatments involve substantial capital expenditure, skilled labor, and specialized equipment. In developing economies, limited access to dedicated remediation funding and unclear cost-sharing mechanisms between landowners, polluters, and authorities delay project execution. Small and medium landholders often lack the financial capacity to undertake remediation seeings beyond basic compliance, slowing market penetration in non-industrial segments.
Technical Complexity and Site-Specific Variability
Soil remediation projects in Asia Pacific face high technical complexity due to diverse soil types, contamination profiles, and climatic conditions. Solutions effective in one location may underperform in another, increasing project risk and uncertainty. Limited availability of high-resolution soil data and inconsistent site assessment standards further complicate technology selection. In addition, a shortage of skilled remediation professionals in emerging markets can affect project quality and timelines. These factors collectively challenge scalability and standardization across the region, constraining faster market expansion.
Regional Analysis
East Asia (China, Japan, South Korea)
East Asia dominates the Asia Pacific soil remediation market, accounting for approximately 42% market share, driven primarily by China’s large-scale industrial legacy pollution and strict enforcement of soil contamination control laws. China leads regional demand through extensive brownfield redevelopment, mining site rehabilitation, and urban renewal projects. Japan and South Korea contribute steadily through remediation linked to infrastructure upgrades, industrial land reuse, and environmental compliance in manufacturing zones. Strong regulatory frameworks, advanced remediation technologies, and higher remediation spending per project reinforce East Asia’s leadership position within the regional market.
South Asia (India, Bangladesh, Sri Lanka, Others)
South Asia holds around 18% market share in the Asia Pacific soil remediation market, supported by rising industrialization, agricultural soil degradation, and expanding infrastructure development. India is the dominant contributor, with remediation demand driven by contaminated industrial land, waste disposal sites, and soil quality improvement initiatives in agriculture. Government programs targeting river basin pollution, industrial corridor development, and urban redevelopment increasingly incorporate soil remediation. While cost sensitivity remains high, growing regulatory awareness and public infrastructure investments continue to strengthen South Asia’s long-term market potential.
Southeast Asia (Indonesia, Vietnam, Thailand, Malaysia, Philippines)
Southeast Asia accounts for approximately 16% market share, driven by rapid industrial growth, port and logistics expansion, and remediation of contaminated manufacturing zones. Countries such as Vietnam, Indonesia, and Thailand are witnessing increased remediation activity linked to electronics, textiles, chemicals, and mining operations. Foreign direct investment and export-oriented industrial parks require compliance with environmental standards, boosting demand for remediation services. Agricultural soil restoration initiatives also support growth, particularly in regions affected by pesticide overuse and industrial runoff, positioning Southeast Asia as a fast-emerging remediation market.
Oceania (Australia, New Zealand)
Oceania represents about 14% market share in the Asia Pacific soil remediation market, led overwhelmingly by Australia. Strict environmental regulations, well-defined contaminated land management frameworks, and strong enforcement drive consistent remediation demand. Mining site rehabilitation, petroleum-contaminated land cleanup, and urban brownfield redevelopment are key application areas. Australia’s mature remediation industry benefits from advanced technologies and established service providers. New Zealand contributes through remediation linked to agricultural land protection and infrastructure projects, although on a smaller scale compared to Australia.
Rest of Asia Pacific (Central Asia and Others)
The Rest of Asia Pacific accounts for around 10% market share, with demand emerging from resource extraction, oil and gas operations, and infrastructure development. Countries in Central Asia and smaller Pacific economies are gradually adopting soil remediation as environmental governance improves. While remediation activity remains project-based and limited in scale, international development funding and foreign investment-driven infrastructure projects are increasing adoption. Over time, regulatory development and industrial expansion are expected to strengthen remediation demand, supporting incremental growth across these emerging markets.
Asia Pacific Soil Remediation Market Segmentations:
By Technology
- Physicochemical Treatment
- Biological Treatment
- Thermal Treatment
By Type
- Organic Amendments
- pH Adjusters
- Soil Protection
By Geography
- East Asia
- South Asia
- Southeast Asia
- Oceania
- Rest of Asia
Competitive Landscape
The Asia Pacific soil remediation market features a moderately fragmented competitive landscape, with a mix of global environmental engineering firms, regional remediation specialists, and country-specific service providers competing across industrial, infrastructure, and agricultural projects. Multinational players leverage advanced physicochemical and thermal remediation technologies, strong project management capabilities, and experience in large-scale brownfield redevelopment to secure high-value contracts, particularly in China, Australia, and Japan. Regional companies remain competitive by offering cost-effective biological and in-situ solutions tailored to local soil conditions and regulatory requirements. Strategic partnerships with construction firms, mining operators, and government agencies are common, enabling integrated remediation and redevelopment execution. Competition increasingly centers on technical reliability, regulatory compliance expertise, and the ability to deliver remediation within tight infrastructure timelines, while sustainability credentials and ESG alignment are becoming key differentiators in project selection.
Key Player Analysis
- Veolia Environment S.A.
- Jacobs Solutions Inc.
- SUEZ
- Clean Harbors, Inc.
- RSK Group (Enviros / ENHESA)
- REGENESIS
- TerraTherm, Inc. (Cascade Environmental)
- Polyeco Group
- Dowa Ecosystem
- Greensum Ecology
Recent Developments
- In October 2025, Veolia secured the first National Environment Agency (NEA) license in Singapore for advanced PFAS treatment of aqueous film-forming foams (AFFF) at its hazardous waste facility, demonstrating thermal treatment capabilities with destruction and removal efficiencies of up to 99.9999% for targeted PFAS compounds. This milestone supports compliance with forthcoming regulations effective from January 2026 and strengthens Veolia’s deployment of high-temperature soil and waste remediation technologies in the Asia Pacific region.
- In June 2025, Veolia’s BeyondPFAS program reported treating 75 million litres of PFAS-contaminated water and managing 200,000 tonnes of PFAS-impacted soil across multiple sites in Australia, reinforcing its end-to-end soil and groundwater remediation services for persistent contaminants.
Report Coverage
The research report offers an in-depth analysis based on Technology, Type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Asia Pacific soil remediation market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Asia Pacific soil remediation market projected to grow between 2024 and 2032?
Which Asia Pacific soil remediation segment held the largest share in 2024?
What are the primary factors fueling the growth of the Asia Pacific soil remediation market?
Who are the leading companies in the Asia Pacific soil remediation market?
Which region commanded the largest share of the Asia Pacific soil remediation market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 15,649 million → 2032: USD 27,992.12 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Asia Pacific Soil Remediation Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Asia Pacific Soil Remediation Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Asia Pacific Soil Remediation Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Asia Pacific Soil Remediation Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Asia Pacific Soil Remediation Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Asia Pacific Soil Remediation Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Asia Pacific Soil Remediation Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Asia Pacific Soil Remediation Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 15,649 million → 2032: USD 27,992.12 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Asia Pacific Soil Remediation Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Asia Pacific Soil Remediation Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Country-Level Shares, 2024
- 13.2 Country Market Size Comparison, 2024
- 13.3 Country Market Forecasts, 2024-2032
- 13.4 Subregional Industrial and Demand Clusters
- 13.5 Intra-Regional Pricing and Cost Differences
- 13.6 Cross-Border Trade and Supply Networks
- 13.7 Regional Supply and Demand Balances
- 13.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 14 Asia Pacific Soil Remediation Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Asia Pacific Soil Remediation Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

