
Market Overview
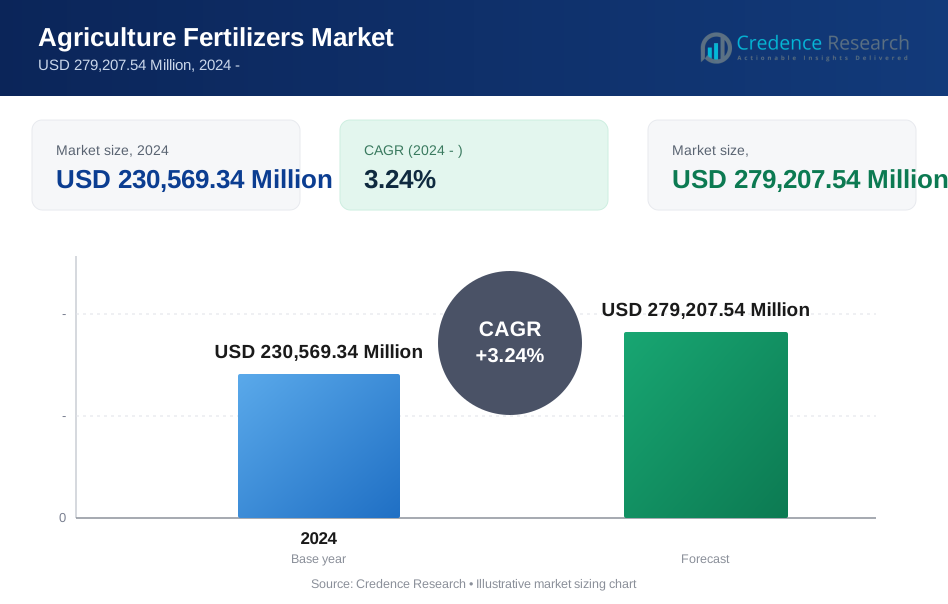
The Agriculture Fertilizers Market is projected to grow from USD 230,569.34 Million in 2024 to an estimated USD 279,207.54 Million by 2032, with a CAGR of 3.24% from 2024 to 2032. Demand rises as growers seek higher crop yields, balanced soil nutrition and more efficient nutrient delivery. Asia Pacific leads global revenue because China, India and Southeast Asia sustain large fertilizer consumption across intensive farming systems.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period: | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Agriculture Fertilizers Market Market Size 2024 | USD 230,569.34 Million |
| Agriculture Fertilizers Market CAGR | 3.24% |
| Agriculture Fertilizers Market Market Size 2032 | USD 279,207.54 Million |
Market Insights
- Asia Pacific led global demand in 2024 with a 38.4% revenue share, supported by intensive fertilizer use across China, India and Southeast Asia.
- Nitrogen remained dominant within type with an estimated 46.8% share because cereal, rice and oilseed cultivation requires repeated nitrogen replenishment.
- Solid fertilizers held an estimated 77.4% share by form because growers favor granules and dry blends for bulk handling, storage and broad-acre application.
- Nutrien, Yara, Mosaic, CF Industries and OCP Group remained five of the most influential participants across production, distribution and product innovation.
- Precision nutrient management, specialty grades and fertigation-compatible formulations represent the market’s most visible current trend.
Market Segmentation Analysis
By Type (Nitrogen, Phosphate, Potash, Micronutrients)
Nitrogen held the largest share of the Agriculture Fertilizers Market in 2024 at an estimated 46.8%. Its dominance reflects heavy use in cereals, rice, wheat, corn and other row crops where rapid vegetative growth and yield formation depend on regular nitrogen application. Strong demand for urea, ammonium nitrate and related nitrogen products also stems from intensive multi-cropping systems in Asia Pacific and Latin America.
By Form (Solid, Liquid)
Solid fertilizers accounted for the largest market share in 2024 at an estimated 77.4%. Granular and powdered products dominate because they move efficiently through wholesale and retail channels, store well in bulk and suit conventional broadcasting and band placement across broad-acre farms. Their lower handling complexity and compatibility with established farm equipment continue to support adoption in staple crop production.
By Application (Soil, Foliar, Fertigation)
Soil application led the market in 2024 with an estimated 68.2% share. This method remains the standard across large-scale field crops because it supports pre-planting, basal and top-dressing programs using dry or liquid nutrients. Wide agronomic familiarity, ease of integration into standard farm operations and strong suitability for nitrogen, phosphate and potash products sustain its leading position.
By Crop Type (Row Crops, Horticulture, Plantations)
Row crops held the largest share in 2024 at an estimated 61.7%. Corn, wheat, rice, soybean and other extensive field crops consume high fertilizer volumes because of large cultivated acreage and repeated nutrient removal from soils. The segment’s scale, combined with farmers’ focus on yield protection and nutrient replacement, keeps row crops at the center of global fertilizer demand.
Key Growth Drivers
Rising pressure to improve crop yields
Global agriculture continues to face strong pressure to produce more grain, oilseeds and feed from limited arable land, which directly supports fertilizer consumption. Growers increasingly depend on nitrogen, phosphate and potash to sustain plant vigor, improve nutrient uptake and prevent yield loss across high-intensity cropping cycles. This pattern is especially visible in rice, wheat and corn systems where nutrient removal is high and soil recovery periods are short. Global cereal production has remained above 2.8 billion tonnes in recent seasons, showing how strongly food systems rely on high-output farming. That production scale requires continuous nutrient replacement, particularly in regions with double-cropping and irrigated agriculture. Fertilizers therefore remain central to farm productivity strategies, not only as yield enhancers but also as tools for maintaining crop consistency under weather variability and tight harvest economics.
Government support and food security programs sustain demand
Public policy remains an important demand pillar for agricultural fertilizers because many governments link nutrient access with domestic food security, farm income stability and rural output. Subsidy frameworks, minimum support prices, input credit and distribution programs help growers maintain fertilizer application even when crop prices fluctuate. These mechanisms matter most in populous agricultural economies where cereal self-sufficiency and inflation control remain policy priorities. India alone allocated more than INR 1.6 trillion for fertilizer subsidies in the 2024-25 fiscal framework, underlining the scale of state support that can influence global nutrient demand. Similar policy backing in parts of Asia, the Middle East and Africa strengthens procurement visibility for suppliers. As governments push for reliable harvests and input availability, fertilizer makers benefit from steadier offtake and more predictable seasonal demand patterns.
Soil nutrient depletion drives balanced nutrition programs
Continuous cultivation, shortened rotations and higher-yield seed varieties have accelerated nutrient mining in many agricultural soils, which supports recurring fertilizer purchases. Farmers are moving beyond single-nutrient applications toward balanced programs that combine nitrogen, phosphate, potash and micronutrients to correct soil deficiencies and improve nutrient-use efficiency. This shift expands demand across both commodity fertilizers and higher-value specialty products. Micronutrient demand is gaining attention in horticulture, plantations and intensive row crops where zinc, boron and other trace elements influence quality, root development and stress tolerance. At the same time, agronomic advisory services and soil testing programs are improving farmer awareness of nutrient imbalances. As growers focus more on crop quality, nutrient recovery and long-term soil performance, fertilizer demand becomes broader, more tailored and more resilient across seasons.
Key Trends & Opportunities
Precision nutrition gains scale
Precision agriculture is reshaping fertilizer purchasing by linking product choice with field-level agronomy, variable-rate technology and in-season crop monitoring. Growers increasingly want nutrient plans that reflect soil maps, crop stage and weather conditions rather than uniform application across every acre. This trend supports higher demand for tailored blends, stabilized nitrogen products and liquid formats that fit modern application equipment and digital farm workflows. Nutrien’s retail network serves more than 500,000 grower accounts, illustrating the scale at which data-led agronomy and fertilizer bundling can now influence buying behavior. Large distributors use this reach to connect crop inputs, digital recommendations and local advisory services. As farms seek better nutrient-use efficiency and stronger return on input spend, precision-led fertilizer programs are becoming a practical operating standard rather than a niche approach.
Specialty and lower-emission products advance
The market is also moving toward differentiated products that solve efficiency, quality and sustainability concerns. Water-soluble grades, foliar nutrients, controlled-release formulations and micronutrient-enriched products are gaining share in high-value crops and water-sensitive production systems. At the same time, buyers across Europe and parts of North America are showing stronger interest in fertilizers with lower carbon intensity, especially where food processors and retailers track upstream emissions. This shift does not replace conventional fertilizers, but it changes portfolio strategy for major suppliers. Companies are investing in enhanced-efficiency nitrogen, cleaner ammonia pathways and specialty crop nutrition lines that support premium pricing. Product development increasingly focuses on nutrient recovery, leaching reduction and ease of application. Those priorities are helping manufacturers defend margins while responding to stricter sustainability expectations from growers, regulators and downstream food companies.
Emerging markets create expansion runway
One of the clearest opportunities lies in regions where fertilizer use remains below agronomic potential. Parts of sub-Saharan Africa, Southeast Asia and selected Latin American markets still show under-application relative to crop nutrient removal, which leaves room for volume growth and yield improvement. Suppliers that combine affordable products with farmer education, local packaging and dealer expansion can capture incremental demand as commercial farming systems mature. Horticulture and plantation crops strengthen this opportunity because they require more specialized nutrient regimes and often generate higher returns per hectare than staple grains. Fertigation, foliar feeding and micronutrient programs can therefore scale quickly where irrigation and export-oriented farming expand. Companies with strong agronomy support and region-specific formulations are well placed to convert these underserved markets into durable long-term revenue streams.
Supply chain localization opens strategic upside
Another important opportunity comes from local production, blending and logistics investments that reduce import dependence and improve seasonal supply reliability. Fertilizer markets in Brazil, Africa and parts of Asia remain exposed to shipping costs, port congestion and feedstock disruption. Producers that build regional storage, inland terminals, blending facilities and crop-specific formulation capabilities can improve service levels while protecting customers from procurement delays during critical planting windows. Localization also supports partnerships with governments, cooperatives and large farm distributors that want more secure nutrient access. Integrated phosphate, potash and nitrogen projects can strengthen product availability while enabling more targeted formulations for local soils and crops. As supply resilience becomes a larger purchasing criterion, companies that control sourcing, distribution and advisory support will gain a clearer competitive edge in both mature and emerging agricultural economies.
Key Challenges
Feedstock and price volatility pressure planning
Fertilizer demand remains vulnerable to volatility in natural gas, sulfur, ammonia, phosphate rock and potash pricing. These cost swings affect producer margins, distributor inventory decisions and farmer purchase timing, especially in import-dependent markets. When nutrient prices rise too quickly, growers often delay applications, reduce dosage or shift toward lower-cost blends, which can weaken volume visibility across seasons. Volatility also complicates procurement for retailers and cooperatives that must position stock ahead of planting cycles. Sharp changes in freight and energy costs can distort regional pricing spreads and reduce market transparency. This environment forces manufacturers to manage working capital carefully while maintaining supply availability during peak demand periods.
Regulation, affordability and uneven farmer adoption limit uptake
Environmental regulation is tightening in several major markets, particularly around nitrogen runoff, groundwater quality and emissions intensity. These rules can increase compliance costs, limit application windows and push growers toward more expensive enhanced-efficiency products. While such changes support innovation, they also create transition risk for suppliers and for farmers who operate on thin margins. Affordability remains a separate challenge in lower-income agricultural regions where smallholders often lack credit, irrigation access or agronomic advice. Even when the agronomic case for balanced fertilization is strong, adoption can remain inconsistent because of cash flow constraints and fragmented distribution. This gap slows penetration of premium products and keeps usage below optimal levels in many developing markets.
Regional Analysis
North America Agriculture Fertilizers Market Market Trends
North America accounted for 22.6% of global Agriculture Fertilizers Market revenue in 2024. Demand remains anchored in corn, soybean and wheat systems that require large-volume nitrogen and phosphate applications, particularly across the U.S. Midwest and Canada’s Prairie provinces. Growers use precision placement, variable-rate programs and retailer agronomy services more widely than most regions, which supports premium blends and enhanced-efficiency products. Distribution is highly organized through cooperatives, ag retailers and direct farm accounts, while Canada’s potash production and U.S. nitrogen capacity strengthen regional supply security. Purchasing decisions increasingly weigh yield response, nutrient-use efficiency and application flexibility rather than price alone.
Asia Pacific Agriculture Fertilizers Market Market Trends
Asia Pacific accounted for 38.4% of global Agriculture Fertilizers Market revenue in 2024. The region leads because China, India and Southeast Asian markets support very large consumption across rice, wheat, fruits, vegetables and plantation crops. High cropping intensity, smaller average farm sizes and strong government involvement in input distribution sustain demand for urea, phosphates and specialty nutrients. Retail channels remain fragmented in many countries, yet subsidy systems and public procurement continue to influence farmer access and seasonal buying patterns. Fertigation and water-soluble products are also gaining ground in horticulture as irrigation coverage and protected cultivation expand.
Europe Agriculture Fertilizers Market Market Trends
Europe accounted for 19.3% of global Agriculture Fertilizers Market revenue in 2024. Market performance reflects a shift toward efficiency, compliance and product differentiation rather than pure volume growth. Nitrogen remains essential for cereals and oilseeds, but stricter nutrient management rules, environmental targets and farm sustainability programs encourage measured application and stronger use of specialty grades. Energy cost volatility has also influenced regional nitrogen production economics, raising the importance of import balancing and supply diversification. Buyers increasingly favor products that support traceability, lower losses and compatibility with precision equipment and farm nutrient plans.
Latin America Agriculture Fertilizers Market Market Trends
Latin America accounted for 11.2% of global Agriculture Fertilizers Market revenue in 2024. Brazil dominates regional demand through soybean, corn, sugarcane and coffee production, while Argentina and other markets add strong row-crop and specialty-crop consumption. Import dependence remains a defining feature for potash and several phosphate products, making pricing and availability sensitive to freight conditions and currency movements. Large commercial farms often buy in bulk before planting and place strong emphasis on yield response, logistics reliability and customized blends for tropical soils. Growth in planted acreage and export-oriented agriculture continues to support fertilizer demand despite periodic farm income swings.
Middle East & Africa Agriculture Fertilizers Market Market Trends
Middle East & Africa accounted for 8.5% of global Agriculture Fertilizers Market revenue in 2024. The region combines major export-oriented production hubs with underpenetrated domestic farm markets, creating a distinct mix of supply strength and demand potential. Morocco supports global phosphate leadership, while Gulf producers contribute meaningfully to nitrogen supply, yet many African countries still show low application rates and uneven distribution access. Water scarcity is pushing more interest in fertigation, soluble fertilizers and crop-specific nutrient programs in irrigated agriculture. Food security policies, local blending initiatives and dealer network expansion are gradually improving market reach across East and West Africa.
Market Segmentations
- By Type
- Nitrogen
- Phosphate
- Potash
- Micronutrients
- By Form
- Solid
- Liquid
- By Application
- Soil
- Foliar
- Fertigation
- By Crop Type
- Row Crops
- Horticulture
- Plantations
- By Geography
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East & Africa
Competitive Landscape
The Agriculture Fertilizers Market remains highly competitive, with global leaders and regional producers competing on scale, product breadth, agronomy support and supply reliability. Major companies are prioritizing innovation in enhanced-efficiency fertilizers, specialty nutrition, water-soluble grades and lower-emission product pathways. Product strategy increasingly centers on complete crop nutrition portfolios rather than stand-alone commodity offerings, allowing suppliers to cross-sell nitrogen, phosphate, potash and micronutrient solutions.
Distribution strength remains a critical advantage, especially where companies combine production assets with retail networks, local warehouses and agronomic advisory teams. Partnerships with cooperatives, distributors, irrigation suppliers and digital agriculture platforms are expanding market reach and improving farmer retention. Competitive intensity is strongest in high-volume row crop markets, where price discipline matters, but differentiation is growing in horticulture, fertigation and sustainability-linked offerings. Companies that pair scale with technical service and localized supply are better positioned to defend margins and market share.
Key Player Analysis
- Nutrien
- Yara
- Mosaic
- CF Industries
- ICL Group
- OCP Group
- EuroChem
- K+S
- OCI
- Coromandel
- Haifa Group
Recent Developments
- In January 2025, Yara advanced its low-carbon fertilizer strategy in Europe through expanded renewable ammonia and decarbonized supply initiatives aimed at food and industrial customers.
- In July 2025, Nutrien strengthened its retail and digital agronomy integration in North America to improve precision nutrient recommendations and bundled fertilizer sales.
- In February 2026, OCP Group progressed phosphate and specialty fertilizer capacity expansion in Morocco to support export demand across Africa, Europe and Latin America.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Agriculture Fertilizers Market in 2024?
What factors are driving growth in the Agriculture Fertilizers Market?
What are the key trends in the Agriculture Fertilizers Market?
Which segment leads the Agriculture Fertilizers Market by type?
Who are the top players in the Agriculture Fertilizers Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 230,569.34 Million → 2032: USD 279,207.54 Million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Agriculture Fertilizers Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Agriculture Fertilizers Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Agriculture Fertilizers Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Agriculture Fertilizers Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Agriculture Fertilizers Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Agriculture Fertilizers Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Agriculture Fertilizers Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Agriculture Fertilizers Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 230,569.34 Million → 2032: USD 279,207.54 Million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Agriculture Fertilizers Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Agriculture Fertilizers Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Agriculture Fertilizers Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Agriculture Fertilizers Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

