
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
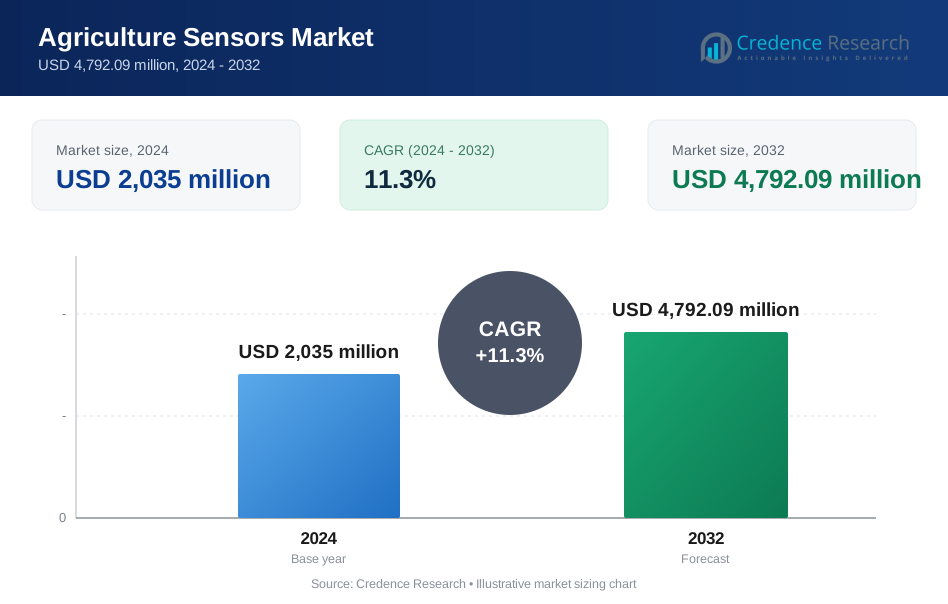
| Agriculture Sensors Market Size 2024 | USD 2,035 million |
| Agriculture Sensors Market, CAGR | 11.3% |
| Agriculture Sensors Market Size 2032 | USD 4,792.09 million |
Market Overview
The global agriculture sensors market is projected to grow from USD 2,035 million in 2024 to USD 4,792.09 million by 2032, at a compound annual growth rate (CAGR) of 11.3%.
The agriculture sensors market is driven by the increasing demand for precision farming techniques, which enhance crop yields and optimize resource utilization. Technological advancements in sensor technologies, such as IoT and remote sensing, further propel market growth by enabling real-time data collection and analysis. Additionally, the rising focus on sustainable agriculture practices encourages farmers to adopt smart farming solutions. The growing awareness of the environmental impact of traditional farming methods and the need for efficient water management systems also contribute to the demand for advanced agriculture sensors, driving innovation and investment in this sector.
The agriculture sensors market exhibits significant geographical variation, with North America and the Asia-Pacific region leading in adoption. North America, driven by advanced technology and precision agriculture practices, hosts key players like Trimble Inc. and Bosch. Meanwhile, the Asia-Pacific region, particularly countries such as China and India, is witnessing rapid growth due to increasing food security demands and government initiatives promoting smart farming. Prominent companies like CropX Inc. and Sentera, LLC are also making strides in this market. As global awareness of sustainable farming rises, these key players are pivotal in shaping the future of agriculture sensor technologies.
Market Drivers
Increasing Demand for Food
The global population is steadily increasing, leading to a higher demand for food. For instance, the United Nations projects that the world population will reach 9.7 billion by 2050, significantly increasing the demand for food, especially in urban areas. As urbanization continues, with more people moving to cities, there’s a growing need for efficient and sustainable food production. This trend compels agricultural practices to adapt, ensuring that the food supply meets the needs of a burgeoning population while maintaining sustainability.
Climate Change and Environmental Concerns
Climate change is causing more frequent and severe extreme weather events, such as droughts, floods, and heatwaves, which adversely affect crop yields. For instance, the 2020–present Horn of Africa drought, exacerbated by climate change, has severely impacted agricultural productivity. Alongside this, there is rising awareness of the environmental impact of agriculture, driving the adoption of sustainable practices. Farmers are increasingly motivated to implement innovative solutions that not only enhance productivity but also minimize ecological footprints.
Rising Labor Costs
The agricultural workforce is aging in many countries, resulting in significant labor shortages. For instance, in the United States, the average age of farmers is increasing, leading to a shortage of younger workers. Additionally, as living standards improve, labor costs are rising, further complicating agricultural operations. This situation necessitates the adoption of technologies that can compensate for labor shortages and rising wages, allowing farmers to maintain productivity and profitability.
Precision Agriculture and Technological Advancements
Precision agriculture enables farmers to utilize resources such as water, fertilizers, and pesticides more efficiently, significantly enhancing operational effectiveness. For instance, IoT-based sensors and drones are being used to monitor crop health and optimize resource use. Sensors provide real-time data on soil conditions, plant health, and weather patterns, facilitating yield optimization. Advancements in sensor miniaturization and integration with the Internet of Things (IoT) have made these technologies more affordable and accessible, empowering a broader range of farmers to adopt smart agricultural practices. Government initiatives and subsidies further encourage the adoption of these advanced technologies, fostering innovation in the agriculture sensor market.
Market Trends
Enhanced Data Management and IoT Integration
The integration of Internet of Things (IoT) technology with agricultural sensors is revolutionizing farming practices by enabling real-time data collection and analysis. For instance, IoT devices in agriculture gather real-time data on various parameters such as soil health, crop growth, and weather conditions. This advancement allows farmers to monitor their crops remotely, providing timely insights that facilitate immediate responses to potential issues such as pest infestations or irrigation needs. The trend towards IoT integration enhances operational efficiency, empowering farmers to make informed decisions based on accurate, real-time data. Additionally, advancements in sensor technology, including miniaturization and improved accuracy, are making these tools more accessible and effective for a broader range of farmers. Smaller, more affordable sensors can now be deployed widely, delivering precise data that enhances reliability in monitoring environmental conditions critical for crop health. As farmers increasingly embrace these technological advancements, they benefit from not only greater efficiency but also the ability to optimize their operations for better yields.
Focus on Sustainability and Specialized Technologies
A notable trend in agriculture is the growing emphasis on sustainability and the adoption of precision agriculture practices, which aim to reduce waste and minimize environmental impacts. Sensors play a vital role in this shift, enabling farmers to monitor soil health, water usage, and carbon emissions more effectively. This data-driven approach supports sustainable farming practices by helping farmers make informed choices about resource allocation and environmental stewardship. Furthermore, the use of specialized sensors, such as drone-based systems for large-scale monitoring and soil sensors for measuring moisture, temperature, and nutrient levels, is gaining traction. These specialized tools enhance the ability to detect crop health issues and manage inputs efficiently, driving better agricultural outcomes. In developing countries, government initiatives to invest in agricultural technology are crucial for improving food security and reducing poverty. The availability of affordable sensor solutions is fostering increased adoption in these regions, enabling more farmers to benefit from modern agricultural practices. As technologies like robotics and blockchain are integrated into farming operations, the transparency and traceability of agricultural products are enhanced, paving the way for a more sustainable and efficient agricultural ecosystem.
Market Challenges Analysis
Integration Challenges and Data Management
The integration of Internet of Things (IoT) platforms with agricultural sensors presents both opportunities and challenges. For instance, a study on Chinese agro-entrepreneurs highlighted that while IoT technology can significantly improve productivity and efficiency, the complexity of managing vast amounts of data can be overwhelming. While real-time data collection and analysis enable farmers to monitor their crops from anywhere, the complexity of managing vast amounts of data can be overwhelming. Farmers must invest in robust data analytics and artificial intelligence (AI) systems to derive actionable insights from the data gathered. AI-powered predictive analytics can significantly enhance decision-making by forecasting crop yields, identifying potential disease outbreaks, and optimizing resource use. However, these advanced technologies require substantial investment in infrastructure and training, which can be a barrier for some farmers.
Adoption of Specialized and Sustainable Technologies
The demand for specialized sensors, such as drone-based and soil sensors, is growing as farmers seek more precise monitoring solutions for large-scale operations. Drones equipped with sensors offer a modern approach to detecting crop health issues across expansive fields, while soil sensors measure critical parameters like moisture, temperature, and nutrient levels. As farmers increasingly focus on sustainability, the integration of precision agriculture practices becomes vital to reducing waste and minimizing environmental impact. Sensors play a crucial role in monitoring soil health, water usage, and carbon emissions, aiding farmers in making environmentally responsible decisions. Despite these advancements, the challenge remains for farmers, particularly in developing countries, to access affordable solutions and effectively adopt these technologies. Government initiatives aimed at improving food security and reducing poverty are essential in driving the integration of agricultural technology, yet widespread adoption requires ongoing support, education, and accessible financing options for farmers.
Market Segmentation Analysis:
By Product:
The agriculture sensors market can be segmented by product into three key categories: physical sensors, mechanical sensors, and chemical sensors. Physical sensors are widely used in various agricultural applications to collect data related to environmental conditions, such as temperature, humidity, and soil moisture. These sensors enable farmers to make informed decisions about crop management and resource allocation. Mechanical sensors, on the other hand, are primarily utilized for monitoring equipment and machinery performance, ensuring optimal functioning and reducing downtime. This segment plays a crucial role in enhancing operational efficiency. Lastly, chemical sensors are gaining traction for their ability to detect soil and water quality, allowing farmers to assess nutrient levels and pollutants. This data is vital for maintaining soil health and ensuring sustainable farming practices. As demand for precision agriculture grows, these product segments are expected to expand, driving innovation and investment in sensor technologies tailored to specific agricultural needs.
By Application:
The agriculture sensors market is also segmented by application, encompassing yield monitoring and mapping, soil monitoring, disease control and detection, and irrigation and water management. Yield monitoring and mapping applications utilize sensors to provide real-time data on crop performance, helping farmers assess productivity and make informed decisions about harvesting. Soil monitoring is critical for understanding soil health, with sensors measuring moisture, temperature, and nutrient levels, allowing for better management of soil resources. In the realm of disease control and detection, sensors are instrumental in identifying early signs of plant stress and disease, enabling prompt intervention and reducing crop losses. Furthermore, irrigation and water management applications leverage sensors to optimize water usage, ensuring efficient irrigation practices that conserve resources and promote sustainable farming. As these applications become increasingly sophisticated, the agriculture sensors market is poised for significant growth, driven by the need for precision farming and sustainable agricultural practices.
Segments:
Based on Product
- Physical Sensors
- Mechanical Sensors
- Chemical Sensors
Based on Application
- Yield Monitoring and Mapping
- Soil Monitoring
- Disease Control and Detection
- Irrigation and Water Management
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a significant share of the agriculture sensors market, accounting for approximately 30% of the global market. This dominance can be attributed to the region's advanced technological infrastructure and strong emphasis on precision agriculture. Farmers in the United States and Canada are increasingly adopting agriculture sensors to optimize crop management and improve yields. The integration of Internet of Things (IoT) technology with sensors facilitates real-time monitoring and data analytics, empowering farmers to make informed decisions. Additionally, government initiatives aimed at promoting sustainable farming practices further drive market growth in this region. The presence of key players, such as John Deere and Trimble Inc., contributes to innovation and the development of cutting-edge sensor technologies, enhancing the overall market landscape in North America.
Asia-Pacific
In contrast, the Asia-Pacific region is rapidly emerging as a significant player in the agriculture sensors market, expected to capture around 25% of the market share by 2032. Countries like China and India are at the forefront of this growth, driven by the increasing need for food security and sustainable agricultural practices. The region's large agricultural base and growing population necessitate the adoption of advanced technologies, including agriculture sensors, to improve productivity and resource efficiency. Government initiatives in countries such as India aim to promote digital agriculture, facilitating the integration of sensor technologies into traditional farming practices. Moreover, the availability of affordable sensor solutions is enabling smallholder farmers to adopt these technologies, further driving market expansion. As awareness of precision agriculture increases, the Asia-Pacific region is poised for substantial growth in the agriculture sensors market, shaping the future of farming practices.
Key Player Analysis
- Bosch
- Trimble Inc
- CropX Inc
- Sentera, LLC
- The Yield Pty Ltd
- Texas Instruments
- Avidor High Tech
- Libelium
- Auroras s.r.l.
- Pycno Agriculture
- Sol Chip Ltd
Competitive Analysis
The agriculture sensors market is characterized by intense competition among several leading players, including Trimble Inc., Bosch, CropX Inc., Sentera, LLC, The Yield Pty Ltd, Texas Instruments, Avidor High Tech, Libelium, Auroras s.r.l., Pycno Agriculture, and Sol Chip Ltd. Companies are increasingly leveraging the Internet of Things (IoT), artificial intelligence (AI), and data analytics to develop innovative sensor technologies that enhance agricultural productivity. Key players are integrating their sensors with advanced data management systems, allowing farmers to monitor crops in real time and make informed decisions. Additionally, there is a growing emphasis on sustainability, with many companies focusing on solutions that optimize resource usage while minimizing environmental impact. As the demand for efficient and eco-friendly agricultural practices rises, businesses are investing in research and development to remain competitive and meet the evolving needs of farmers globally. This dynamic landscape is likely to foster continuous innovation and improve the overall efficiency of agricultural operations.
Recent Developments
In January 2023, CropX Technologies, a global leader in digital solutions for agronomic farm management, acquired Tule Technologies, a precision irrigation company based in California. This acquisition brings new data capture technologies to the CropX Agronomic Farm Management System and expands its market in California drip-irrigated specialty crops.
In October 2022, Reinke Irrigation, a leading center pivot manufacturer, partnered with CropX Technologies, the developer of a digital agronomic farm management platform to ensure the optimization of water use in crop production and maximizing crop production.
In August 2022, CropX Technologies launched continuous nitrogen leaching monitoring capability. It is easier, less time-consuming, and able to supply continuous monitoring of nitrogen leaching events than traditional lab testing methods.
Market Concentration & Characteristics
The agriculture sensors market exhibits moderate to high concentration, with several key players dominating the landscape while also fostering a growing presence of niche companies. Major corporations leverage advanced technologies, such as the Internet of Things (IoT) and artificial intelligence (AI), to deliver comprehensive sensor solutions tailored for precision agriculture. The market is characterized by continuous innovation, as companies invest heavily in research and development to enhance sensor accuracy, functionality, and integration capabilities. Additionally, there is a noticeable trend towards collaboration and partnerships among industry players, which helps accelerate product development and expand market reach. The demand for sustainable agricultural practices drives market growth, prompting companies to develop eco-friendly sensors that optimize resource use and reduce environmental impact. This competitive yet dynamic environment encourages ongoing advancements, positioning the agriculture sensors market as a critical component in the evolution of modern farming practices.Top of Form
Report Coverage
The research report offers an in-depth analysis based on Product, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The agriculture sensors market is expected to grow significantly, driven by the increasing demand for precision farming.
- Technological advancements in IoT and AI will enhance sensor capabilities, providing farmers with real-time data for better decision-making.
- The adoption of sustainable farming practices will lead to the development of eco-friendly sensor solutions.
- Integration with drones and robotics will expand the functionality of agriculture sensors for monitoring large-scale operations.
- Rising investments from governments and private sectors will promote innovation and accessibility of sensor technologies.
- The emergence of affordable sensor solutions will enable smallholder farmers to adopt advanced technologies.
- Increased focus on data analytics will help farmers derive actionable insights from sensor-generated data.
- Collaborations among key industry players will drive product development and market expansion.
- Growth in e-commerce will facilitate wider distribution and availability of agriculture sensors.
- The agriculture sensors market will increasingly play a crucial role in addressing global food security challenges.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the size of Agriculture Sensors Market?
What factors are driving the growth of the Agriculture Sensors market?
What are the key segments within the Agriculture Sensors market?
Who are the major players in this Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Agriculture Sensors Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Agriculture Sensors Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2,035 million → 2032: USD 4,792.09 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Agriculture Sensors Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Agriculture Sensors Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Agriculture Sensors Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Agriculture Sensors Market Drivers
- 3.3 Agriculture Sensors Market Restraints & Challenges
- 3.4 Agriculture Sensors Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Agriculture Sensors Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Agriculture Sensors Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Agriculture Sensors category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Agriculture Sensors Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Agriculture Sensors Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Agriculture Sensors market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Agriculture Sensors Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Agriculture Sensors Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Agriculture Sensors Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Agriculture Sensors (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Agriculture Sensors Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Agriculture Sensors Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Agriculture Sensors Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Agriculture Sensors Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Agriculture Sensors Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Agriculture Sensors Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Agriculture Sensors Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Agriculture Sensors Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Agriculture Sensors Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
