
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| AI as a Service (AIaaS) Market Size 2024 | USD 8,595 Million |
| AI as a Service (AIaaS) Market, CAGR | 39.75% |
| AI as a Service (AIaaS) Market Size 2032 | USD 125,043.29 Million |
Market Overview:
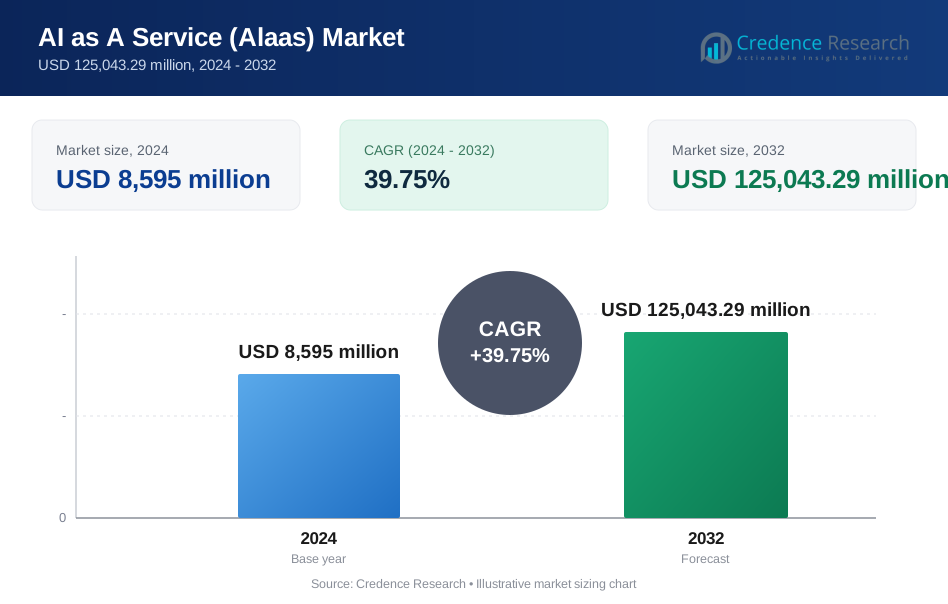
The AI As A Service (AIaaS) Market is projected to grow from USD 8,595 million in 2024 to an estimated USD 125,043.29 million by 2032, with a compound annual growth rate (CAGR) of 39.75% from 2024 to 2032.
The AIaaS market is primarily driven by the increasing demand for cloud-based artificial intelligence solutions that allow businesses to leverage advanced technologies like machine learning, natural language processing, and computer vision without needing substantial investments in infrastructure or specialized expertise. Companies, both large and small, are adopting AI solutions to automate operations, improve efficiency, personalize customer experiences, and make data-driven decisions. Additionally, AIaaS provides businesses with the flexibility to scale AI capabilities based on their specific needs, reducing costs and complexity associated with in-house AI development. One of the key factors contributing to the growth of the AIaaS market is the increasing focus on automation across industries. Organizations in sectors such as healthcare, retail, finance, and manufacturing are adopting AI to streamline workflows, enhance productivity, and gain a competitive edge. AIaaS platforms also enable businesses to access cutting-edge AI tools and services without needing to maintain a large workforce of data scientists and engineers.
Regionally, North America is expected to dominate the AIaaS market, driven by the presence of leading technology companies, significant investments in AI research and development, and a strong digital infrastructure. The United States, in particular, is a key contributor to this growth, as companies like Google, Microsoft, and Amazon continue to push the boundaries of AI technology. Europe is also experiencing rapid growth, fueled by an increasing demand for AI solutions across diverse industries. In Asia Pacific, countries like China and India are rapidly adopting AI technologies, enhancing market growth. Other regions, including Latin America and the Middle East, are also exploring AIaaS to enhance business efficiency and innovation.
Market insights:
- The AI as a Service (AIaaS) market is projected to grow from USD 8,595 million in 2024 to USD 125,043.29 million by 2032, at a CAGR of 39.75% from 2024 to 2032.
- Key drivers of market growth include the increasing demand for automation, cost-effective access to advanced AI technologies, and the ability for businesses to scale AI solutions without large upfront investments.
- The rise of machine learning, natural language processing, and computer vision technologies is significantly boosting the AIaaS market, enabling businesses across industries to enhance operational efficiency and customer experience.
- Market restraints include concerns around data privacy and security, the complexity of integrating AI technologies into existing systems, and the shortage of skilled AI professionals, which may limit adoption in some sectors.
- North America is expected to dominate the AIaaS market, driven by the presence of major tech companies, robust cloud infrastructure, and significant investments in AI research and development.
- Europe is experiencing rapid growth in AIaaS adoption, particularly in healthcare, finance, and manufacturing sectors, where AI is used for improving operational efficiency and data analytics.
- Asia Pacific, especially countries like China, India, and Japan, is seeing accelerated AI adoption due to government initiatives and increased industrial demand for automation, with the Middle East and Latin America following suit in exploring AI solutions.
Market Drivers:
Increasing Demand for Automation Across Industries:
The global push for automation is one of the primary drivers fueling the AI as a Service (AIaaS) market. Businesses are increasingly turning to AI solutions to streamline processes, improve efficiency, and reduce operational costs. Industries such as healthcare, finance, retail, and manufacturing are adopting AI technologies for various applications, including customer service automation, predictive maintenance, and data analysis. For example, according to the International Labour Organization (ILO), the automation trend will continue to rise, with nearly 30% of jobs in OECD countries being highly susceptible to automation by 2030. Governments and international organizations, including the World Economic Forum (WEF), are also emphasizing the importance of automation in achieving greater economic efficiency and productivity.
Advancements in Machine Learning and Artificial Intelligence Technologies:
The continuous evolution of machine learning (ML) and AI technologies is another crucial factor propelling the AIaaS market. Advancements in deep learning, natural language processing (NLP), and computer vision have expanded AI applications, making these technologies more valuable across various sectors. Organizations are leveraging AIaaS to integrate these advanced capabilities into their business models without the need for specialized in-house development teams. For instance, research from the U.S. Department of Energy (DOE) has highlighted the significant potential of AI and ML technologies to drive innovation across sectors such as healthcare, automotive, and cybersecurity. The DOE reports that machine learning algorithms could improve energy efficiency by up to 40% in certain industries, showing the vast potential of AIaaS for driving operational improvements.
Cost-Efficiency and Scalability of AI Solutions:
AIaaS platforms provide businesses with a cost-effective solution for adopting AI technologies, as they eliminate the need for large capital investments in hardware and skilled personnel. Organizations can scale AI capabilities according to their needs, allowing even small and medium-sized enterprises (SMEs) to benefit from AI’s power. The flexibility of AIaaS enables businesses to access cutting-edge AI solutions with minimal financial risk, reducing the barriers to AI adoption for various industries. For example, the World Bank emphasizes the importance of cloud computing solutions, noting that over 85% of global businesses are now utilizing cloud technologies. As cloud computing becomes increasingly accessible and affordable, SMEs can integrate AI solutions more easily, fostering innovation and growth in smaller businesses globally.
Rising Focus on Data-Driven Decision Making:
Data-driven decision-making has become a core business strategy for organizations looking to enhance their competitive edge. AIaaS platforms provide the tools necessary for processing and analyzing massive amounts of data, enabling businesses to derive actionable insights. AI's ability to automate data analysis in real-time supports decision-making processes across industries, improving accuracy and efficiency. For example, global data generation reached 120 zettabytes in 2023. This figure is expected to surge by 150%, reaching 181 zettabytes in 2024, as organizations worldwide increasingly adopt AI solutions to derive valuable insights from these massive datasets.
Market Trends:
Growing Integration of AI in Cloud Platforms:
The integration of artificial intelligence (AI) with cloud platforms is a leading trend within the AI as a Service (AIaaS) market. As cloud computing continues to become more widely adopted, the synergy between cloud and AI technologies is enabling businesses to scale AI-driven solutions with ease. For example, governments and international organizations are making significant investments to enhance AI adoption. The European Commission has committed over €1 billion in funding for the creation of the European Cloud Federation. This initiative aims to enhance the development of AI and cloud computing infrastructure across member states, ensuring that both the public and private sectors benefit from enhanced cloud services and AI capabilities. The EU’s commitment to AI-powered cloud solutions aligns with their broader digital transformation agenda, which expects to bolster the European economy by driving greater innovation and efficiency in the tech space.
Expansion of AIaaS in Healthcare:
AIaaS is also transforming the healthcare industry by improving diagnostics, treatment planning, and patient care. AI-driven technologies are being used to analyze large datasets for improved decision-making, predict health outcomes, and even automate administrative tasks to reduce costs. For instance, the U.S. Department of Health and Human Services (HHS) projects that AI could help reduce healthcare spending by up to $150 billion annually by 2026. The integration of AIaaS into healthcare solutions is particularly critical in the aftermath of the COVID-19 pandemic, as the healthcare sector seeks innovative ways to manage increasing demands for services. Governments, such as the U.S. and the UK, are implementing national AI strategies that include healthcare solutions powered by AIaaS to improve patient outcomes while maintaining cost-efficiency.
AIaaS Adoption in Public Services and Governance:
Governments worldwide are embracing AIaaS to enhance the efficiency and quality of public services. AI technologies are being used for everything from predictive analytics for crime prevention to automating administrative workflows and improving public health systems. For example, the United Nations (UN) has launched the "AI for Good" initiative, a global project aiming to use AI for sustainable development goals (SDGs). With a budget of over $50 million, the initiative focuses on deploying AI in disaster response, climate change mitigation, and healthcare, among other sectors. This push toward AI in governance is further exemplified by national AI strategies across the globe, including the UK and Canada, who are also investing heavily in AI-powered public services to streamline government operations and improve service delivery.
Focus on Sustainable AI Solutions:
As the demand for sustainability increases, there is a growing trend of using AIaaS to drive environmental impact and support sustainability goals. Governments, recognizing the role AI can play in energy efficiency, waste reduction, and emissions management, are increasingly integrating AI-driven solutions into their environmental policies. For instance, the U.S. Environmental Protection Agency (EPA) has invested to promote AI-powered solutions for climate change mitigation, focusing on energy-efficient technologies and carbon emissions reduction. Additionally, countries like Japan and Germany are leveraging AI to optimize renewable energy management and reduce their carbon footprints. AIaaS platforms are enabling businesses and governments to achieve sustainability targets by providing scalable AI-driven insights for optimizing energy use, reducing waste, and supporting a circular economy.
Market Challenge Analysis:
Data Privacy and Security Concerns:
One of the key challenges facing the AI as a Service (AIaaS) market is ensuring data privacy and security. As organizations increasingly rely on AI-driven platforms for sensitive data analysis, the risk of data breaches and cyberattacks also escalates. With AIaaS platforms handling vast amounts of personal, financial, and health-related information, it is essential for businesses to implement robust security protocols. For instance, the European Union's General Data Protection Regulation (GDPR) mandates strict guidelines on data protection and privacy, which has become a barrier for companies operating in the AIaaS space. Organizations must comply with these regulations to avoid legal repercussions, which can be both costly and time-consuming. The continuous need for data encryption, secure access controls, and regular security audits is critical in mitigating these risks and ensuring the safe use of AI technologies.
Integration with Legacy Systems:
Another significant challenge is the seamless integration of AIaaS solutions with existing legacy systems. Many businesses still rely on outdated IT infrastructure, which can be incompatible with advanced AI platforms. This creates a technical barrier that makes the adoption of AIaaS more complex and costly. For instance, the U.S. Federal Government, through the General Services Administration (GSA), has emphasized the need for modernizing IT systems to facilitate the use of emerging technologies like AI. Legacy systems may require costly upgrades or complete overhauls to support AI capabilities, leading to delays in implementation. Furthermore, businesses must invest in training and reskilling their workforce to adapt to new systems, which can add to the overall costs of integration. The complexity and high cost of integrating AIaaS with legacy systems remain a significant obstacle for many organizations, especially small and medium-sized enterprises (SMEs) that lack the resources to invest in such transformations.
Market Opportunities:
The AI as a Service (AIaaS) market presents significant opportunities for growth, particularly as businesses and governments worldwide continue to embrace digital transformation. One of the primary opportunities lies in the increasing adoption of AI across various sectors, such as healthcare, finance, and manufacturing. AIaaS platforms enable businesses to harness advanced technologies without substantial upfront investments in infrastructure or specialized talent. This accessibility is driving innovation, especially among small and medium-sized enterprises (SMEs), who can now leverage AI to improve operational efficiency, customer service, and data analysis. For example, the World Bank has highlighted the importance of cloud-based AI solutions for fostering growth in developing countries, where SMEs are increasingly utilizing AIaaS to compete in the global market. This trend presents a significant opportunity for AIaaS providers to expand their reach and cater to a diverse client base across different industries.
Moreover, AIaaS has the potential to address critical global challenges, such as sustainability and climate change. Governments and international organizations are increasingly integrating AI into their sustainability strategies, creating new opportunities for AIaaS providers to develop solutions that optimize energy use, reduce waste, and improve resource management. For instance, the U.S. Environmental Protection Agency (EPA) has invested in AI-driven projects focused on environmental protection, presenting a growing market for AIaaS solutions in the green technology sector. As the demand for sustainable practices intensifies, AIaaS platforms that offer scalable, cost-effective solutions will play a key role in helping organizations achieve their sustainability goals, thereby driving long-term growth in the market.
Market Segmentation Analysis:
By Technology:
The AI as a Service (AIaaS) market is segmented by technology, with machine learning, natural language processing (NLP), and computer vision being the primary drivers. Machine learning remains the dominant segment due to its wide applicability across industries such as finance, healthcare, and manufacturing, enabling predictive analytics and automation. NLP is gaining momentum as businesses increasingly adopt AI for customer service, chatbots, and sentiment analysis, particularly in retail and telecom. Computer vision, on the other hand, is growing rapidly in industries like healthcare, security, and automotive, where visual data processing is crucial. Each technology offers unique capabilities that cater to specific industry needs, and businesses are opting for tailored AI solutions based on their operational requirements.
By End-User:
The AIaaS market is also segmented by end-user industries, with BFSI, healthcare, IT and telecom, retail, and manufacturing being the major contributors. BFSI has seen rapid AI adoption for fraud detection, risk management, and customer personalization. In healthcare, AIaaS is revolutionizing diagnostics, treatment plans, and drug discovery. IT and telecom companies use AI to improve network management, customer support, and operational efficiency. Retailers are leveraging AI to enhance customer experience, inventory management, and personalized marketing. Meanwhile, manufacturers are adopting AIaaS for predictive maintenance, supply chain optimization, and automation.
Segmentation:
Based on Technology
- Machine Learning
- Natural Language Processing
- Context Awareness
- Computer Vision
Based on Enterprise Size
- Large Enterprise
- Small and Medium-sized Enterprise
Based on Deployment Mode
- Public Cloud
- Private Cloud
- Hybrid Cloud
Based on Offering
- Infrastructure as a Service (IaaS)
- Platform as a Service (PaaS)
- Software as a Service (SaaS)
Based on End User
- BFSI (Banking, Financial Services, and Insurance)
- IT and Telecom
- Retail and E-Commerce
- Healthcare and Life Science
- Government and Defense
- Manufacturing
- Energy and Utilities
- Others
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America continues to dominate the AI as a Service (AIaaS) market, accounting for nearly 40% of the global market share. This is primarily due to the region's strong technological infrastructure, high investment in AI research and development, and the presence of leading players such as Microsoft, Google, and Amazon Web Services. The U.S. is at the forefront, with significant government and corporate initiatives driving AI adoption across industries like healthcare, finance, and manufacturing. For instance, the U.S. Department of Energy has heavily invested in AI for energy efficiency and environmental solutions. Additionally, companies are increasingly adopting AIaaS for customer service automation, predictive analytics, and data processing. The region's mature tech ecosystem, along with favorable regulations and substantial venture capital funding, continues to propel the growth of AIaaS in North America.
Europe
Europe holds 30% of the global AIaaS market share, with countries like the United Kingdom, Germany, and France leading the way in AI adoption. The European Union has been particularly proactive in encouraging AI innovation through initiatives such as the Horizon 2020 program, which funds AI research. Moreover, the implementation of strict data protection regulations, such as the General Data Protection Regulation (GDPR), has also accelerated demand for secure and compliant AI solutions. For instance, the European Commission has invested over €1 billion into AI research and development as part of its digital transformation agenda. Industries such as healthcare, automotive, and finance are increasingly turning to AIaaS to enhance operational efficiency and deliver personalized services, driving significant market growth in the region.
Asia-Pacific
Asia-Pacific is expected to experience the fastest growth in the AIaaS market, capturing about 20% of the global market share. The region is home to rapidly developing economies such as China, India, and Japan, where AI adoption is expanding across industries like e-commerce, manufacturing, and finance. Governments in these countries are heavily investing in AI, with initiatives like China’s "Next Generation Artificial Intelligence Development Plan" driving AI innovation. For instance, in India, the government’s National AI Strategy aims to create AI-driven solutions to address challenges in healthcare, agriculture, and education. The region’s growing technology infrastructure and increasing demand for AI-driven automation and efficiency in sectors like IT, retail, and logistics further fuel the growth of AIaaS. With a combination of government support and increased private-sector investments, Asia-Pacific is poised to be a major contributor to the global AIaaS market.
Key Player Analysis:
- Microsoft Corporation
- Google LLC
- IBM Corporation
- Amazon Web Services, Inc.
- SAS Institute Inc.
- FICO
- Salesforce, Inc.
- Oracle Corporation
- H2O.ai, Inc.
- SAP SE
Competitive Analysis:
The competitive landscape in the AI as a Service (AIaaS) market is highly dynamic, with key players such as Microsoft Corporation, Google LLC, IBM Corporation, and Amazon Web Services leading the charge in driving innovation and market growth. These companies offer a range of AI-driven solutions, including machine learning platforms, natural language processing, and computer vision tools, catering to diverse industries such as healthcare, finance, and retail. Additionally, firms like Salesforce, Oracle, and SAP are expanding their AI capabilities, integrating AIaaS into their existing platforms to enhance customer experience and operational efficiency. The competition is also intensifying with niche players like H2O.ai, who specialize in machine learning platforms, providing tailored solutions. Companies are increasingly focusing on strengthening their product offerings through strategic partnerships, acquisitions, and investments in R&D to differentiate themselves and meet the growing demand for scalable, cost-effective AI solutions across sectors.
Recent Developments:
- In April 2023, CHATCRYPTO, a blockchain enterprise, launched its innovative ChatCrypto token, a deflationary AI-powered token designed to unlock access to blockchain as a service (BaaS), artificial intelligence as a service (AIaaS), and high-performance computing (HPC) power through its infrastructure as a service (IaaS). The ChatCrypto token aims to build a sustainable and resilient ecosystem, providing stability for both the platform and its users.
- In July 2022, IBM Corporation announced the acquisition of Databand.ai, Ltd., a leading provider of data observability software. This acquisition enhances IBM's research and development initiatives and strengthens its strategic partnerships in automation and artificial intelligence. By integrating Databand.ai with IBM's observability tools, including IBM Watson Studio and Instana APM, IBM is positioned to offer comprehensive observability across IT operations, further expanding its capabilities in AI and automation.
- In July 2022, Shenzhen Super Eagle Technology Co., Ltd., a company known for its power supply solutions, announced the launch of the IPAW Model L, an AI robot server poised to transform the hospitality industry. The IPAW Model L offers a range of features, including meal delivery, voice interaction, precise navigation, customer engagement, smart obstacle avoidance, and multi-machine collaboration. The company is currently partnering with major brands like Heineken, McDonald's, and Hilton to integrate this cutting-edge technology into their operations, bringing AI-driven solutions to the forefront of hospitality services.
Market Concentration & Characteristics:
The AI as a Service (AIaaS) market exhibits moderate to high market concentration, with a few dominant players such as Microsoft Corporation, Google LLC, IBM Corporation, and Amazon Web Services holding significant market shares. These industry leaders leverage their vast resources, extensive R&D capabilities, and established customer bases to maintain a competitive edge. Additionally, several smaller, niche players, like H2O.ai and FICO, are carving out specialized segments by offering innovative, machine learning-focused solutions. The market is characterized by rapid technological advancements, high scalability, and a growing demand for customizable, cost-effective AI solutions. As companies across various sectors increasingly adopt AIaaS to drive digital transformation, the market is also seeing rising investments in cloud infrastructure, data security, and AI integration platforms. While the leading players dominate the landscape, there is room for niche players to differentiate through specialized offerings and targeted innovations, fostering healthy competition and market evolution.
Report Coverage:
The research report offers an in-depth analysis based on By Enterprise type, By Technology, By End-User, By Offering, By Deployment, By Offering, By Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The AI as a Service (AIaaS) market will continue to expand as businesses increasingly integrate AI-driven solutions for improved operational efficiency and customer engagement.
- Advancements in machine learning and deep learning technologies will accelerate AI adoption across diverse industries, including healthcare, finance, and retail.
- Companies will focus on enhancing the scalability and flexibility of AIaaS platforms to cater to both large enterprises and small businesses.
- Increased demand for personalized AI solutions will drive providers to offer more customizable and industry-specific AI tools.
- Data privacy and security concerns will push AIaaS providers to enhance their platforms with robust security measures to comply with regulations.
- Integration of AIaaS with cloud computing platforms will grow, enabling businesses to access AI tools without heavy upfront investments in infrastructure.
- Governments and regulatory bodies will introduce more frameworks to ensure ethical use and data governance in AI applications.
- The demand for AIaaS will rise as organizations seek real-time data analysis and decision-making support.
- More strategic partnerships and acquisitions will occur, as companies aim to expand their AI capabilities and market reach.
- The focus on sustainability and climate change will drive AIaaS innovations that optimize energy consumption and reduce environmental impact.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of AI as a Service (AIaaS) market?
What factors are driving the AI as a Service (AIaaS) market?
What are the key segments within the AI as a Service (AIaaS) market?
What are some challenges faced by the AI as a Service (AIaaS) market?
Who are the major players in the AI as a Service (AIaaS) market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 AI as A Service (Alaas) Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global AI as A Service (Alaas) Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 8,595 million → 2032: USD 125,043.29 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 AI as A Service (Alaas) Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. AI as A Service (Alaas) Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 AI as A Service (Alaas) Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 AI as A Service (Alaas) Market Drivers
- 3.3 AI as A Service (Alaas) Market Restraints & Challenges
- 3.4 AI as A Service (Alaas) Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 AI as A Service (Alaas) Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 AI as A Service (Alaas) Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, AI as A Service (Alaas) category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 AI as A Service (Alaas) Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. AI as A Service (Alaas) Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the AI as A Service (Alaas) market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 AI as A Service (Alaas) Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 AI as A Service (Alaas) Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 AI as A Service (Alaas) Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in AI as A Service (Alaas) (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New AI as A Service (Alaas) Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global AI as A Service (Alaas) Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America AI as A Service (Alaas) Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe AI as A Service (Alaas) Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific AI as A Service (Alaas) Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America AI as A Service (Alaas) Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East AI as A Service (Alaas) Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa AI as A Service (Alaas) Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. AI as A Service (Alaas) Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
