
Market Overview:
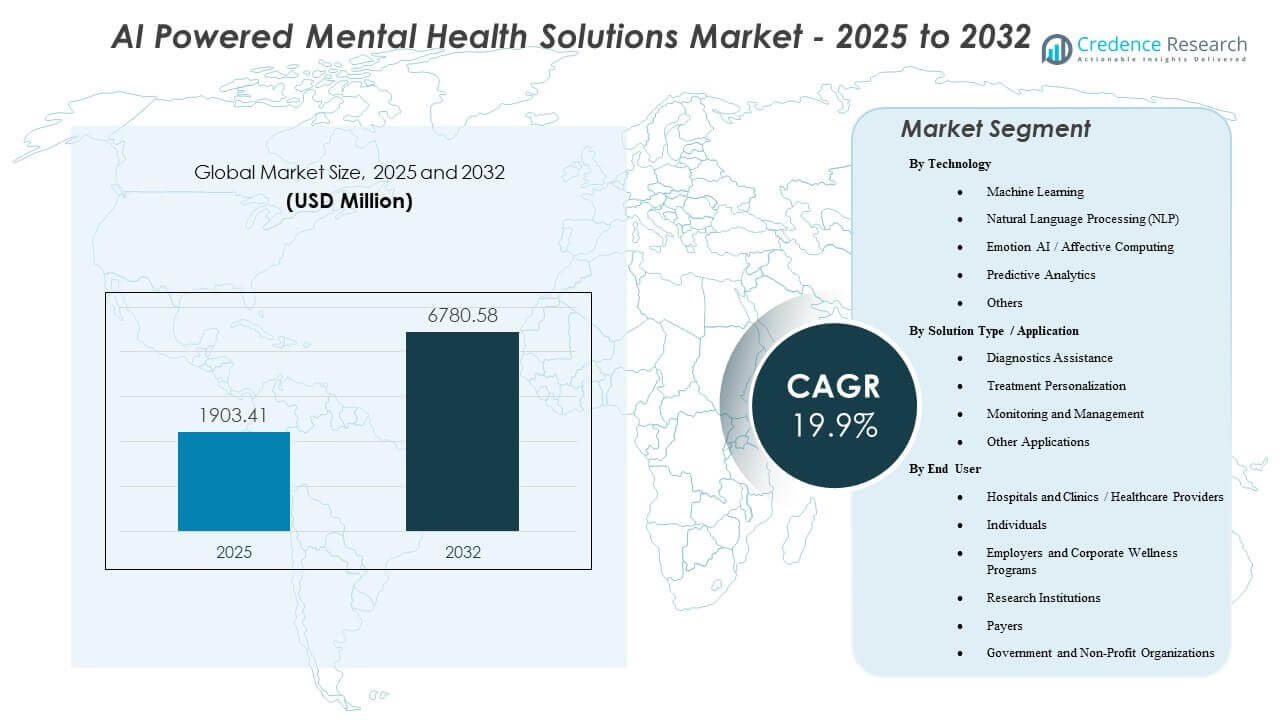
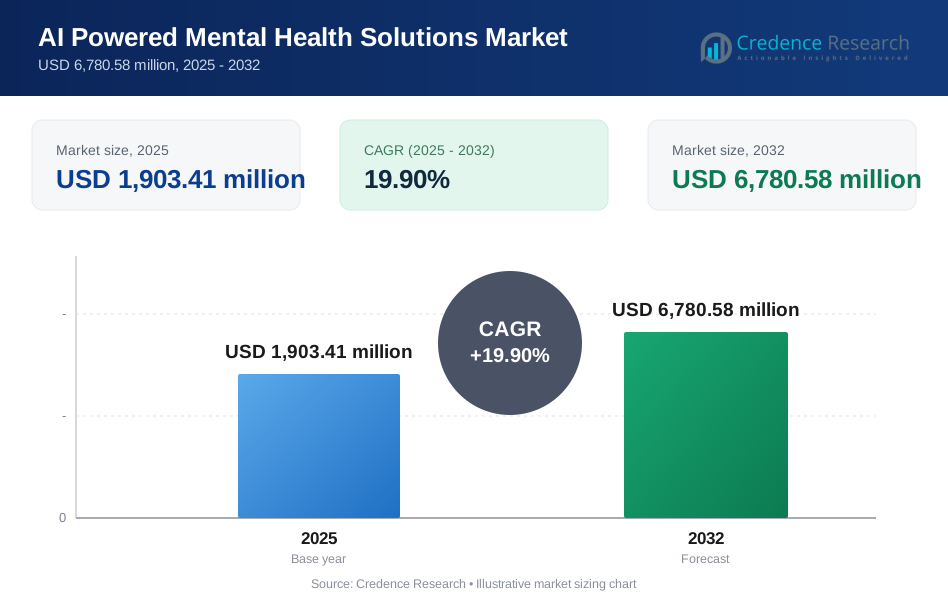
The AI Powered Mental Health Solutions Market is projected to grow from USD 1,903.41 million in 2025 to an estimated USD 6,780.58 million by 2032, registering a CAGR of 19.90% from 2025 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| AI Powered Mental Health Solutions Market Size 2025 | USD 1,903.41 million |
| AI Powered Mental Health Solutions Market, CAGR | 19.90% |
| AI Powered Mental Health Solutions Market Size 2032 | USD 6,780.58 million |
The market is being driven by rising mental health awareness, a global shortage of trained therapists, and growing smartphone penetration. AI offers scalable, 24/7 mental health assistance through virtual agents, automated CBT programs, and predictive analytics. Healthcare systems are integrating these tools to manage growing caseloads and reduce care gaps. Employers and universities are adopting AI wellness platforms for stress management and emotional support, while investors continue backing mental health tech start-ups due to rising engagement and clinical validation.
North America leads the AI Powered Mental Health Solutions Market, supported by strong digital infrastructure, mental health policy focus, and high adoption of telehealth. The U.S. is a key hub for innovation and deployment, with companies and universities piloting AI for emotional diagnostics and support. Europe follows closely, with expanding reimbursement coverage and startup activity in countries like Germany and the UK. Meanwhile, Asia-Pacific is emerging rapidly, especially in India, Japan, and Australia, where mental health stigma is lowering and digital health tools are gaining momentum.
Market Insights:
- The market was valued at USD 1,903.41 million in 2024 and is projected to reach USD 6,780.58 million by 2032, expanding at a CAGR of 19.90%, driven by rapid AI adoption in mental healthcare delivery.
- North America (~40%), Europe (~28%), and Asia-Pacific (~20%) hold the top regional shares due to strong digital health infrastructure, policy support, and high awareness of mental health solutions.
- Asia-Pacific, with around 20% share, is the fastest-growing region, supported by rising smartphone use, younger demographics, expanding telehealth access, and government digital health initiatives.
- By segment, Technology-based solutions account for nearly 45% share, led by machine learning and NLP due to their role in diagnostics, personalization, and conversational therapy tools.
- End-user distribution shows employers and corporate wellness programs at ~30% share, followed by hospitals and clinics at ~25%, reflecting strong demand for scalable and preventive mental health solutions.
Market Drivers:
Growing Demand for Mental Health Access Across Underserved Populations
Mental health support remains inaccessible for millions due to a shortage of trained professionals and high treatment costs. AI helps bridge this gap by offering 24/7 virtual assistance, symptom tracking, and self-guided therapy options. In the AI Powered Mental Health Solutions Market, tech-enabled platforms address early detection and intervention needs without increasing the clinical burden. It delivers support across rural, low-income, or stigmatized communities. Automated tools support mood analysis, depression screening, and cognitive behavioral guidance. Employers and universities adopt AI platforms to handle rising stress-related cases. The need for scalable solutions grows as awareness and demand surge. Governments also invest in mental health technology to meet rising service backlogs.
- For instance, Woebot Health’s chatbot has been used by around 1.5 million people, showing real engagement across diverse users. It delivers support across rural, low‑income, or stigmatized communities.
Integration of AI With Telehealth and Personalized Care Platforms
Telehealth expansion has created new channels for AI-enabled diagnostics and mental health care delivery. Integrated platforms use natural language processing and machine learning to screen emotions and suggest personalized therapy routines. The AI Powered Mental Health Solutions Market leverages these tools to improve triage, automate journaling, and guide therapists in care planning. It ensures consistency, fast response, and round-the-clock accessibility. Customizable content supports therapy for anxiety, depression, PTSD, and more. Digital clinics and start-ups embed AI in apps and video consultations for precise tracking of patient progress. Insurance firms also support tech-based interventions to cut long-term treatment costs. These systems help scale services without compromising clinical safety.
- For instance Wysa Gateway launched to streamline patient intake across U.S. care settings, improving access. It ensures consistency, fast response, and round‑the‑clock accessibility.
Wider Use of Predictive Analytics for Early Detection and Risk Monitoring
AI-based predictive models support real-time mood tracking, crisis alerts, and behavioral pattern analysis. These tools flag high-risk individuals before symptoms worsen. In the AI Powered Mental Health Solutions Market, advanced algorithms assess speech, writing, and behavior to detect emotional shifts. It offers preventive care, especially in populations at risk for self-harm or burnout. Schools, prisons, and large enterprises deploy sentiment-analysis platforms to ensure safety and improve well-being. Healthcare systems integrate dashboards for therapists to monitor patient journeys remotely. This proactive approach reduces hospital visits and boosts outcomes. It also helps allocate clinical resources more efficiently.
Support From Investors, Start-ups, and Government Digital Health Programs
The mental health tech ecosystem receives strong funding, pushing AI innovation across diagnostics and therapy support. Start-ups continue launching new products for mobile-first mental wellness and chatbot-guided therapy. The AI Powered Mental Health Solutions Market grows as governments expand digital health missions and partner with AI firms. It benefits from national policies aimed at reducing healthcare burdens. Incubators and research labs focus on developing ethical and culturally adaptive AI systems. Clinical trials also validate app-based mental health platforms, boosting user trust. Licensing bodies begin supporting AI software as digital therapeutics. These efforts align with growing demand for non-traditional and scalable care options.
Market Trends:
Adoption of AI-Powered Chatbots and Emotionally Intelligent Virtual Agents
AI chatbots now offer cognitive behavioral therapy, anxiety support, and guided meditation. Emotional intelligence algorithms enable more human-like conversations. The AI Powered Mental Health Solutions Market benefits from this shift as users prefer non-judgmental, always-on companions. It fosters trust and encourages engagement through familiar text-based and voice interfaces. Platforms also include mood journaling and breathing exercise modules. These agents adapt over time, learning from interaction patterns to improve support quality. Mental wellness apps increasingly integrate with wearable devices to offer real-time suggestions. Conversational AI reduces dropout rates in app-based therapy sessions.
- For instance Wysa’s empathetic CBT‑based chatbot helps users manage stress, grief, and burnout through intuitive dialogue. It fosters trust and encourages engagement through familiar text‑based.
Expansion of Voice-Based Mental Health Assessments and Speech Analytics
AI tools analyze voice pitch, speech patterns, and tone to assess emotional state and mental distress. Voice biomarkers help identify early signs of depression, anxiety, and stress. In the AI Powered Mental Health Solutions Market, companies deploy voice-enabled tools for passive monitoring. It captures insights without active user engagement, improving compliance. Call centers, healthcare providers, and therapists integrate these tools to enhance diagnostics. These assessments become part of routine virtual health check-ups. Regulatory agencies begin evaluating clinical-grade speech analytics for approval. Adoption grows across corporate wellness and elder care segments.
Use of Generative AI to Customize Therapy Content and Exercises
Generative AI tools create personalized therapy content, including guided self-reflection prompts, coping strategies, and relaxation stories. Users receive tailored interventions that evolve with mood or symptom history. The AI Powered Mental Health Solutions Market incorporates these innovations into mobile apps and platforms. It improves patient retention and satisfaction with therapy journeys. Therapists also use content engines to save time on material preparation. Platforms update modules based on clinical guidelines and user feedback. Generative AI enhances user engagement by offering fresh, relatable content. It also supports multilingual and culturally sensitive therapy access.
Integration of Mental Health AI Tools Into Enterprise and Educational Platforms
Workplaces and schools embed AI wellness tools into their digital systems for emotional well-being tracking. These integrations include daily mental check-ins, burnout risk analysis, and access to digital counselors. The AI Powered Mental Health Solutions Market gains visibility across enterprise HR, student support, and e-learning ecosystems. It reduces absenteeism and boosts productivity through early intervention. AI dashboards help institutions track trends and guide internal mental health policies. Tools remain discreet and confidential, increasing usage among youth and professionals. Demand grows for seamless API-based mental wellness integration into existing platforms. It aligns with broader corporate and academic well-being goals.
- For instance, Spring Health integrates its AI-driven mental health platform directly into corporate benefit systems for global enterprises like PepsiCo and General Mills. Their data-driven approach has enabled employees to reach "clinical remission" in an average of 5.9 weeks, which is nearly half the time of traditional care, resulting in an average of $2,430 in saved productivity costs per employee per year.
Market Challenges Analysis:
Limited Clinical Validation, Privacy Concerns, and Regulatory Hurdles Slow Widespread Adoption
Many AI mental health tools still lack peer-reviewed validation and formal clinical trials, creating hesitation among professionals. Without clear medical evidence, therapists often avoid full integration. In the AI Powered Mental Health Solutions Market, uncertainty around data privacy and model transparency continues to raise concerns. It restricts deployments in regulated healthcare environments. AI systems must handle sensitive information, including emotions and health histories, making security critical. Existing laws like HIPAA and GDPR require strict compliance, but some tools fall short. Developers face pressure to build explainable models that gain both clinician and regulator trust. Without stronger clinical partnerships, growth remains concentrated in the wellness segment rather than core healthcare.
Digital Divide and Cultural Biases in Algorithms Affect Reach and Effectiveness
AI models may underperform in diverse populations due to training data limitations. Many platforms reflect Western language, behavior, and mental health frameworks. The AI Powered Mental Health Solutions Market struggles to localize tools for regions with different expressions of emotional distress. It leads to misinterpretation or underdiagnosis in non-English-speaking users. The digital divide also limits adoption in low-income or rural settings where smartphone use and internet access are limited. Populations at highest mental health risk may remain underserved due to language, literacy, or tech access barriers. Building inclusive datasets and culturally aware designs remains a slow process. Until resolved, global reach of AI mental health tools stays uneven.
Market Opportunities:
Rising Demand for Scalable Preventive Care Tools in Corporate and Public Health Programs
Corporations and public health agencies are integrating AI-based screening and early intervention tools into wellness initiatives. The AI Powered Mental Health Solutions Market can address population-level needs through scalable, cost-efficient platforms. It supports stress reduction, burnout prevention, and resilience training. Real-time dashboards allow organizations to respond quickly to emerging trends. AI-driven insights help shape workplace mental health strategies. Governments invest in AI tools to reach underserved and high-risk groups.
Partnerships With Insurance Providers, Therapists, and Mobile Tech Firms Can Expand Reach
AI mental health platforms can scale faster through collaborations with insurers, therapists, and telecom companies. The AI Powered Mental Health Solutions Market benefits from distribution via mobile apps, telehealth networks, and employee assistance programs. These partnerships support reimbursement models, regulatory navigation, and user trust. Localized platforms also emerge through tech-health partnerships. This expansion opens new opportunities in tier-2 cities and remote communities.
Market Segmentation Analysis:
By Technology Segment: Machine Learning, NLP, Emotion AI, and Predictive Analytics Driving Innovation
Machine learning leads the technology segment with its role in real-time emotion tracking, behavior modeling, and personalization. It supports automated learning from user inputs, improving system responsiveness. Natural Language Processing (NLP) helps interpret speech and text patterns, enabling chatbots and conversational tools. Emotion AI or affective computing enhances understanding of non-verbal cues and user sentiment. Predictive analytics is vital for forecasting mental health risks and triggering early interventions. The AI Powered Mental Health Solutions Market leverages these tools to create scalable and adaptive care models. It combines data insights with user feedback loops for better outcomes. Other technologies such as reinforcement learning and computer vision are emerging in specialized applications.
- For instance through advanced NLP that enables accurate interpretation of speech and text used by apps like Wysa and Woebot. Natural Language Processing helps interpret speech and text patterns, enabling chatbots and conversational tools.
By Solution/Application Segment: Diagnostics, Treatment Personalization, and Monitoring Dominate Use Cases
Diagnostic assistance forms the foundation for many AI mental health tools by identifying emotional distress through voice, text, or behavioral data. Treatment personalization follows closely, offering tailored cognitive behavioral therapy paths or mindfulness routines. Monitoring and management tools help track mood changes, therapy progress, and medication adherence. The AI Powered Mental Health Solutions Market expands through mobile and web platforms that integrate these capabilities. It supports clinicians and individuals in real-time engagement and behavior tracking. Other applications such as self-help programs and mood journals supplement clinical tools. Demand grows for seamless user interfaces that simplify navigation across solutions. Cross-functional solutions that blend all these categories are gaining traction.
- For instance via chatbot frameworks built on CBT principles that deliver structured coaching. Monitoring and management tools help track mood changes, therapy progress, and medication adherence.
By End User Segment: Broad Adoption Across Healthcare, Individuals, and Organizations
Hospitals and clinics adopt AI tools to support therapy workflows, reduce patient loads, and optimize mental health programs. Individuals use mobile apps for self-help, emotional tracking, and guided support. Employers deploy mental wellness platforms to enhance workplace productivity and reduce absenteeism. The AI Powered Mental Health Solutions Market also includes research institutions testing experimental models and validating algorithms. Payers are interested in reducing long-term claims through preventive mental care solutions. Government and non-profit organizations integrate AI into public health frameworks to reach underserved populations. It enables wider adoption and sustainability in low-resource settings. Demand rises across both high-income and developing regions.
Segmentation:
By Technology
- Machine Learning
- Natural Language Processing (NLP)
- Emotion AI / Affective Computing
- Predictive Analytics
- Others
By Solution Type / Application
- Diagnostics Assistance
- Treatment Personalization
- Monitoring and Management
- Other Applications
By End User
- Hospitals and Clinics / Healthcare Providers
- Individuals
- Employers and Corporate Wellness Programs
- Research Institutions
- Payers
- Government and Non-Profit Organizations
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America Holds the Largest Share Due to Strong Digital Infrastructure and High Awareness
North America dominates the AI Powered Mental Health Solutions Market with over 40% share, led by the U.S. It benefits from mature healthcare systems, high adoption of telehealth, and advanced AI capabilities. The presence of leading players like Lyra Health, Talkspace, and Woebot Health supports regional growth. Government support for digital health integration and mental health parity laws drive platform deployment across public and private sectors. Employers and universities widely adopt AI mental wellness tools to address stress and burnout. Widespread smartphone penetration and insurance-backed digital care improve accessibility across demographics.
Europe Maintains a Significant Market Share Backed by Expanding Digital Health Policies
Europe holds around 28% of the global share, with Germany, the UK, and France leading adoption. It benefits from rising mental health awareness and favorable regulations supporting digital therapeutics. The European Commission’s eHealth initiatives encourage AI integration in mental healthcare delivery. Companies like Wysa and Headspace Health actively expand their footprint across European markets. Public healthcare systems partner with AI vendors to reduce clinical workload and improve early diagnosis rates. It continues advancing AI-based wellness through collaboration between startups, healthcare providers, and universities.
Asia-Pacific Emerges Rapidly with Growing Mobile Health Adoption and Youth-Driven Demand
Asia-Pacific accounts for approximately 20% share and shows the fastest growth in the AI Powered Mental Health Solutions Market. Countries like India, Japan, Australia, and South Korea lead adoption due to rising smartphone usage and increased awareness. Youth populations drive demand for app-based counselling, stress management, and emotional well-being tools. Governments invest in digital health platforms to reach remote or underserved areas. Startups introduce culturally relevant AI models tailored to local mental health needs. It sees rapid uptake of AI mental wellness solutions across education, employment, and consumer health spaces. South America and Middle East & Africa together represent around 12% of the market, showing potential in urban centers and digitally enabled healthcare systems.
Key Player Analysis:
- Woebot Health
- Wysa
- Lyra Health
- Talkspace
- Ginger
- Spring Health
- Headspace Health
- Youper
Competitive Analysis:
The AI Powered Mental Health Solutions Market features a mix of digital therapy specialists, AI-first startups, and hybrid mental healthcare providers. Companies compete on clinical credibility, AI sophistication, user engagement, and enterprise reach. Platforms such as Woebot Health, Wysa, and Youper focus on AI-driven self-help and conversational therapy tools. Firms like Lyra Health, Spring Health, and Headspace Health emphasize employer-sponsored and hybrid care models that combine AI with human clinicians. Talkspace and Ginger strengthen positions through teletherapy networks and payer partnerships. Competition centers on personalization depth, data security standards, and scalability across regions. It rewards players that align AI tools with evidence-based care and regulatory compliance. Strategic partnerships and product differentiation remain key to sustaining market presence.
Recent Developments:
- In October 2025, Lyra Health launched a clinical-grade generative AI chatbot integrated into ongoing therapy sessions, advancing AI-assisted mental health care. This tool marks a key step in blending next-generation AI with therapy for better patient outcomes.
- In March 2025, Wysa merged with April Health to integrate AI chatbots with virtual behavioral health services in primary care, enhancing continuous patient support. This move combines Wysa's AI tools for anxiety and stress with human coaches and specialists, adopted by partners like LifePoint Healthcare.
Report Coverage:
The research report offers an in-depth analysis based on Technology, Solution Type and End User segments. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- AI-powered platforms will increasingly support hybrid mental health models by combining virtual agents with licensed human therapists to improve efficiency and reach.
- Real-time emotion tracking and personalized behavioral analytics will enhance early intervention accuracy across both individual and enterprise use cases.
- Large employers and payers will continue integrating AI tools into employee assistance programs to reduce burnout, absenteeism, and turnover.
- Natural language processing and generative AI will evolve to deliver deeper conversational engagement, improving retention in long-term therapy adherence.
- Governments will expand funding for AI-based mental wellness tools, especially in public healthcare systems with long wait times for mental health consultations.
- Mobile-first, multilingual platforms will gain traction in Asia, Latin America, and Africa, helping overcome language and stigma-related barriers.
- Speech and voice analysis technologies will enter mainstream diagnostic workflows, offering continuous monitoring for high-risk populations.
- Ethical AI development will become a core differentiator, with vendors focusing on transparent algorithms and responsible data practices.
- Venture capital investments will continue fueling innovation, with startups expanding across B2B, B2C, and wellness platforms.
- Clinical trials and real-world evidence generation will support regulatory validation of AI tools, accelerating reimbursement and clinical adoption worldwide.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for AI Powered Mental Health Solutions Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the AI Powered Mental Health Solutions Market projected to grow between 2025 and 2032?
Which AI Powered Mental Health Solutions Market segment held the largest share in 2025?
What are the primary factors fueling the growth of the AI Powered Mental Health Solutions Market?
Who are the leading companies in the AI Powered Mental Health Solutions Market?
Which region commanded the largest share of the AI Powered Mental Health Solutions Market in 2025?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 1,903.41 million → 2032: USD 6,780.58 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2025
- 2.6.2 Forecast Period: 2025-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global AI Powered Mental Health Solutions Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global AI Powered Mental Health Solutions Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2025-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2025-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global AI Powered Mental Health Solutions Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2025-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global AI Powered Mental Health Solutions Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global AI Powered Mental Health Solutions Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global AI Powered Mental Health Solutions Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global AI Powered Mental Health Solutions Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global AI Powered Mental Health Solutions Market Outlook, 2025-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 1,903.41 million → 2032: USD 6,780.58 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global AI Powered Mental Health Solutions Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global AI Powered Mental Health Solutions Geographic Market Outlook, 2025-2032
- 13.1 Regional Market Size and Share, 2025
- 13.2 Regional Market Forecast, 2025-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global AI Powered Mental Health Solutions Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global AI Powered Mental Health Solutions Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

