
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Air Handling Units Market Size 2023 | USD 12,151.2 Million |
| Air Handling Units Market, CAGR | 6.80% |
| Air Handling Units Market Size 2032 | USD 21,966.47 Million |
Market Insights
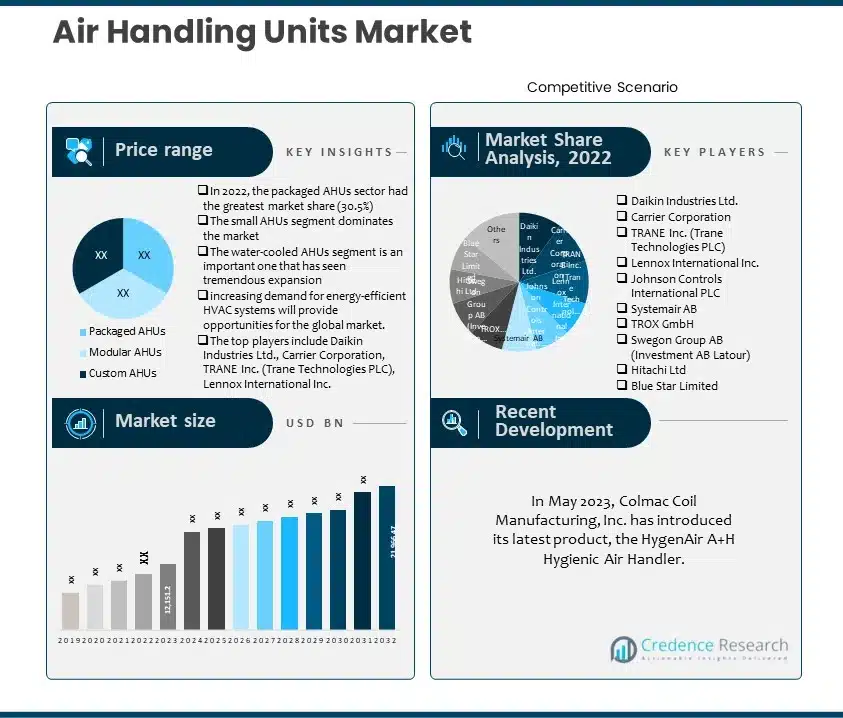
- The global demand for Air Handling Units was valued at USD 12,151.2 Million in 2023 and is expected to reach USD 21,966.47 Million in 2032, growing at a CAGR of 6.80% between 2024 and 2032.
- The packaged AHUs sector is the market leader by type, accounting for more than 40% of total value in 2023, while the modular AHUs segment is expected to grow rapidly throughout the forecast period.
- The small AHUs capacity dominates the global need for air handling units, accounting for more than 40% in 2023 and medium AHUs is predicted to expand at a high CAGR.
- The water-cooled AHUs sector is predicted to grow fastest over the projection period, while the air-cooled AHUs segment will have a market share of more than 55% in 2023.
- Over the projection period, the cooling coils category is expected to expand at the highest rate, while the fans category will dominate the market in 2023 with a 25% share.
- The commercial buildings category is expected to expand quickly over the forecast period, while the industrial facilities segment will have the greatest market share in 2023.
- The single-zone control category dominated the market with 45% of the total revenue share by control type segment. In contrast, the modular control category will expand fastest throughout the projected period.
- With a significant market share of over 45% in 2023 and projections of high CAGR growth, the sensible heat recovery category will likely continue to dominate the need for air handling units globally.
- North America is fueling the growth of the air handling units industry with over one-third share in 2023, while Asia Pacific and Europe collectively account for just under 55% share in 2023. Europe held over 20% share in 2023.
- Due to the increasing demand for energy-efficient HVAC systems to reduce carbon footprint and energy costs, the market for air handling units is growing.
- The market's primary possibilities include the significant growth potential in North America, technological advancements leading to the development of smart and connected air handling units.
Executive Summary
Market Definition
Air handling units are essential components of heating, ventilation, and air conditioning (HVAC) systems used in buildings. They work by taking in air from the environment, filtering it to remove impurities like dust and allergens, then adjusting its temperature and humidity to create a comfortable indoor environment. These units distribute the treated air throughout the building via ductwork, ensuring that occupants breathe clean and conditioned air. Additionally, air handling units can incorporate features such as heat recovery systems to improve energy efficiency by capturing and reusing heat from exhaust air. Overall, air handling units play a vital role in maintaining indoor air quality and thermal comfort in various residential, commercial, and industrial settings.
Market Overview
The global Air Handling Units market has witnessed steady growth in recent years and is expected to grow at a CAGR of 6.80% between 2024 and 2032. The market was valued at USD 12,151.2 million in 2023 and is expected to reach USD 21,966.47 million in 2032.
The key driver boosting the growth rate of the Air Handling Units market is the stringent regulations aimed at reducing carbon emissions and energy consumption, there's a growing demand for energy-efficient HVAC systems, of which air handling units are integral components. These units offer advanced features such as heat recovery, variable speed drives, and smart controls, allowing for precise temperature and humidity control while minimizing energy usage. As businesses and consumers alike prioritize environmentally-friendly solutions, the adoption of energy-efficient air handling units is expected to soar.
Furthermore, the expansion of the Air Handling Units market is actively driven by the rapid urbanization and industrialization, particularly in emerging economies, are fueling the demand for air handling units. As cities expand and infrastructural development projects multiply, there's a parallel need for efficient heating, ventilation, and air conditioning systems to maintain optimal indoor air quality in residential, commercial, and industrial buildings. Moreover, the expansion of sectors like healthcare, data centers, and pharmaceuticals requires specialized air handling solutions tailored to their unique requirements
Segmentation by Type
- Packaged AHUs is the leading segment by interface type and held over 40% share in value in 2023, attributable to the increasing demand for energy-efficient HVAC systems to reduce carbon footprint and energy costs
- The modular AHUs segment will likely exhibit a significant CAGR during the forecast period. Growing construction activities in residential, commercial, and industrial sectors worldwide.
- Custom AHUs is another segment but contributes very little to the global air handling units market compared to the packaged and modular segments.
Segmentation by Capacity
- The small AHUs segment governs the demand for air handling units in the world, holding a massive share of over 40% in 2023.
- Medium AHUs is expected to grow at a rapid CAGR due to the rising awareness among consumers regarding the importance of maintaining indoor air quality for health and productivity.
- The large AHUs sectors segment contributes to the demand for air handling units.
Segmentation by Cooling Type
- The water-cooled AHUs segment is expected to post the highest CAGR during the forecast period. This is primarily due to the technological advancements leading to the development of smart and connected air handling units.
- The air-cooled AHUs segment is leading the market share with over 55% share in 2023.
Segmentation by Component
- The cooling coils segment is anticipated to register the highest CAGR during the projection period.
- With a market share of nearly 25% in 2023, the fans category is currently in the lead.
- The category of components includes heating coils, filters, humidifiers, mixing boxes, and others.
Segmentation by End-User
- The industrial facilities dominate the global need for Air Handling Units, accounting for more than 20% in 2023.
- Commercial buildings are predicted to expand at a high CAGR during the forecast timeframe.
- The rest of the demand for air handling units comes from the residential buildings, healthcare facilities, educational institutions, and others.
Segmentation by Control Type
- In terms of value, the single-zone control category is the leading control type, with a 45% share in 2023. Expansion of the healthcare sector, driving the need for specialized air handling units for hospitals and clinics.
- During the forecast period, the modular control segment is expected to grow at the quickest rate.
Segmentation by Energy Recovery Type
- The sensible heat recovery category, expected to grow at a high CAGR and account for more than 55% of the global demand for air handling units in 2023, currently dominates this market. Urbanization and industrialization in emerging economies leading to increased demand for HVAC systems.
- The total heat recovery market accounts for the remaining need for Air Handling Units.
Segmentation by Region
- North America is fueling the growth of the Air Handling Units industry with over one-third share in 2023 due to the region's increasing investments in infrastructure projects such as airports, metro stations, and shopping malls.
- Asia Pacific and Europe collectively account for just under 55% share in 2023, with Europe holding over 20% share in the same year.
- The rest of the world, including Latin America, the Middle East, and Africa, supplies the remaining demand for Air Handling Units.
The market for Air Handling Units is driven by Adoption of air handling units with heat recovery systems for energy conservation in commercial and residential buildings.
North America boasts a mature economy with well-established infrastructure across various sectors such as commercial, residential, healthcare, and industrial. This robust infrastructure necessitates high-quality HVAC systems, including air handling units, to maintain optimal indoor air quality and temperature control. Additionally, stringent regulations and standards regarding energy efficiency and environmental sustainability drive the adoption of advanced air handling units in the region. Moreover, technological advancements and innovations in HVAC systems further contribute to North America's dominance in the air handling units market, with manufacturers continuously striving to meet the evolving needs of customers.
The Asia Pacific emerges as the fastest-growing region in the air handling units market. The rapid pace of urbanization and industrialization in countries like China, India, and Southeast Asian nations fuels the demand for HVAC systems, including air handling units, to cater to the burgeoning construction projects and expanding industrial facilities. Moreover, rising disposable incomes, growing awareness about indoor air quality, and increasing emphasis on energy efficiency drive the adoption of advanced air handling solutions in the region. Additionally, government initiatives promoting infrastructure development and sustainable building practices further propel the growth of the air handling units market in Asia Pacific. As a result, the region presents lucrative opportunities for market players seeking to capitalize on its expanding market potential and address the diverse needs of customers across various industries.
The primary factor driving the Air Handling Units market's growth rate is the stringent government regulations and policies promoting energy efficiency and indoor air quality standards. The increasing demand for energy-efficient HVAC systems to reduce carbon footprint and energy costs is one important factor that is anticipated to support the growth of the air handling units market over the forecast period.
Key Highlights of the Report
The global Air Handling Units market is segmented by type, capacity, cooling type, component, end-user, control type, energy recovery type, and region. Packaged AHUs-based Air Handling Units are the most popular, while small AHUs and air-cooled AHUs are the primary segments. In addition, fans and industrial facilities are the most commonly used categories. However, single-zone control and sensible heat recovery dominate the market, with North America leading the market growth.
One of the main factors propelling the global market for air handling units is growing construction activities in residential, commercial, and industrial sectors globally. The increasing demand for energy-efficient HVAC systems to reduce carbon footprint and energy costs drives up demand for air handling units components. The increasing adoption of air handling units with heat recovery systems for energy conservation in commercial and residential buildings is another factor boosting the size of the global market. In compact areas, the Air Handling Units is dependable and effective.
Nonetheless, North America is anticipated to have the greatest share of the worldwide air handling units market because of the technological advancements leading to the development of smart and connected air handling units. Furthermore, the market is anticipated to expand at the highest rate in the Asia-Pacific (APAC) region due to the rising disposable income levels in developing countries leading to higher spending on residential and commercial infrastructure, including HVAC systems.
What Are The Main Drivers Of The Global Air Handling Units Market?
Main drivers of the global air handling units market include increasing demand for energy-efficient HVAC systems, growth in construction activities, stringent government regulations promoting indoor air quality, rising awareness about health impacts, technological advancements, expansion of healthcare and data center sectors, urbanization, retrofitting of existing buildings, adoption of heat recovery systems, and investments in infrastructure projects.
What Are The Major Challenges Faced By The Global Air Handling Units Market?
Major challenges faced by the global air handling units market include pricing pressures due to intense competition, fluctuating raw material costs, regulatory complexities across different regions, high initial investment costs for advanced systems, skilled labor shortages for installation and maintenance, and the impact of economic downturns on construction activities.
What Are The Growth Opportunities In The Global Air Handling Units Market?
Growth opportunities in the global air handling units market include expanding into emerging markets with increasing urbanization, developing innovative and customizable solutions to meet specific customer needs, focusing on aftermarket services for maintenance and upgrades, leveraging digital technologies for smart and connected systems, partnering with energy service companies for performance-based contracts, and investing in research and development for sustainable and energy-efficient solutions.
Market Drivers
The global Air Handling Units market is driven by several factors. The following are the key drivers of the global Air Handling Units market:
Increasing Demand for Energy-Efficient HVAC Systems
One significant driver propelling the global air handling units market is the escalating demand for energy-efficient HVAC systems. As businesses and consumers become more conscious of environmental sustainability and operational costs, there's a growing preference for HVAC solutions that minimize energy consumption while maintaining optimal performance. Air handling units play a pivotal role in this regard, as they are essential components of HVAC systems responsible for treating and distributing conditioned air throughout buildings. The emphasis on energy efficiency is driven by various factors, including rising energy prices, stringent environmental regulations, and the need to reduce carbon emissions.
Businesses across industries, from commercial office buildings to manufacturing facilities, are increasingly investing in energy-efficient air handling units to lower their operational expenses and minimize their environmental footprint. Moreover, government initiatives and building codes aimed at promoting energy conservation further accelerate the adoption of energy-efficient HVAC systems worldwide. Manufacturers are responding to this demand by developing innovative air handling units with features such as variable speed drives, heat recovery systems, and smart controls, allowing for precise control over energy consumption. Therefore, the increasing demand for energy-efficient HVAC systems serves as a significant driver fueling the growth of the global air handling units market.
Market Restraints
The global Air Handling Units market faces some challenges that may hinder its growth. These include the following:
Fluctuating Raw Material Costs
A major obstacle to the market for air handling units is the fluctuating raw material costs. The manufacturing of air handling units involves various materials such as steel, aluminum, copper, and plastics, the prices of which are subject to market fluctuations influenced by factors like supply chain disruptions, geopolitical tensions, and currency fluctuations. Fluctuating raw material costs can significantly impact the profitability of air handling unit manufacturers, as sudden price hikes can erode profit margins and increase production costs.
To mitigate the impact of fluctuating raw material costs, air handling unit manufacturers often employ strategies such as hedging, sourcing from multiple suppliers, and negotiating long-term contracts. However, these measures may not fully shield manufacturers from sudden price spikes, especially in volatile market conditions. Moreover, passing on increased costs to customers through higher product prices could make air handling units less competitive in the market, potentially affecting sales volumes. Therefore, while fluctuating raw material costs present a significant challenge for the global air handling units market, proactive cost management strategies and agile supply chain practices are crucial for mitigating their impact and maintaining profitability.
Opportunities
The global Air Handling Units market offers significant growth opportunities. These include the following:
Expansion into Emerging Markets
Emerging economies in regions such as Asia Pacific, Latin America, and the Middle East are experiencing rapid urbanization, industrialization, and infrastructure development, driving the demand for HVAC systems, including air handling units. As these economies continue to grow, there's a burgeoning need for modern buildings equipped with efficient heating, ventilation, and air conditioning systems to meet the requirements of urban dwellers, businesses, and industries.
Expanding into emerging markets offers air handling unit manufacturers the opportunity to tap into new customer segments and geographic regions, thereby diversifying their revenue streams and reducing dependence on mature markets. Moreover, emerging markets often present less saturated competitive landscapes, allowing manufacturers to establish themselves as key players and capture significant market share. To capitalize on this opportunity, air handling unit manufacturers need to adapt their product offerings to suit the unique requirements and preferences of emerging market customers, such as affordability, ease of maintenance, and suitability for local climatic conditions. Additionally, establishing strong distribution networks, partnerships with local players, and investing in marketing and promotional activities are essential for successfully penetrating and growing market presence in emerging economies. Overall, expansion into emerging markets presents a promising opportunity for air handling unit manufacturers to fuel growth and drive long-term success in the global market.
Competitive Landscape
Key Players
The global Air Handling Units market is highly competitive, with several key players. Some of the major players in the market and their market share are as follows:
- Daikin Industries Ltd.
- Carrier Corporation
- TRANE Inc. (Trane Technologies PLC)
- Lennox International Inc.
- Johnson Controls International PLC
- Systemair AB
- TROX GmbH
- Swegon Group AB (Investment AB Latour)
- Hitachi Ltd
- Blue Star Limited
- Others
These organizations prioritize product innovation, distribution channel expansion, and mergers and acquisitions to stay competitive.
The global Air Handling Units market's key players continually seek to stay ahead by offering new products and developments.
In May 2023, Colmac Coil Manufacturing, Inc. has introduced its latest product, the HygenAir A+H Hygienic Air Handler. This innovative air handler is specifically engineered to enhance hygiene levels within processing room environments, particularly in industries where sanitation is of paramount importance such as food processing. Tailored to meet the stringent requirements set by the USDA and to ensure worker safety, the HygenAir A+H Hygienic Air Handler is designed to uphold high-quality standards.
In December 2022, Swegon has recently completed the acquisition of Dalair, a prominent air handling manufacturer based in the UK. Dalair holds a significant position in the UK AHU market, making this strategic move a key development for Swegon's expansion in the UK&I region. By integrating Dalair's expertise and product portfolio, Swegon aims to bolster its presence across various sectors including commercial buildings, offices, retail spaces, as well as healthcare and pharmaceutical industries in the UK&I market.
Summary of Key Findings
- The demand for air handling units is rising due to the increasing demand for energy-efficient HVAC systems, growth in construction activities, which is boosting the growth of the Air Handling Units market.
- Market segmented by type, capacity, cooling type, component, end-user, control type, energy recovery type, and region.
- Packaged AHUs-based Air Handling Units are the most popular, while small AHUs and air-cooled AHUs are the primary segments.
- Fans and industrial facilities are the most commonly used categories. However, single-zone control and sensible heat recovery dominate the market.
- North America is leading market growth; the market is highly competitive with key players including Daikin Industries Ltd., Carrier Corporation, TRANE Inc. (Trane Technologies PLC), Lennox International Inc., Johnson Controls International PLC, Systemair AB, TROX GmbH, Swegon Group AB (Investment AB Latour), Hitachi Ltd, Blue Star Limited, and Others.
Future Outlook
- Positive outlook for the global air handling units market with significant growth potential in the North American region.
- One of the main factors promoting the market's expansion is the government and business sectors' current reliance on air handling units.
- During the forecast period, pricing pressures due to intense competition, fluctuating raw material costs is a significant factor projected to restrain the growth of the air handling units market.
- Key firms must focus on product innovation, growing market reach, and maintaining competitive pricing to keep ahead of the competition.
How CXOs Can Benefit from the Credence Research Air Handling Units Market Report
The Credence Research Air Handling Units Market Report provides CXOs with a comprehensive overview of the market, including:
- Market size and growth forecast: The report provides detailed estimates of the global Air Handling Units market size, segmented by type, capacity, cooling type, component, end-user, control type, energy recovery type, and region. It also includes forecasts for the market through 2032, based on key trends and drivers.
- Market segmentation: The report segments the Air Handling Units market by type, capacity, cooling type, component, end-user, control type, energy recovery type, and region. This segmentation provides CXOs with a granular understanding of the market and the opportunities in each segment.
- Competitive landscape: The report profiles the key players in the Air Handling Units market and provides insights into their strategies, product offerings, and financial performance. This information can help CXOs to identify and assess their competition.
- Key trends and drivers: The report identifies and analyzes the key trends and drivers that are shaping the air handling units This information can help CXOs to make informed decisions about their investments and strategies.
CXOs can use the insights from the Credence Research Air Handling Units Market Report to:
- Identify growth opportunities: The report can help CXOs to identify new growth opportunities in the Air Handling Units For example, the report identifies the growing demand for Air Handling Units from HVAC providers and construction companies as a key opportunity.
- Make informed investment decisions: The report can help CXOs to make informed investment decisions about Air Handling Units. For example, the report provides insights into the key factors to consider when evaluating Air Handling Units providers and selecting Air Handling Units
- Develop competitive strategies: The report can help CXOs to develop competitive strategies for their Air Handling Units For example, the report identifies the key strategies that Air Handling Units providers are using to differentiate themselves from their competitors.
- Track market developments: The report can help CXOs to track market developments and stay ahead of the curve. For example, the report provides insights into the latest trends and innovations in the Air Handling Units
Overall, the Credence Research Air Handling Units Market Report is a valuable resource for CXOs who are looking to gain a deeper understanding of the market and identify opportunities for growth.
Segmentation
- By Type
- Packaged AHUs
- Modular AHUs
- Custom AHUs
- By Capacity
- Small AHUs
- Medium AHUs
- Large AHUs
- By Cooling Type
- Air-Cooled AHUs
- Water-Cooled AHUs
- By Component
- Heating Coils
- Cooling Coils
- Filters
- Humidifiers
- Fans
- Mixing Boxes
- Others
- By End-User
- Commercial Buildings
- Industrial Facilities
- Residential Buildings
- Healthcare Facilities
- Educational Institutions
- Others
- By Control Type
- Single-Zone Control
- Modular Control
- Custom Control
- By Energy Recovery Type
- Sensible Heat Recovery
- Total Heat Recovery
- By Region
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
- North America

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Energy Efficiency Regulations
Governments and regulatory bodies are enforcing stricter standards for energy consumption and carbon emissions in buildings, driving the adoption of advanced, energy-efficient air handling units with features like heat recovery and smart controls.
Rapid Urbanization and Infrastructure Growth
Expanding urban areas and increased construction of commercial, residential, and industrial buildings, especially in emerging economies, are fueling demand for modern HVAC systems, including air handling units.
Technological Advancements in HVAC Systems
Innovations such as smart and connected AHUs, variable speed drives, and advanced filtration are making air handling units more attractive for new installations and retrofits, supporting market growth.
Rising Awareness of Indoor Air Quality
Growing concern about health and productivity is increasing the demand for air handling units that can effectively filter and condition indoor air, particularly in sectors like healthcare, education, and commercial buildings.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the global Air Handling Units market?
What is the expected growth rate of the Air Handling Units market between 2024 and 2032?
Which segment is leading the market share in terms of type?
Which capacity segment governs the demand for Air Handling Units in the world?
Who are the major players in the global Air Handling Units market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Packaged AHUs
- 1.2.2 Modular AHUs
- 1.2.3 Custom AHUs
- 1.3 By Capacity
- 1.3.1 Small AHUs
- 1.3.2 Medium AHUs
- 1.3.3 Large AHUs
- 1.4 By End-User
- 1.4.1 Commercial Buildings
- 1.4.2 Industrial Facilities
- 1.4.3 Residential Buildings
- 1.4.4 Healthcare Facilities
- 1.4.5 Educational Institutions
- 1.4.6 Others
- 1.5 By Cooling Type
- 1.5.1 Air-Cooled AHUs
- 1.5.2 Water-Cooled AHUs
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 12,151.2 Million → 2032: USD 21,966.47 Million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Air Handling Units Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Air Handling Units Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Air Handling Units Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Air Handling Units Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Air Handling Units Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Air Handling Units Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Air Handling Units Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Air Handling Units Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 12,151.2 Million → 2032: USD 21,966.47 Million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Air Handling Units Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Packaged AHUs
- 12.3.7.2 Modular AHUs
- 12.3.7.3 Custom AHUs
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Capacity - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Small AHUs
- 12.4.7.2 Medium AHUs
- 12.4.7.3 Large AHUs
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End-User - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Commercial Buildings
- 12.5.7.2 Industrial Facilities
- 12.5.7.3 Residential Buildings
- 12.5.7.4 Healthcare Facilities
- 12.5.7.5 Educational Institutions
- 12.5.7.6 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Cooling Type - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Air-Cooled AHUs
- 12.6.7.2 Water-Cooled AHUs
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Air Handling Units End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Air Handling Units Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Air Handling Units Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Air Handling Units Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Daikin Industries Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Carrier Corporation
- 18.4 Trane Inc. (Trane Technologies PLC)
- 18.5 Lennox International Inc.
- 18.6 Johnson Controls International PLC
- 18.7 Systemair AB
- 18.8 TROX GmbH
- 18.9 Swegon Group AB
- 18.10 Hitachi Ltd
- 18.11 Blue Star Limited
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

