
Market Overview
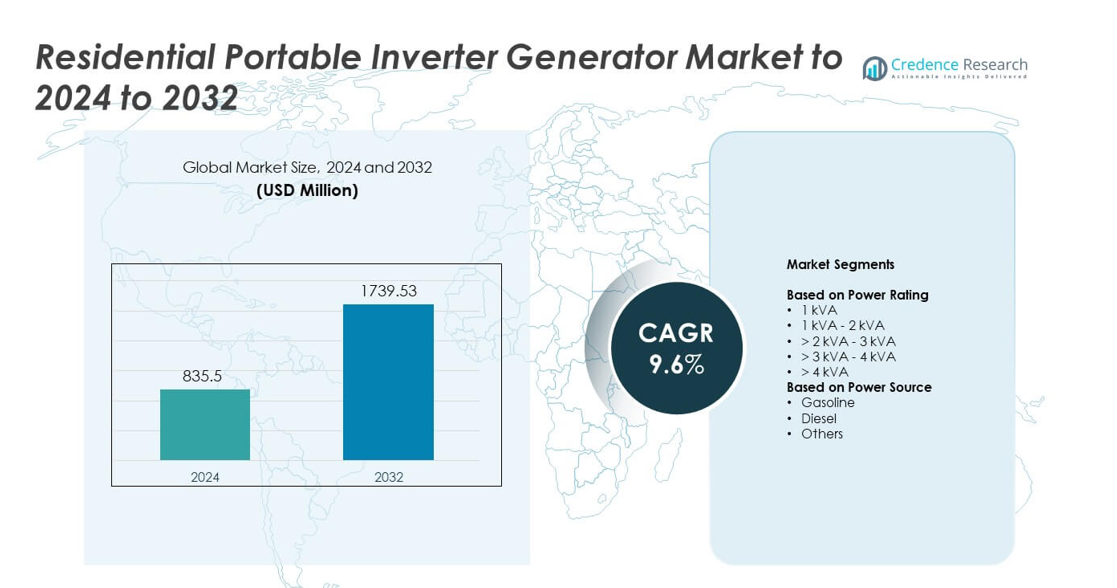
The Residential Portable Inverter Generator Market size was valued at USD 835.5 million in 2024 and is anticipated to reach USD 1,739.53 million by 2032, at a CAGR of 9.6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Residential Portable Inverter Generator Market Size 2024 | USD 835.5 million |
| Residential Portable Inverter Generator Market, CAGR | 9.6% |
| Residential Portable Inverter Generator Market Size 2032 | USD 1,739.53 million |
The Residential Portable Inverter Generator Market is led by prominent players such as Honda India Power Products Ltd., Generac Power Systems Inc., Cummins, Inc., Yamaha Motor Co., Ltd., and Briggs & Stratton. These companies focus on technological innovation, energy efficiency, and eco-friendly designs to strengthen their global presence. Continuous advancements in low-noise, fuel-efficient, and smart inverter systems have enhanced product performance and consumer adoption. North America emerged as the leading region with a 38.6% market share in 2024, driven by high household power backup demand, expanding outdoor recreational use, and strong manufacturer distribution networks across the United States and Canada.
Market Insights
- The Residential Portable Inverter Generator Market was valued at USD 835.5 million in 2024 and is projected to reach USD 1,739.53 million by 2032, growing at a CAGR of 9.6%.
- Rising power outages, expanding outdoor activities, and increasing preference for clean, quiet, and fuel-efficient backup systems are driving market growth.
- Technological advancements such as smart monitoring, hybrid fuel options, and compact designs are shaping market trends and improving operational efficiency.
- The market is moderately competitive, with key players focusing on innovation, product reliability, and emission compliance to strengthen global presence.
- North America dominated with a 38.6% share in 2024, followed by Asia Pacific at 27.8% and Europe at 25.4%, while the 1 kVA–2 kVA power rating segment led the market with 38.2% share due to high household and recreational usage demand.
Market Segmentation Analysis:
By Power Rating
The 1 kVA - 2 kVA segment dominated the residential portable inverter generator market in 2024, accounting for 38.2% of the total share. This range is preferred for small households and recreational use due to compact size, quiet operation, and high portability. Rising adoption for outdoor activities, RV camping, and backup during short power outages supports demand. Manufacturers are improving fuel efficiency and runtime to cater to home users seeking reliable, lightweight, and easy-to-use solutions, strengthening this segment’s leadership across developed and emerging markets.
- For instance, Honda’s EU2200i outputs 2,200 W max and 1,800 W rated. It runs 8.1 hours at ¼-load on a 0.95-gal tank. Noise is 48–57 dB(A), weight 47.4 lb.
By Power Source
The gasoline segment held the dominant share of 64.5% in 2024, driven by wide availability and low maintenance cost. Gasoline-powered inverter generators offer faster start-up, reduced emissions, and lower noise levels compared to conventional models. Their ease of refueling and compact design make them ideal for residential backup and recreational applications. Increasing consumer shift toward cleaner and portable power alternatives continues to favor gasoline models, while hybrid and propane variants are gradually emerging in regions promoting eco-friendly energy sources.
- For instance, the international Yamaha EF2200iS uses a 4.7-liter gasoline tank, has a dry weight of 25 kg, and a runtime of up to 10.5 hours at a quarter-load with the economy mode on. The North American version, for comparison, has a 1.24-gallon fuel tank and a dry weight of 55.2 lbs (25 kg).
Key Growth Drivers
Rising Demand for Reliable Backup Power
Frequent power outages and unstable grid supply are increasing demand for portable inverter generators in residential settings. Homeowners prefer these systems for their ability to deliver consistent and clean power suitable for sensitive electronics. Their lightweight design, quiet operation, and improved fuel efficiency enhance user convenience. Growing urbanization and dependence on electronic devices further strengthen adoption, especially in areas facing frequent weather disruptions and grid instability.
- For instance, Westinghouse’s iGen2550c runs up to 12 hours at 25% load. Fuel tank capacity is 1.11 gal. Noise is as low as 52 dBA with ≤3% THD.
Expanding Recreational and Outdoor Activities
Growth in outdoor leisure activities such as camping, tailgating, and RV travel is boosting generator use. Consumers seek compact and efficient power solutions for remote locations without permanent power access. The portability and reduced noise levels of inverter generators make them ideal for recreational use. Rising disposable income and lifestyle changes supporting outdoor experiences continue to drive steady market expansion across developed and emerging economies.
- For instance, Champion’s 2500-W inverter operates at 53 dBA. Runtime reaches up to 11.5 hours on gasoline. Parallel kit doubles available output.
Technological Advancements and Eco-Friendly Designs
Advancements in inverter technology are improving energy efficiency and reducing emissions. Modern models now integrate digital control systems, parallel connectivity, and smart monitoring features. Manufacturers are adopting cleaner fuels and hybrid technologies to meet stricter environmental regulations. These improvements are attracting eco-conscious consumers while enabling compliance with evolving emission norms, reinforcing steady growth in the residential segment.
Key Trends & Opportunities
Integration of Smart Connectivity Features
Smart inverter generators equipped with IoT-based monitoring and remote-control systems are gaining traction. Consumers benefit from real-time status updates, fuel level tracking, and predictive maintenance alerts. Such features improve user experience and operational efficiency. The growing trend toward smart home integration supports adoption, creating opportunities for manufacturers to develop connected power solutions tailored to residential needs.
- For instance, Ryobi’s 2300-W inverter integrates Bluetooth GenControl. The app displays fuel level and remaining runtime. Runtime reaches up to 10.3 hours at 25% load.
Shift Toward Low-Noise and Compact Designs
Urban homeowners increasingly prefer low-noise generators suitable for confined spaces. Manufacturers are focusing on acoustic insulation, advanced muffler systems, and vibration control to enhance user comfort. Compact and lightweight models also appeal to consumers seeking easy transport and storage. This trend supports the rising adoption of inverter generators in apartments and residential communities with noise restrictions.
- For instance, Briggs & Stratton's P2400 model specifications differ by market. The model sold in Europe and Australia (model 030800/030802) has a noise rating of 58 dB(A) at 7 meters at a 25% load, a 3.8 L fuel tank capacity, an 8-hour runtime at a 25% load, and weighs 22.7 kg.
Key Challenges
High Initial Cost and Maintenance Requirements
Portable inverter generators often involve higher upfront costs than traditional models. Advanced technologies and emission-compliant designs add to the overall price. Additionally, routine maintenance such as oil changes and filter replacements can deter price-sensitive consumers. These factors limit adoption in low-income households, especially in developing regions where cost-efficiency remains a primary purchase factor.
Environmental and Regulatory Compliance
Strict emission norms and noise regulations challenge manufacturers to balance performance with compliance. The transition to low-emission and fuel-efficient designs requires costly R&D investments. Companies face pressure to meet varying regional standards while maintaining affordability. These evolving regulatory demands slow product approvals and raise production costs, posing challenges for small and mid-sized players in the market.
Regional Analysis
North America
North America dominated the residential portable inverter generator market with a 38.6% share in 2024. The region’s leadership is driven by frequent power disruptions, rising adoption of recreational vehicles, and strong demand for home backup systems. The United States leads due to widespread use of inverter generators for residential and outdoor purposes. Increasing consumer preference for fuel-efficient and low-noise equipment supports steady market expansion. Technological innovation, combined with government emphasis on clean energy, further promotes advanced generator deployment across both urban and rural households.
Europe
Europe accounted for a 25.4% market share in 2024, supported by stringent emission norms and growing demand for eco-friendly backup power. Consumers in the United Kingdom, Germany, and France favor inverter generators for energy-efficient home power management. Expanding infrastructure modernization and renewable integration have boosted household generator usage. The shift toward compact, quiet, and low-emission models aligns with the region’s sustainability goals. Growing adoption for recreational activities such as caravanning and outdoor camping also supports market expansion across Northern and Western European countries.
Asia Pacific
Asia Pacific held a 27.8% share in 2024, driven by increasing residential electricity consumption and unreliable grid infrastructure in rural areas. Countries like China, Japan, and India lead demand due to rapid urbanization and a rising middle-class population. Manufacturers in the region are introducing cost-effective, compact, and fuel-efficient inverter generators to address household backup needs. Expanding outdoor leisure and recreational trends also support product demand. Government initiatives promoting cleaner power sources are further encouraging the transition from conventional generators to advanced inverter models across key Asian economies.
Latin America
Latin America captured a 4.6% share in 2024, fueled by increasing reliance on portable power solutions for residential and recreational use. Brazil and Mexico are the primary markets, with consumers opting for gasoline-powered inverter generators for their affordability and reliability. Frequent power fluctuations and limited grid coverage in remote areas further accelerate adoption. Growing interest in compact, easy-to-maintain systems is driving sales among households. However, limited consumer awareness and higher import costs continue to constrain large-scale adoption in certain developing parts of the region.
Middle East & Africa
The Middle East & Africa region held a 3.6% market share in 2024. Growth is driven by rising power outages, expanding residential infrastructure, and increasing investment in off-grid energy solutions. Countries such as Saudi Arabia, South Africa, and the UAE are witnessing rising adoption due to residential development and outdoor recreation trends. The preference for gasoline and hybrid inverter generators is strengthening, particularly in areas with unreliable grid networks. However, high equipment costs and limited product accessibility remain barriers to widespread adoption across rural and remote areas.
Market Segmentations:
By Power Rating
- 1 kVA
- 1 kVA - 2 kVA
- > 2 kVA - 3 kVA
- > 3 kVA - 4 kVA
- > 4 kVA
By Power Source
- Gasoline
- Diesel
- Others
By Geography
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- Italy
- U.K.
- Russia
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- Rest of Asia-Pacific
- Latin America
- Brazil
- Mexico
- Rest of Latin America
- Middle East and Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Competitive Landscape
The Residential Portable Inverter Generator Market is characterized by strong competition among key players such as Honda India Power Products Ltd., Generac Power Systems Inc., Cummins, Inc., Briggs & Stratton, Yamaha Motor Co., Ltd., Kohler Co., Kirloskar, Caterpillar, Atlas Copco, Wacker Neuson SE, Champion Power Equipment, DuroMax Power Equipment, Westinghouse Electric Corporation, A-iPower Corp., WEN Products, EcoFlow, and Deere & Company. Companies are focusing on developing advanced inverter technologies offering higher fuel efficiency, reduced emissions, and quieter operation to meet consumer and regulatory expectations. Strategic initiatives include product innovation, regional expansion, and partnerships with distributors to strengthen brand visibility and customer reach. Manufacturers are also investing in hybrid and smart inverter systems to align with growing demand for sustainable and connected solutions. Continuous focus on lightweight, compact, and easy-to-maintain designs supports market competitiveness, while aftermarket service enhancement and digital engagement remain crucial for maintaining customer loyalty and long-term growth.
Key Player Analysis
- Honda India Power Products Ltd.
- Generac Power Systems Inc.
- Cummins, Inc.
- Briggs & Stratton
- Yamaha Motor Co., Ltd.
- Kohler Co.
- Kirloskar
- Caterpillar
- Atlas Copco
- Wacker Neuson SE
- Champion Power Equipment
- DuroMax Power Equipment
- Westinghouse Electric Corporation
- A-iPower Corp.
- WEN Products
- EcoFlow
- Deere & Company
Recent Developments
- In 2024, EcoFlow launched the EcoFlow DELTA Pro 3, an ultra-powerful and user-friendly portable power station.
- In 2023, Generac Power Systems released the GP15500EFI and GP18000EFI portable generators, which feature Electronic Fuel Injection (EFI)
- In 2023, Champion Power Equipment continued to offer budget-friendly inverter models, often featuring dual-fuel technology.
Report Coverage
The research report offers an in-depth analysis based on Power Rating, Power Source and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will continue to expand with growing residential demand for reliable backup power.
- Technological upgrades will enhance fuel efficiency and reduce operational noise levels.
- Integration of smart monitoring and IoT-based control will become standard in new models.
- Hybrid and cleaner fuel options will gain popularity due to environmental regulations.
- Manufacturers will focus on lightweight, compact designs to attract urban consumers.
- Rising outdoor and recreational activities will further boost portable generator adoption.
- Partnerships between energy and electronics firms will accelerate innovation and connectivity.
- Demand from emerging economies will grow with increasing household electrification.
- Expansion of e-commerce channels will strengthen product accessibility and aftersales services.
- Continuous regulatory focus on emission standards will drive sustainable product development.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Residential Portable Inverter Generator Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Residential Portable Inverter Generator Market projected to grow between 2025 and 2032?
Which Residential Portable Inverter Generator Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Residential Portable Inverter Generator Market?
Who are the leading companies in the Residential Portable Inverter Generator Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 835.5 million → 2032: USD 1,739.53 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Residential Portable Inverter Generator Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Residential Portable Inverter Generator Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Residential Portable Inverter Generator Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Residential Portable Inverter Generator Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Residential Portable Inverter Generator Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Residential Portable Inverter Generator Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Residential Portable Inverter Generator Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Residential Portable Inverter Generator Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 835.5 million → 2032: USD 1,739.53 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Residential Portable Inverter Generator Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Residential Portable Inverter Generator Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Residential Portable Inverter Generator Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Residential Portable Inverter Generator Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

