
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
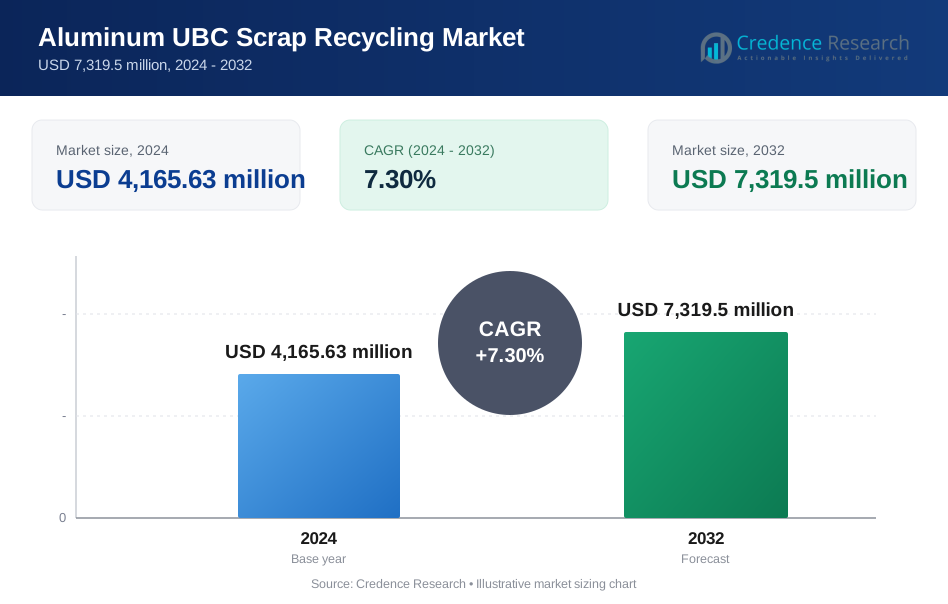
| Aluminum UBC scrap recycling market Size 2024 | USD 4,165.63 million |
| Aluminum UBC scrap recycling market, CAGR | 7.3% |
| Aluminum UBC scrap recycling market Size 2032 | USD 7,319.5 million |
Market Overview
The Aluminum UBC (Used Beverage Can) scrap recycling market is projected to grow from USD 4,165.63 million in 2024 to USD 7,319.5 million by 2032, registering a CAGR of 7.3% during the forecast period.
The Aluminum UBC scrap recycling market is gaining momentum due to increasing environmental concerns, rising demand for sustainable packaging, and the economic benefits of aluminum recycling. Used beverage cans offer a high recovery rate and retain their properties through multiple recycling cycles, making them ideal for circular economy initiatives. Governments and regulatory bodies worldwide are promoting aluminum recycling through supportive policies and mandates, especially in the beverage and food packaging sectors. Additionally, recycling UBCs requires significantly less energy than primary aluminum production, reducing greenhouse gas emissions and overall production costs. The growing popularity of aluminum cans over plastic in the beverage industry further accelerates scrap availability and recycling potential. Technological advancements in collection, sorting, and reprocessing are also improving efficiency and yield. Key trends include the expansion of closed-loop recycling systems by major beverage companies, increased investments in recycling infrastructure, and a shift toward lightweight and recyclable materials in consumer goods packaging. These factors collectively support steady market growth.
The Aluminum UBC scrap recycling market exhibits strong geographical diversity, with North America leading at 36% market share, followed by Europe at 29% and Asia-Pacific at 24%. North America benefits from mature infrastructure and corporate recycling programs, while Europe is driven by regulatory mandates and advanced collection systems. Asia-Pacific is expanding rapidly with industrial growth and policy reforms in countries like China, India, and Japan. Key players operating across these regions include Novelis Inc., Ball Corporation, Alcoa Corporation, Constellium SE, Rio Tinto Group, Norsk Hydro ASA, Ardagh Group, UACJ Corporation, Kaiser Aluminum Corporation, Tri-Arrows Aluminum Inc., Hindalco Industries Limited, Amcor Limited, and Tata Steel Limited. These companies are investing in technology, expanding regional capacities, and forming partnerships to strengthen their positions. The market reflects a blend of global leadership and regional adaptation focused on sustainability and circular economy goals.
Market Insights
- The Aluminum UBC scrap recycling market is projected to grow from USD 4,165.63 million in 2024 to USD 7,319.5 million by 2032, registering a CAGR of 7.3%.
- Rising environmental concerns and demand for sustainable packaging are driving increased use and recycling of aluminum beverage cans.
- Recycling aluminum UBCs saves up to 95% of the energy required for primary production, lowering emissions and operational costs.
- Government mandates, tax incentives, and EPR programs are compelling companies to adopt aluminum recycling and invest in closed-loop systems.
- Technological advancements in sorting and processing are improving efficiency, purity, and scalability in recycling operations.
- Inconsistent scrap collection, contamination, price volatility, and supply chain issues pose challenges to profitability and recycling efficiency.
- North America leads the market with 36% share, followed by Europe at 29% and Asia-Pacific at 24%, with key players including Novelis Inc., Ball Corporation, and Hindalco Industries driving regional growth.
Market Drivers
Rising Demand for Sustainable and Circular Packaging Solutions
The Aluminum UBC scrap recycling market is driven by the global shift toward sustainable packaging alternatives. Consumers and companies alike are prioritizing eco-friendly materials that align with circular economy goals. Aluminum beverage cans, being 100% recyclable without quality loss, are increasingly favored over plastic and glass. It supports reduced landfill waste and energy use. Governments are enforcing recycling mandates, encouraging businesses to adopt recyclable packaging. This demand sustains long-term growth for aluminum UBC recycling operations.
- For instance, Anderson Valley Brewing Company (AVBC) switched from glass bottles to aluminum cans, reducing shipping weight by 60% and minimizing breakage, while recycling aluminum cans uses 90% less energy than recycling glass bottles.
Energy and Cost Efficiency in Aluminum Recycling
Recycling aluminum from UBCs consumes up to 95% less energy compared to primary aluminum production, making it a highly cost-effective process. The Aluminum UBC scrap recycling market benefits from this energy advantage, allowing producers to reduce operational expenses and carbon footprints. It helps industries comply with emission norms while maintaining material quality. Energy savings directly translate into better profit margins, pushing companies to invest more in collection and processing infrastructure. Economic incentives make recycling a practical business strategy.
- For instance, Ball Corporation-a major supplier of aluminum beverage packaging-has documented that recycling just one ton of aluminum cans saves approximately 14,000 kWh of electricity compared to primary production.
Strong Policy Support and Industry Regulations
Government policies promoting waste management and recycling infrastructure development play a critical role in advancing the Aluminum UBC scrap recycling market. Regulations in major economies enforce collection targets and extended producer responsibility (EPR) programs. It compels beverage companies and recyclers to collaborate and close the recycling loop. Tax benefits, subsidies, and public-private partnerships further reinforce market stability. Mandatory recycling quotas ensure a steady flow of UBC scrap, supporting high-capacity plant operations. These measures strengthen regional and global market frameworks.
Technological Advancements in Recycling Processes
Continuous innovation in sorting, shredding, and melting technologies enhances efficiency and yield across the Aluminum UBC scrap recycling market. Automated systems improve separation accuracy and reduce contamination, delivering high-purity aluminum for reuse. It enables manufacturers to meet strict quality standards required in food-grade and automotive applications. Modern plants also lower labor costs and increase throughput. These advancements attract investments in next-generation recycling infrastructure. Upgraded technologies elevate competitiveness and support sustainable industry scaling.
Market Trends
Expansion of Closed-Loop Recycling Systems by Beverage Companies
Leading beverage companies are expanding closed-loop recycling systems to secure a consistent supply of recycled aluminum. These systems ensure that used cans are collected, processed, and returned to production lines without quality degradation. The Aluminum UBC scrap recycling market is benefiting from this integrated approach. It promotes operational efficiency, reduces reliance on primary aluminum, and aligns with corporate sustainability goals. Brands are also using closed-loop models for marketing, reinforcing their environmental commitment and driving consumer preference.
- For instance, Coca-Cola has launched certified closed-loop recycling at major sporting events such as the NCAA® Final Four® tournaments. In 2024, all beverage bottles and cans collected at State Farm Stadium and Rocket Mortgage FieldHouse were recycled and remade into new food-grade packaging, with an estimated 160,000 pounds of material upcycled, directly supporting Coca-Cola’s “World Without Waste” goal.
Increased Adoption of Automated Sorting Technologies
Advanced automated sorting technologies are gaining traction across recycling facilities to improve efficiency and reduce material loss. These systems utilize AI, robotics, and sensor-based sorting to enhance speed and precision. The Aluminum UBC scrap recycling market is adopting these innovations to streamline operations and increase profitability. It helps recyclers recover cleaner, higher-grade aluminum, suitable for remanufacturing. This trend also supports scalability, as facilities can manage higher volumes with reduced manual intervention and operational downtime.
Growing Emphasis on Lightweight and Recyclable Packaging
Consumer goods and beverage industries are shifting toward lightweight, recyclable packaging to minimize material use and environmental impact. Aluminum cans fit this profile, offering strength, durability, and complete recyclability. The Aluminum UBC scrap recycling market is gaining from this trend, as rising can usage leads to greater scrap availability. It supports efficient recovery and recycling cycles. Market players are partnering with manufacturers to ensure design compatibility with recycling systems, optimizing material returns and reducing waste contamination.
- For instance, Pathwater offers purified drinking water in aluminum bottles designed to be refilled and reused, highlighting aluminum’s recyclability and reduced energy use (aluminum can be recycled using five times less energy than plastic).
Global Investment in Recycling Infrastructure and Capacity Expansion
Governments and private stakeholders are making significant investments in upgrading recycling infrastructure to meet rising aluminum recovery demands. New collection networks, high-capacity furnaces, and regional processing centers are being established. The Aluminum UBC scrap recycling market is seeing capacity expansion across North America, Europe, and parts of Asia-Pacific. It strengthens supply chains and reduces transportation costs. These developments also improve recycling access and convenience, boosting consumer participation and return rates across urban and rural settings.
Market Challenges Analysis
Inconsistent Scrap Collection and Contamination Issues
One of the primary challenges in the Aluminum UBC scrap recycling market is the inconsistency in scrap collection and the high rate of contamination. Collection systems vary significantly across regions, limiting the volume and quality of UBCs entering the recycling stream. It affects processing efficiency and increases the cost of cleaning and sorting. Contaminants such as food residues, labels, and mixed materials reduce the value of recycled aluminum. Public awareness and participation in proper disposal practices remain uneven. These issues create operational hurdles for recyclers trying to maintain purity and cost efficiency.
- For instance, in the United States, the Aluminum Association has highlighted that the presence of food and liquid residues in used beverage cans (UBCs) can require extra cleaning steps at facilities like Novelis’ recycling plants, adding significant time and expense to the process.
Volatile Market Prices and Supply Chain Disruptions
Fluctuating global aluminum prices and disruptions in supply chains pose risks to the stability of the Aluminum UBC scrap recycling market. Price volatility makes long-term planning difficult for recyclers and manufacturers dependent on recycled inputs. It also affects profitability, particularly for smaller facilities with limited financial buffers. Transport bottlenecks, geopolitical tensions, and labor shortages can delay scrap movement and processing. The market faces pressure to build resilient systems that can adapt to economic uncertainty. Maintaining consistent profitability requires careful cost management and diversified sourcing strategies.
Market Opportunities
Rising Demand from Beverage and Consumer Goods Industries
The growing consumption of aluminum beverage cans offers a major opportunity for the Aluminum UBC scrap recycling market. Global brands are shifting toward aluminum packaging due to its recyclability and consumer appeal. It increases the volume of used cans available for collection and reprocessing. The move away from plastic packaging in response to regulatory pressure creates space for aluminum to dominate in multiple product categories. Recyclers can expand capacity and partner with manufacturers to secure long-term supply contracts. This demand surge supports investment in new recycling technologies and facilities.
Government Support and Circular Economy Initiatives
Policy-driven efforts to promote circular economy practices are opening new avenues for growth in the Aluminum UBC scrap recycling market. Governments are introducing incentives, stricter recycling mandates, and infrastructure development programs to enhance material recovery. It encourages public-private partnerships and facilitates funding for modernization. Urban waste management systems are evolving to support higher collection rates for UBCs. Recyclers can tap into these programs to scale operations and improve efficiency. Compliance with environmental targets will further accelerate adoption of aluminum recycling across industrial and consumer sectors.
Market Segmentation Analysis:
By Process Type
The Aluminum UBC scrap recycling market is segmented into mechanical and chemical recycling, with mechanical recycling holding a dominant share. Mechanical processes involve shredding, cleaning, and melting of UBCs, offering cost efficiency and scalability. It is widely adopted due to its lower environmental impact and energy consumption. Chemical recycling is still in the early stages but presents future potential for higher material recovery. Investments in R&D are pushing advancements in chemical methods, particularly for contaminated or composite materials.
- For instance, companies like Novelis and Constellium utilize advanced mechanical recycling lines with automated sorting and decoating technologies; Novelis’ UBC recycling plants in the US and Europe use rotary decoaters and side well furnaces to efficiently recover aluminum from beverage cans, minimizing metal loss and emissions.
By Application
Packaging remains the leading application segment in the Aluminum UBC scrap recycling market, driven by the widespread use of aluminum cans in the beverage industry. It supports a high recovery rate and forms the backbone of closed-loop recycling systems. The automotive sector is growing steadily due to the demand for lightweight components made from recycled aluminum. Building & construction and consumer goods also contribute to market expansion, leveraging recycled content to meet regulatory and sustainability goals.
- For instance, Coca-Cola has increasingly adopted aluminum bottles over plastic in select markets as part of its sustainability initiatives, contributing to the high recovery rate of aluminum in beverage packaging and supporting closed-loop recycling systems.
By End-User
Recycling plants represent the largest end-user segment, as they directly handle the collection, sorting, and processing of UBCs. The Aluminum UBC scrap recycling market also sees strong demand from smelters, which use recycled aluminum as a secondary raw material to reduce production costs. Other end-users, including third-party processors and material recovery facilities, play a supportive role by feeding the primary recycling ecosystem. Collaboration between these entities ensures efficient scrap management and market growth.
Segments:
Based on Process Type
- Mechanical Recycling
- Chemical Recycling
Based on Application
- Packaging
- Automotive
- Building & Construction
- Consumer Goods
- Others
Based on End-User
- Recycling Plants
- Smelters
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds the largest share in the Aluminum UBC scrap recycling market with 36% of the global revenue. The region has a well-established recycling infrastructure supported by strong regulatory frameworks and corporate sustainability programs. The United States leads with high aluminum can recycling rates driven by consumer awareness and extended producer responsibility initiatives. Beverage companies actively promote closed-loop systems to secure recycled aluminum supply. It benefits from advanced sorting technologies and a robust scrap collection network. Canada also contributes with national policies encouraging circular economy practices and investment in green technologies.
Europe
Europe accounts for 29% of the Aluminum UBC scrap recycling market and continues to expand under stringent environmental regulations and recycling mandates. Countries like Germany, the UK, and France enforce high recycling standards through deposit return schemes and packaging waste directives. The market benefits from strong collaboration between municipalities, recyclers, and manufacturers. It supports investment in automated facilities and chemical recycling pilot projects. The European Union’s Green Deal further pushes demand for recycled aluminum in packaging and automotive industries. Public support for sustainable practices strengthens regional collection efficiency.
Asia-Pacific
Asia-Pacific holds 24% of the Aluminum UBC scrap recycling market and is witnessing rapid growth due to urbanization, rising beverage consumption, and government-led waste management reforms. China, India, and Japan are key contributors, investing in large-scale recycling plants and infrastructure modernization. It faces challenges related to informal collection systems but offers strong growth potential with expanding industrial capacity. Governments are implementing stricter regulations on aluminum imports and promoting domestic recycling. Consumer brands are increasing aluminum packaging use, driving higher UBC scrap availability across the region. Collaboration between public and private sectors is improving collection logistics and recovery rates.
Key Player Analysis
- Kaiser Aluminum Corporation
- Tata Steel Limited
- Constellium SE
- UACJ Corporation
- Alcoa Corporation
- Novelis Inc.
- Hindalco Industries Limited
- Ball Corporation
- Ardagh Group
- Norsk Hydro ASA
- Rio Tinto Group
- Amcor Limited
- Tri-Arrows Aluminum Inc.
Competitive Analysis
The Aluminum UBC scrap recycling market features a competitive landscape with the presence of global and regional players focusing on scale, efficiency, and sustainability. Key companies such as Novelis Inc., Ball Corporation, Alcoa Corporation, and Constellium SE lead through integrated recycling operations and strategic partnerships with beverage brands. The market sees growing investment in advanced sorting and melting technologies to improve yield and reduce energy consumption. It is witnessing capacity expansion efforts to meet rising demand for recycled aluminum in packaging and automotive sectors. Companies like Rio Tinto, Norsk Hydro, and UACJ Corporation are leveraging sustainability initiatives and closed-loop systems to strengthen their market position. Competitive differentiation relies on scrap sourcing capabilities, operational efficiency, and alignment with circular economy goals. Market leaders are also targeting regional expansion and collaborating with governments and NGOs to improve collection infrastructure. The market remains dynamic, with innovation and environmental performance driving long-term success.
Recent Developments
- In February 2024, Alcoa announced that it had reached an agreement with Alumina Limited regarding the terms and process for acquiring the company, pending the execution of a scheme implementation agreement.
- On March 13, 2025, Novelis Inc. launched the world’s first aluminum coil made entirely from 100% recycled, end-of-life automotive scrap. While this product focuses on automotive scrap, Novelis is a leading company in UBC (Used Beverage Can) scrap recycling and continues to invest in expanding its recycling capabilities and technology for aluminum scrap overall.
- On April 22, 2025, The City of Greenville, Mississippi, in partnership with Every Can Counts U.S. and Replenysh, launched the state’s first “Cans for Cash” Circularity Center, offering residents $0.30 per pound for aluminum cans to boost community recycling efforts.
- On December 1, 2023, Rio Tinto and Giampaolo Group completed a joint venture agreement, giving Rio Tinto a 50% stake in Matalco, which operates six North American recycling facilities with a total capacity of approximately 900,000 tonnes per year.
Market Concentration & Characteristics
The Aluminum UBC scrap recycling market is moderately concentrated, with a mix of large multinational corporations and regional players competing across key geographies. Major companies such as Novelis Inc., Ball Corporation, Alcoa Corporation, and Constellium SE hold significant market shares due to their integrated operations, advanced technologies, and strategic supply agreements. It features high entry barriers due to capital-intensive infrastructure, regulatory compliance, and the need for efficient collection and processing systems. The market is characterized by strong emphasis on sustainability, energy efficiency, and circular economy alignment. Players differentiate through innovation in recycling processes, partnerships with beverage companies, and expansion of closed-loop systems. Geographic reach, scrap sourcing capabilities, and responsiveness to policy shifts are critical for maintaining competitiveness. The Aluminum UBC scrap recycling market shows increasing consolidation trends as companies seek to enhance capacity, secure raw materials, and improve cost structures. High recyclability and growing demand for sustainable materials continue to shape its evolution.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for recycled aluminum will continue to rise as industries prioritize sustainability and circular economy practices.
- Beverage companies will expand closed-loop recycling systems to secure consistent aluminum supply.
- Investments in advanced sorting and processing technologies will enhance material recovery and purity.
- Government policies will strengthen, enforcing higher recycling targets and promoting local scrap utilization.
- Emerging economies will develop structured collection systems to improve UBC scrap availability.
- The automotive sector will increase adoption of recycled aluminum for lightweight vehicle components.
- Partnerships between recyclers, municipalities, and packaging firms will improve collection infrastructure.
- Chemical recycling methods may see commercial adoption for contaminated or complex aluminum waste.
- Market players will focus on regional expansion to tap into growing scrap volumes and reduce logistics costs.
- Fluctuations in aluminum prices will drive more producers toward recycled inputs for cost stability.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Demand for Sustainable and Circular Packaging Solutions
The shift toward eco-friendly and recyclable packaging, especially in the beverage industry, is driving the use and recycling of aluminum cans, which are 100% recyclable and retain quality through multiple cycles.
Energy and Cost Efficiency in Aluminum Recycling
Recycling aluminum UBCs consumes up to 95% less energy than primary production, significantly reducing operational costs and emissions, making it an economically attractive option for producers and recyclers.
Strong Policy Support and Industry Regulations
Government mandates, tax incentives, and extended producer responsibility (EPR) programs are compelling companies to adopt aluminum recycling and invest in closed-loop systems, ensuring a steady supply of UBC scrap.
Technological Advancements in Recycling Processes
Innovations in automated sorting, shredding, and melting technologies are improving efficiency, yield, and purity of recycled aluminum, enabling recyclers to meet strict quality standards and scale operations.
Expansion of Closed-Loop Recycling Systems by Beverage Companies
Major beverage brands are investing in closed-loop recycling systems to secure consistent recycled aluminum supply, reduce reliance on primary aluminum, and align with corporate sustainability goals.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Aluminum UBC scrap recycling market?
What factors are driving the growth of the Aluminum UBC scrap recycling market?
What are the key segments within the Aluminum UBC scrap recycling market?
What are some challenges faced by the Aluminum UBC scrap recycling market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Recycling Plants
- 1.2.2 Smelters
- 1.2.3 Others
- 1.3 By Application
- 1.3.1 Packaging
- 1.3.2 Automotive
- 1.3.3 Building & Construction
- 1.3.4 Consumer Goods
- 1.3.5 Others
- 1.4 By Process Type
- 1.4.1 Mechanical Recycling
- 1.4.2 Chemical Recycling
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 4,165.63 million → 2032: USD 7,319.5 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Aluminum UBC Scrap Recycling Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Aluminum UBC Scrap Recycling Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Aluminum UBC Scrap Recycling Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Aluminum UBC Scrap Recycling Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Aluminum UBC Scrap Recycling Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Aluminum UBC Scrap Recycling Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Aluminum UBC Scrap Recycling Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Aluminum UBC Scrap Recycling Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 4,165.63 million → 2032: USD 7,319.5 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Aluminum UBC Scrap Recycling Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Recycling Plants
- 12.3.7.2 Smelters
- 12.3.7.3 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Packaging
- 12.4.7.2 Automotive
- 12.4.7.3 Building & Construction
- 12.4.7.4 Consumer Goods
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Process Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Mechanical Recycling
- 12.5.7.2 Chemical Recycling
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Aluminum UBC Scrap Recycling End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Aluminum UBC Scrap Recycling Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Aluminum UBC Scrap Recycling Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Aluminum UBC Scrap Recycling Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Novelis Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Ball Corporation
- 18.4 Alcoa Corporation
- 18.5 Constellium SE
- 18.6 Rio Tinto Group
- 18.7 Norsk Hydro ASA
- 18.8 Hindalco Industries Limited
- 18.9 Kaiser Aluminum Corporation
- 18.10 Ardagh Group
- 18.11 UACJ Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

