
Market Overview:
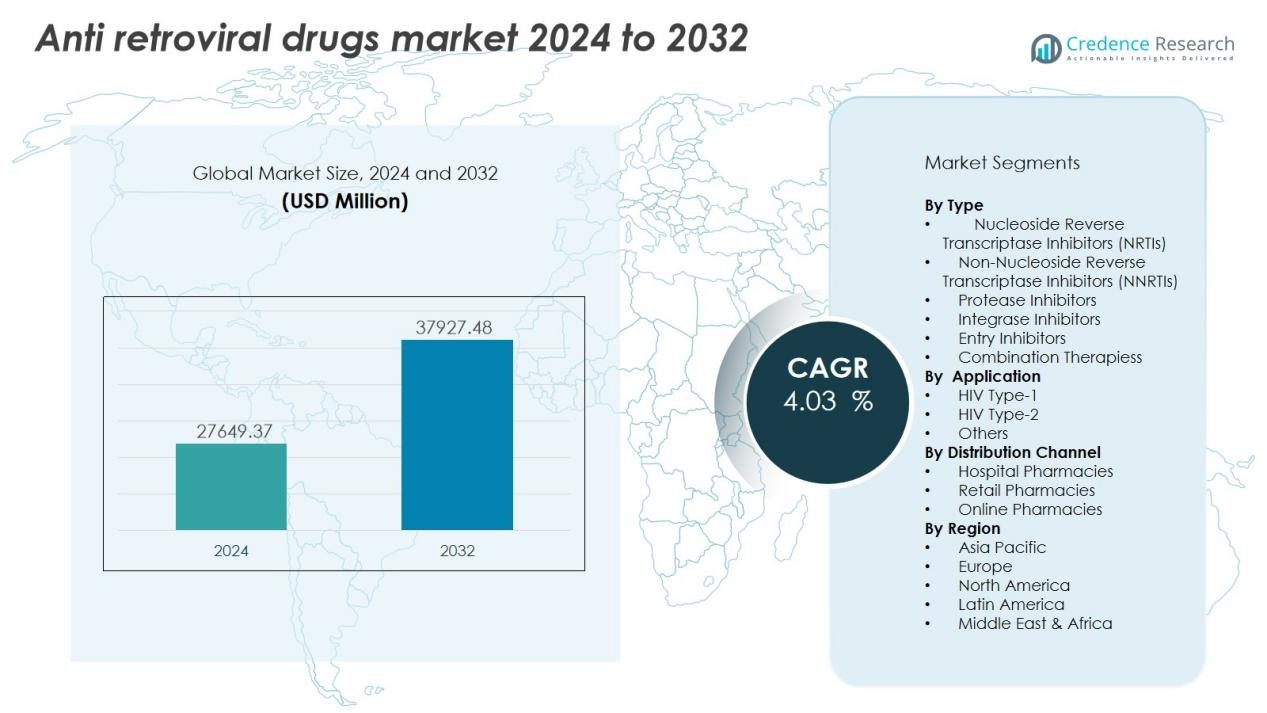
The Anti Retroviral Drugs Market size was valued at USD 27649.37 million in 2024 and is anticipated to reach USD 37927.48 million by 2032, at a CAGR of 4.03 % during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Anti Retroviral Drugs Market Size 2024 | USD 27649.37 Million |
| Anti Retroviral Drugs Market, CAGR | 4.03% |
| Anti Retroviral Drugs Market Size 2032 | USD 37927.48 Million |
The market is also supported by growing public and private healthcare investments, especially in developing regions. Advances in fixed-dose combinations and long-acting injectable therapies are reshaping treatment paradigms. Pharmaceutical companies are increasingly focusing on partnerships with global health organizations to expand access to life-saving drugs in low-income countries, further boosting demand.
Regionally, North America dominates the global market due to well-established healthcare infrastructure, high awareness levels, and strong adoption of advanced therapies. Europe holds a significant share, driven by robust reimbursement policies and supportive government programs. The Asia-Pacific region is expected to witness the fastest growth, fueled by expanding healthcare access, growing HIV prevalence, and active government initiatives in countries such as India, China, and Thailand.
Market Insights:
- The Anti-Retroviral Drugs Market was valued at USD 21,923.47 million in 2018, reached USD 27,649.37 million in 2024, and is projected to attain USD 37,927.48 million by 2032, growing at a CAGR of 4.03% during the forecast period.
- North America holds a 36% market share in 2024, driven by advanced healthcare systems, high awareness levels, and rapid adoption of next-generation therapies.
- Europe accounts for 28% share, supported by strong reimbursement frameworks, government-led access programs, and collaboration with NGOs for HIV elimination goals.
- Asia-Pacific represents 22% of the market and is the fastest-growing region, fueled by expanding healthcare infrastructure, rising HIV prevalence, and public awareness programs in India, China, and Thailand.
- By type, NRTIs dominate with a 32% share, while integrase inhibitors follow with 25%, supported by superior efficacy and reduced side effects driving preference for first-line treatment options.
Market Drivers:
Rising Global HIV Prevalence and Expanding Access to Antiretroviral Therapy
The Anti-Retroviral Drugs Market grows steadily due to the increasing global prevalence of HIV infections and expanded access to life-saving therapies. According to UNAIDS, over 39 million people were living with HIV in 2023, creating a sustained need for continuous treatment. Governments and international organizations such as WHO and PEPFAR continue to fund large-scale ART programs, enabling broader drug availability in low-income regions. This expanded access drives consistent demand and supports long-term treatment adherence.
- For Instance, Biktarvy is a leading antiretroviral drug from Gilead Sciences that has demonstrated high efficacy and durable viral suppression in clinical studies and real-world settings. In the U.S. alone, over 430,000 people were taking Biktarvy as of July 2024.
Advancements in Drug Formulations and Treatment Efficiency
Ongoing innovation in drug formulations strengthens the Anti-Retroviral Drugs Market. Pharmaceutical companies are developing fixed-dose combinations and long-acting injectables that simplify therapy and reduce dosing frequency. These innovations improve patient compliance, minimize drug resistance, and enhance overall treatment effectiveness. The shift toward integrase inhibitors and single-tablet regimens represents a significant milestone in achieving sustained viral suppression.
- For instance, ViiV Healthcare’s Cabenuva is a long-acting injectable regimen approved for HIV treatment that can be dosed once every two months, a frequency shown to be as effective as monthly dosing in clinical trials. In the pivotal clinical trials (ATLAS and FLAIR), the monthly regimen demonstrated a >90% rate of virologic suppression (specifically 92.5% to 94%) over 48 weeks, a result that was also confirmed for the every-two-months regimen in the separate ATLAS-2M trial.
Rising Government and Non-Governmental Health Initiatives
Strong policy frameworks and funding from global health organizations accelerate market expansion. Many governments integrate ART into national healthcare systems, offering free or subsidized medication to HIV-positive individuals. Non-governmental bodies such as the Global Fund and UNICEF also support awareness programs, supply-chain strengthening, and early testing initiatives. These coordinated efforts promote early diagnosis and treatment continuity, ensuring consistent drug demand.
Increasing Focus on Research, Innovation, and Preventive Therapies
R&D activities continue to enhance treatment outcomes and reduce side effects in the Anti-Retroviral Drugs Market. Companies invest heavily in developing next-generation therapies targeting resistant HIV strains. The introduction of pre-exposure prophylaxis (PrEP) and post-exposure prophylaxis (PEP) products broadens the preventive drug segment. Strategic collaborations between academia and pharmaceutical firms foster innovation and create advanced solutions that improve patient quality of life and global treatment accessibility.
Market Trends:
Shift Toward Long-Acting and Combination Therapies
The Anti-Retroviral Drugs Market is witnessing a strong shift toward long-acting formulations and fixed-dose combinations. These therapies simplify complex treatment regimens, improving patient adherence and reducing the likelihood of drug resistance. Pharmaceutical companies focus on developing injectable and implant-based options that provide sustained drug release for several weeks or months. This trend aligns with the growing need for convenient, low-maintenance HIV management solutions, particularly in developing regions with limited healthcare access. Fixed-dose combinations also reduce pill burden and improve treatment outcomes, supporting widespread adoption. Continuous advancements in drug delivery technologies are expected to transform HIV care, promoting consistent viral suppression and better patient quality of life.
- For instance, Gilead Sciences achieved a milestone with Biktarvy, a single-tablet regimen combining three antiretroviral agents, which showed 98% viral suppression at 144 weeks in Phase 3 studies, simplifying therapy for patients globally.
Integration of Digital Health Solutions and Preventive Approaches
Digital health integration is becoming a key trend shaping the Anti-Retroviral Drugs Market. Mobile health platforms and digital adherence tools enable real-time patient monitoring and improve treatment compliance. Pharmaceutical firms and health agencies increasingly collaborate on data-driven initiatives that enhance disease tracking and personalized therapy optimization. Preventive measures, such as pre-exposure prophylaxis (PrEP) and post-exposure prophylaxis (PEP), are gaining traction, driven by awareness campaigns and public health funding. These approaches help reduce new infection rates while expanding the overall patient base for preventive therapy. It continues to evolve through partnerships between governments, tech firms, and healthcare providers, reinforcing a more connected and preventive global HIV treatment ecosystem.
- For Instance, "ViiV Healthcare actively supports HIV prevention in South Africa through various initiatives, including the regulatory approval and non-profit rollout of Apretude (long-acting injectable PrEP) and its Positive Action grant program. In 2023, ViiV's Positive Action program distributed over £12.3 million in funds for 99 grants across 31 countries, reaching more than 650,000 people globally through community-led efforts, including support for adolescent girls and young women in sub-Saharan Africa.
Market Challenges Analysis:
Rising Drug Resistance and Limited Access in Low-Income Regions
The Anti-Retroviral Drugs Market faces growing challenges from drug-resistant HIV strains and uneven treatment access. Mutations reduce drug efficacy, forcing patients to switch to costlier second-line or third-line therapies. Many low- and middle-income countries still struggle with limited healthcare infrastructure and inconsistent drug supply chains. This creates treatment interruptions that worsen resistance and disease transmission. It remains critical to strengthen surveillance systems, ensure affordable drug availability, and improve adherence support to maintain therapeutic effectiveness.
High Treatment Costs and Stringent Regulatory Barriers
High pricing of branded therapies continues to restrict adoption across developing markets. Patent protection and complex approval processes delay entry of affordable generics. Governments face financial strain in sustaining free or subsidized ART programs amid rising patient numbers. Regulatory hurdles related to clinical trial approvals and safety standards slow product innovation and market entry. It must address cost-efficiency and streamline compliance to ensure sustainable global access while maintaining treatment quality and safety.
Market Opportunities:
Expansion of Long-Acting and Next-Generation Therapies
The Anti-Retroviral Drugs Market presents strong opportunities through the development of long-acting and next-generation drug formulations. Long-acting injectables and implantable devices promise better adherence and longer dosing intervals, improving patient outcomes. Pharmaceutical companies invest in nanotechnology-based delivery systems and new molecular combinations to enhance efficacy and reduce toxicity. It creates opportunities for sustained viral suppression and improved treatment convenience. Rising acceptance of once-monthly or bi-monthly therapies supports the shift toward patient-centric care models. The introduction of new drug classes targeting resistant strains further broadens therapeutic scope and market potential.
Rising Focus on Preventive Treatments and Global Health Initiatives
Preventive therapies, including pre-exposure prophylaxis (PrEP) and post-exposure prophylaxis (PEP), are expanding rapidly, offering new revenue streams. Governments and global health agencies increase funding for early intervention and awareness programs that promote prophylactic adoption. It strengthens collaboration between public institutions and private drug manufacturers to improve outreach and affordability. Growing demand for low-cost generics and regional production partnerships enhances market access in emerging economies. Digital health integration and real-time patient monitoring open new avenues for personalized treatment approaches, creating long-term growth prospects for the global anti-retroviral therapy landscape.
Market Segmentation Analysis:
By Type
The Anti-Retroviral Drugs Market is segmented into nucleoside reverse transcriptase inhibitors (NRTIs), non-nucleoside reverse transcriptase inhibitors (NNRTIs), protease inhibitors, integrase inhibitors, and entry inhibitors. NRTIs hold the largest share due to their long-standing clinical use and proven safety profile. Integrase inhibitors are gaining strong momentum owing to superior efficacy, faster viral suppression, and minimal side effects. It continues to see new drug introductions in this class, driving higher adoption across first-line therapies. Combination therapies that merge multiple drug classes in single-tablet regimens further enhance treatment convenience and patient adherence.
- For Instance, ViiV Healthcare data from the Phase IIIb VOLITION study and other sources confirm that the median time to viral suppression (defined as HIV-1 RNA <50 copies/mL) with a dolutegravir (DTG)-based regimen (specifically DTG/3TC or dolutegravir/lamivudine) in treatment-naïve patients was approximately 4.14 weeks, which is close to the cited 28 days (exactly 4 weeks).
By Application
Based on application, the market is divided into HIV Type-1, HIV Type-2, and others. HIV Type-1 dominates the segment due to its global prevalence and extensive drug pipeline. HIV Type-2 treatments are gradually expanding in parts of West Africa and Asia where incidence is higher. It benefits from growing diagnostic awareness and targeted treatment programs. Increasing focus on early-stage therapy and prevention drives product demand across both categories, strengthening long-term treatment outcomes.
- For instance, Gilead Sciences reported that its antiretroviral therapy Biktarvy achieved a viral suppression rate of 98% after 48 weeks in treatment-naïve HIV-1 patients in Phase III clinical trials.
By Distribution Channel
By distribution channel, the market includes hospital pharmacies, retail pharmacies, and online platforms. Hospital pharmacies lead due to the need for specialist supervision in ART initiation and monitoring. Retail pharmacies play a key role in improving accessibility for long-term patients. It experiences rising online distribution supported by e-pharmacy growth and government initiatives promoting telemedicine-based ART delivery in remote regions.
Segmentations:
By Type
- Nucleoside Reverse Transcriptase Inhibitors (NRTIs)
- Non-Nucleoside Reverse Transcriptase Inhibitors (NNRTIs)
- Protease Inhibitors
- Integrase Inhibitors
- Entry Inhibitors
- Combination Therapies
By Application
- HIV Type-1
- HIV Type-2
- Others
By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America Dominates with Strong Healthcare Infrastructure and Drug Accessibility
North America holds a 36% market share in the Anti-Retroviral Drugs Market in 2024, supported by advanced healthcare systems and high awareness levels. The United States leads regional demand due to strong government programs, early adoption of next-generation drugs, and a robust pharmaceutical presence. The region benefits from active research funding and rapid regulatory approvals for innovative therapies. It continues to focus on improving adherence through digital monitoring and long-acting treatment options. High diagnosis rates and widespread availability of branded and generic drugs sustain regional leadership. Canada contributes steadily through expanded ART coverage and awareness campaigns.
Europe Maintains Significant Share with Policy-Driven Access to Therapies
Europe captures 28% market share in 2024, driven by supportive reimbursement frameworks and comprehensive public health policies. Countries such as Germany, France, and the United Kingdom lead in treatment coverage and patient education initiatives. Strong regulatory emphasis on drug quality and access strengthens market stability. It experiences consistent growth through rising adoption of fixed-dose combinations and preventive therapies like PrEP. Collaborative programs between government bodies and private companies enhance early diagnosis and treatment adherence. The European market benefits from strong partnerships with NGOs focused on achieving HIV elimination goals.
Asia-Pacific Emerges as the Fastest-Growing Region with Expanding Healthcare Reach
Asia-Pacific accounts for a 22% market share in 2024 and is expected to record the highest growth through 2032. Expanding healthcare infrastructure, rising HIV incidence, and government-led ART programs drive demand. India, China, and Thailand are key contributors due to large patient populations and improving drug affordability. It benefits from local manufacturing initiatives and increasing investments in public awareness campaigns. Partnerships with global health organizations strengthen ART availability across rural and urban areas. The region’s focus on innovation and preventive care positions it as a critical growth hub in the coming years.
Key Player Analysis:
- Hoffmann-La Roche Ltd.
- GSK plc.
- AbbVie, Inc.
- Merck & Co., Inc.
- Johnson & Johnson Services, Inc.
- Bristol-Myers Squibb Company
- Cipla Inc.
- Aurobindo Pharma
- Reddy’s Laboratories Ltd.
Competitive Analysis:
The Anti-Retroviral Drugs Market is highly competitive, with several global pharmaceutical leaders driving innovation and access. Key players include F. Hoffmann-La Roche Ltd., GSK plc, AbbVie Inc., Merck & Co., Inc., and Johnson & Johnson Services, Inc. These companies focus on developing advanced therapies with improved efficacy, safety, and dosing convenience. Strategic collaborations with governments and global health organizations enhance their reach in developing regions. It emphasizes R&D investment in long-acting injectables and resistance-targeted formulations to strengthen market presence. Competitive differentiation relies on patent portfolios, affordability strategies, and continuous product innovation. Expanding generic competition and regional partnerships further intensify competition while promoting broader access to life-saving treatments.
Recent Developments:
- In October 2025, AbbVie completed the acquisition of Gilgamesh Pharmaceuticals’ Bretisilocin, a novel investigational therapy for major depressive disorder.
- In September 2025, Roche entered into a definitive merger agreement to acquire 89bio, Inc., a deal valued up to $3.5 billion, aimed at expanding its cardiovascular, renal, and metabolic portfolio with 89bio's late-stage therapies.
Report Coverage:
The research report offers an in-depth analysis based on Type, Application, Distribution Channel and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- The Anti-Retroviral Drugs Market is expected to experience sustained growth driven by continued innovation and public health investments.
- Rising adoption of long-acting injectable therapies will transform treatment adherence and convenience.
- Pharmaceutical firms will expand partnerships with global health agencies to improve drug access in low-income regions.
- Next-generation therapies focusing on resistant HIV strains will gain traction across developed markets.
- Digital health tools supporting adherence monitoring and telemedicine-based consultations will enhance treatment efficiency.
- Fixed-dose combinations will remain central to first-line therapy due to simplified dosing and improved outcomes.
- Increased focus on preventive solutions such as PrEP and PEP will broaden patient coverage.
- Local manufacturing and generic drug production will strengthen affordability and regional supply stability.
- Continuous research on vaccine development and curative approaches will shape long-term innovation efforts.
- The market will evolve toward personalized HIV management supported by genomic insights and data-driven treatment optimization.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Anti-Retroviral Drugs Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Anti-Retroviral Drugs Market projected to grow between 2024 and 2032?
Which segment held the largest share of the Anti-Retroviral Drugs Market in 2024?
What are the primary factors fueling the growth of the Anti-Retroviral Drugs Market?
Who are the leading companies in the Anti-Retroviral Drugs Market?
Which region commanded the largest share of the Anti-Retroviral Drugs Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 27,649.37 million → 2032: USD 37,927.48 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Anti Retroviral drugs Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Anti Retroviral drugs Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Anti Retroviral drugs Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Anti Retroviral drugs Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Anti Retroviral drugs Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Anti Retroviral drugs Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Anti Retroviral drugs Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Anti Retroviral drugs Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 27,649.37 million → 2032: USD 37,927.48 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Anti Retroviral drugs Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Anti Retroviral drugs Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Anti Retroviral drugs Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Anti Retroviral drugs Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

