
Antidepressants Market Overview:
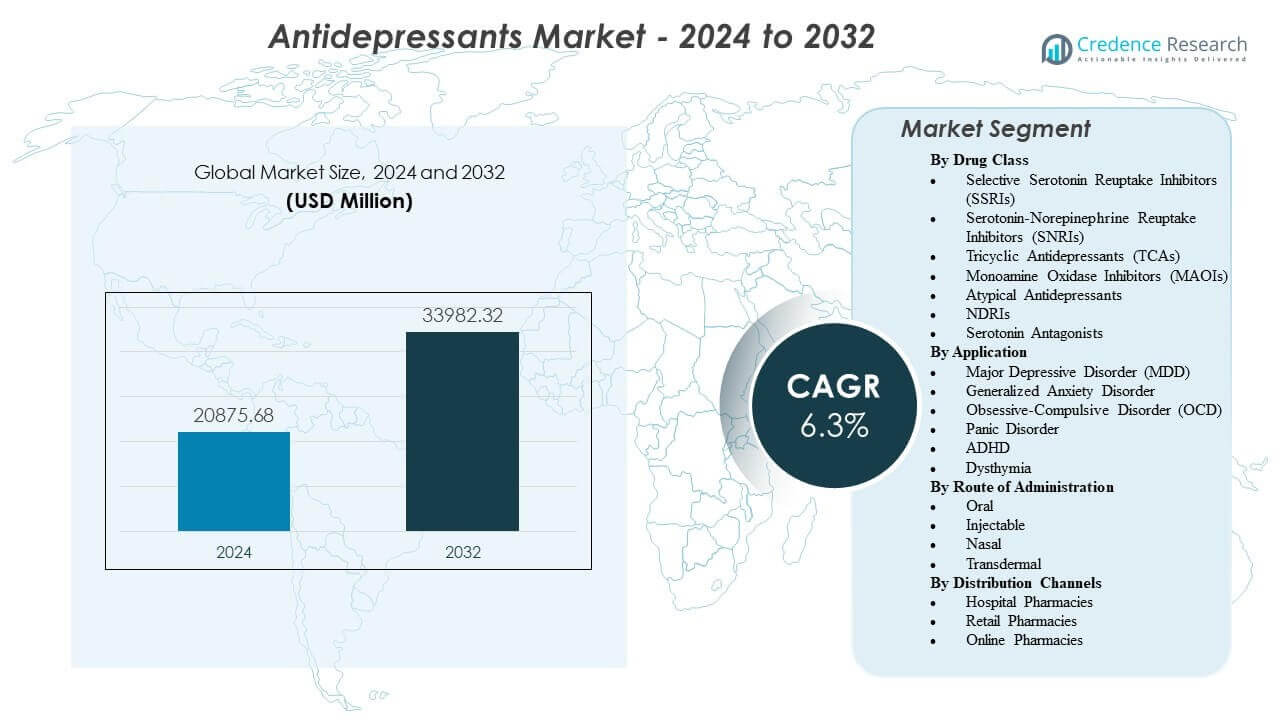
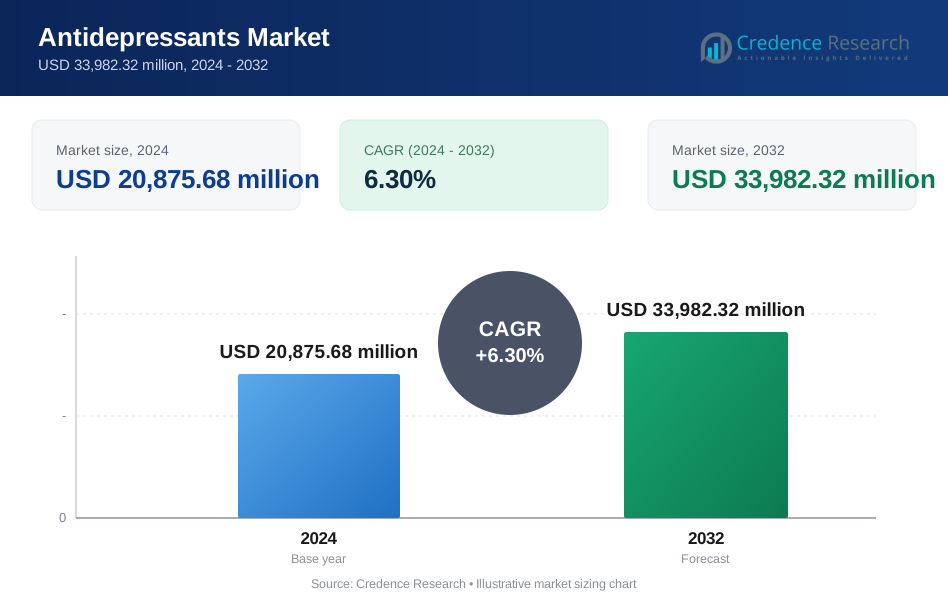
The Antidepressants Market is projected to grow from USD 20,875.68 million in 2024 to an estimated USD 33,982.32 million by 2032, with a compound annual growth rate (CAGR) of 6.3% from 2024 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Antidepressants Market Size 2024 | USD 20,875.68 million |
| Antidepressants Market, CAGR | 6.3% |
| Antidepressants Market Size 2032 | USD 33,982.32 million |
Market drivers include rising stress levels, higher prevalence of major depressive disorder, and strong preference for safer antidepressant classes with improved tolerability. Healthcare providers adopt therapies supported by real-world evidence and rapid-effect mechanisms that address treatment-resistant conditions. Innovation in digital mental health platforms enables earlier diagnosis and better medication management, which boosts adherence and therapeutic outcomes. Active investment in novel mechanisms, such as NMDA pathway modulation, enhances future treatment options. Growing awareness campaigns encourage individuals to seek structured psychiatric care. These combined forces reinforce sustained momentum across the Antidepressants Market.
North America leads due to strong healthcare infrastructure, wide availability of psychiatric services, and early adoption of advanced drug therapies. Europe maintains a significant share through established reimbursement systems and standardized clinical guidelines that support long-term treatment continuity. Asia Pacific emerges as the fastest-growing region driven by expanding mental health programs, increasing diagnosis rates in urban centers, and rising acceptance of pharmacological therapy. Latin America shows gradual improvement through strengthening healthcare networks. The Middle East and Africa progress steadily as stigma decreases and access to mental health services improves across developing regions.Top of Form
Antidepressants Market Insights:
- The Antidepressants Market is projected to grow from USD 20,875.68 million in 2024 to USD 33,982.32 million by 2032, reflecting a 6.3% CAGR driven by rising treatment demand.
- Growing awareness, improved screening programs, and adoption of safer drug classes support stronger long-term medication use across diverse patient groups.
- Treatment challenges persist due to side effects, limited response in treatment-resistant cases, and varying patient adherence levels across regions.
- North America leads the market due to strong psychiatric care networks and high adoption of advanced therapies.
- Asia Pacific shows the fastest growth as diagnosis rates rise, stigma declines, and mental health services expand across major urban centers.
Antidepressants Market Drivers
Rising Global Burden of Depression and Expanding Diagnosis Rates
Growing awareness of mental disorders drives early patient engagement and wider screening programs across regions. Demand for treatment increases when healthcare systems promote routine mental health assessments. The Antidepressants Market gains strength when patients receive timely diagnoses and structured therapy plans. Public campaigns encourage individuals to seek help without fear of stigma. Governments integrate mental health into primary care to support larger treatment volumes. Youth and working-age groups show higher help-seeking behavior due to rising stress levels. Digital tools simplify initial assessments. It promotes stronger treatment adoption across diverse demographics.
Shift Toward Safer Drug Classes and Better Tolerability Profiles
Healthcare providers prefer medications with improved safety and lower discontinuation risk. Newer classes support long-term adherence by limiting severe side effects. It becomes easier for physicians to prescribe options that suit varied patient needs. Developers focus on molecules that support faster symptom relief. Clinical guidelines highlight therapies with balanced efficacy and tolerability. Expanding research on serotonin and norepinephrine pathways supports wider product uptake. Physicians choose targeted therapies when treating chronic forms. Market momentum grows as patients report higher satisfaction with stable treatment cycles.
- For instance, Sage Therapeutics reported that zuranolone achieved clinically significant improvement within three days in Phase III trials for depressive episodes, demonstrating a rapid-action mechanism distinct from SSRIs.
Growth in Telemedicine Use and Remote Mental Health Consultations
Telehealth platforms expand access for patients with limited mobility or poor local infrastructure. It supports consistent follow-ups and medication adjustments. Online psychiatric services reduce wait times in crowded health systems. Remote care encourages adherence among individuals seeking privacy. Virtual clinics handle large patient loads through structured treatment workflows. Improved internet coverage strengthens digital care delivery. Pharmacies integrate online prescription services to ease medication access. Long-term engagement increases due to flexible appointment structures.
Surge in Research for Novel Mechanisms Addressing Treatment Resistance
Pharmaceutical firms invest in drugs targeting rapid symptom improvement. Ketamine-based therapies and new receptor modulators attract strong clinical interest. Many patients show limited response to older treatments, which pushes innovation. The Antidepressants Market benefits when research groups expand trials for treatment-resistant cases. Developers study neural circuitry to identify faster-acting pathways. Hospitals explore advanced options for severe episodes. Regulators accelerate review timelines for breakthrough therapies. New approvals expand the therapeutic landscape for complex patient needs.
- For instance, COMPASS Pathways’ Phase IIb trial for COMP360 psilocybin therapy reported a −12-point reduction in MADRS scores at week three with the 25 mg dose, demonstrating statistically significant improvement over the comparator group.
Market Trends
Adoption of Personalized Treatment Models Guided by Biomarkers
Clinicians study genetic markers and patient profiles to select suitable therapies. It helps reduce trial-and-error periods that often delay recovery. Predictive tools guide dosing choices and limit adverse reactions. AI-based platforms support decision-making during clinical visits. Biomarker studies help classify depression types more clearly. Healthcare systems invest in precision tools to support better outcomes. Research groups test companion diagnostics for future pipelines. The Antidepressants Market evolves toward individualized care structures.
Expansion of Digital Therapeutics Integrated With Medication Pathways
Digital tools combine structured therapy modules with medication support plans. It helps patients maintain regular tracking of symptoms and milestones. Platforms encourage behavioral reinforcement and improve engagement. Clinicians use dashboards to monitor patient progress. Mobile apps offer guided sessions that complement pharmacologic action. Regulators review more digital solutions for potential approvals. Younger populations value technology-enabled mental health tools. Demand for hybrid therapeutic models grows across regions.
- For instance, Headspace Health reported that digitally guided CBT modules delivered around 32% reduction in depressive symptom scores after eight weeks when paired with medication plans.
Increase in Multimodal Treatment Approaches Enhancing Clinical Outcomes
Healthcare providers combine psychotherapy, neuromodulation, and medication to improve remission rates. It supports comprehensive plans for individuals with complex needs. Clinics adopt multidisciplinary care pathways to reduce relapse risk. Collaborative care programs coordinate psychiatrists, psychologists, and primary physicians. Structured treatment plans improve stability during severe episodes. Hospitals train teams to deliver integrated support. Demand for holistic care rises across urban centers. The Antidepressants Market shifts toward outcome-driven treatment combinations.
- For instance, BrainsWay’s Deep TMS system demonstrated a 60% response rate using its H1-coil technology in major depressive disorder patients in pivotal trials, leading to expansion in integrated psychiatric programs.
Strong Pipeline Activity in Rapid-Acting Neuropsychiatric Agents
Companies test fast-acting mechanisms that reduce symptom severity quickly. It reflects rising interest in alternatives to conventional slow-acting agents. NMDA-modulating candidates show promising early results. Clinics evaluate agents with measurable improvement within hours or days. Pipeline strength grows across Europe, North America, and Japan. Regulators track safety data for accelerated pathways. Studies prioritize patients with high relapse risk. Innovation pace increases across late-stage programs.
Market Challenges Analysis
High Discontinuation Rates and Limited Response in Many Patient Groups
Many patients discontinue therapy due to side effects and low perceived benefit. It weakens long-term disease management when remission requires steady medication use. Primary care settings struggle to adjust treatment quickly for non-responders. Many physicians lack tools to predict patient response accurately. The Antidepressants Market faces gaps in meeting the needs of resistant cases. Slow-acting therapies hinder urgent symptom control in high-severity groups. Public hesitation toward pharmacologic treatments limits adoption in some areas. Underreporting of symptoms delays optimized treatment cycles.
Persistent Stigma, Uneven Access, and Regulatory Pressures on New Therapies
Stigma remains a barrier in rural regions where mental health discussions remain limited. It lowers treatment uptake even when services are available. Many countries lack enough psychiatric specialists to manage rising demand. Regulatory agencies place strict safety requirements on new drugs. Market entry becomes difficult for smaller companies. Insurance gaps restrict access to advanced therapies. Variation in national reimbursement policies affects product penetration. Global disparities reduce equal distribution of effective treatments.
Market Opportunities
Growing Demand for Rapid-Relief Therapies and Novel Neuromodulation Options
Severe depression cases require quick symptom improvement to support patient stability. It creates strong interest in fast-acting drug classes and device-based interventions. Emerging neurostimulation technologies gain traction across advanced healthcare systems. Hospitals evaluate ketamine-derived formulations for acute episodes. The Antidepressants Market sees strong engagement from innovators exploring new neural pathways. Clinical programs expand in regions supporting accelerated reviews. Providers seek tools that reduce relapse risk. Investment in next-generation therapies grows each year.
Rising Acceptance of Integrated Care and Digital-Enabled Mental Health Models
Integrated systems combine therapy, counseling, and medication under unified structures. It encourages consistent patient engagement and better progress tracking. Digital mental health platforms reach underserved populations efficiently. Providers deliver structured care without geographic limits. Remote prescription services support regular treatment continuation. Hybrid care strengthens long-term outcomes across diverse age groups. Awareness campaigns promote early intervention. Market expansion grows as public comfort with mental health support improves.
Antidepressants Market Segmentation Analysis:
By Drug Class
Selective serotonin reuptake inhibitors lead use due to strong safety profiles and broad clinical acceptance. SNRIs gain steady traction for patients needing dual-pathway action. TCAs retain relevance for severe or chronic cases despite higher side-effect risks. MAOIs serve niche groups where other therapies fail. Atypical antidepressants expand treatment flexibility for diverse symptom patterns. NDRIs support patients who require energizing effects without sedation. Serotonin antagonists help manage complex behavioral symptoms. The Antidepressants Market benefits from wide therapeutic diversity across these classes.
By Application
Major depressive disorder drives highest demand due to global prevalence and long treatment cycles. Generalized anxiety disorder patients support strong prescription volumes in primary care settings. OCD needs structured therapy and steady pharmacologic support, which strengthens long-term uptake. Panic disorder patients use rapid-acting and preventive therapies under guided care. ADHD cases rely on select antidepressant classes for symptom control in specific patient groups. Dysthymia treatment needs continuous support for persistent low-mood states. It reflects strong clinical reliance on sustained medication use across varied psychiatric needs.
- For instance, Janssen’s esketamine achieved a 50% reduction in depressive symptoms in treatment-resistant MDD patients during Phase III trials.
By Route of Administration
Oral drugs dominate use due to ease of dosing and strong patient adherence. Injectable formats support severe episodes requiring controlled administration. Nasal formulations gain attention for fast-acting relief in acute cases. Transdermal patches offer alternative delivery for patients with swallowing or tolerability issues. It reflects strong clinical demand for varied administration routes that support personalized care within the Antidepressants Market.
- For instance, esketamine nasal spray reduced depressive symptoms within two hours in emergency-setting evaluations.
By Distribution Channels
Hospital pharmacies manage acute episodes and severe psychiatric cases requiring structured oversight. Retail pharmacies handle most long-term prescriptions across urban and semi-urban regions. Online pharmacies expand access for patients seeking privacy and convenience. It supports growing engagement across digital platforms and strengthens continuity of medication supply.
Segmentation:
By Drug Class
- Selective Serotonin Reuptake Inhibitors (SSRIs)
- Serotonin-Norepinephrine Reuptake Inhibitors (SNRIs)
- Tricyclic Antidepressants (TCAs)
- Monoamine Oxidase Inhibitors (MAOIs)
- Atypical Antidepressants
- NDRIs
- Serotonin Antagonists
By Application
- Major Depressive Disorder (MDD)
- Generalized Anxiety Disorder
- Obsessive-Compulsive Disorder (OCD)
- Panic Disorder
- ADHD
- Dysthymia
By Route of Administration
- Oral
- Injectable
- Nasal
- Transdermal
By Distribution Channels
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America holds the largest share of the Antidepressants Market due to strong mental health awareness and advanced healthcare systems. The region benefits from high diagnosis rates and steady adoption of new drug classes. Providers offer structured care supported by large psychiatric networks. It gains strength from broad insurance coverage and strong research pipelines. Pharmaceutical companies introduce innovative therapies first in this region. North America maintains its lead through continued investment in mental health infrastructure.
Europe follows with a substantial market share driven by established reimbursement systems and strong regulatory frameworks. Countries in Western Europe emphasize long-term treatment, which supports high prescription volumes. Providers integrate digital mental health tools to improve adherence. It gains momentum from strong government support for mental health programs. Eastern Europe expands access through growing healthcare investments. Europe strengthens its position through improved treatment guidelines and broad medication availability.
Asia Pacific records the fastest growth and secures a rising share due to expanding patient awareness and large population bases. Urban centers show strong demand for structured psychiatric care. Healthcare systems invest in training programs and digital consultation platforms. It benefits from private sector expansion and wider pharmacy networks. Emerging economies focus on reducing mental health stigma through public campaigns. Asia Pacific continues to build a stronger role within the Antidepressants Market as access improves across diverse regions.
Key Player Analysis:
- Pfizer Inc.
- Eli Lilly and Company
- Johnson & Johnson
- AbbVie Inc.
- Novartis AG
- GlaxoSmithKline PLC
- AstraZeneca
- Sanofi
- Sun Pharmaceutical Industries Ltd.
- Merck & Co. Inc.
- Teva Pharmaceutical Industries Ltd.
Competitive Analysis:
The Antidepressants Market features strong competition among global pharmaceutical companies focused on innovation, product expansion, and safety improvements. Leading firms invest in new drug classes with better tolerability and faster onset of action. Companies strengthen portfolios through lifecycle management and targeted launches across high-burden regions. It drives competitive intensity by pushing rapid development of atypical antidepressants and novel receptor modulators. Firms expand digital support programs to improve adherence and patient engagement. Generic manufacturers gain share through cost-effective products that appeal to broader populations. Market consolidation trends appear through strategic partnerships, co-development agreements, and acquisitions aimed at pipeline expansion. Competitive strength continues to rise as companies align research priorities with unmet clinical needs.
Recent Developments:
- In August 2025, AbbVie Inc. announced the acquisition of Gilgamesh Pharmaceuticals' bretisilocin, a novel investigational therapy for moderate-to-severe major depressive disorder (MDD), completing the deal in October 2025 to expand psychiatric care options.
- In January 2025, Johnson & Johnson strengthened its neuroscience portfolio with the acquisition of Intra-Cellular Therapies gaining CAPLYTA (lumateperone), approved for bipolar depression and with a pending sNDA for major depressive disorder as adjunctive therapy.
Report Coverage:
The research report offers an in-depth analysis based on Drug Class, Application, Route of Administration, Medication Type, and Distribution Channels. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand will grow as awareness programs expand and more patients seek structured mental health support.
- New drug classes with faster onset will strengthen treatment outcomes and raise adoption.
- Digital tools will support personalized care paths and improve adherence across patient groups.
- Telemedicine expansion will widen access and drive stronger prescription volumes in remote regions.
- Novel mechanisms for treatment-resistant cases will reshape clinical decision-making.
- Hybrid therapy models combining medication and digital interventions will gain wider use.
- More companies will invest in rapid-relief agents to support high-severity episodes.
- Generic penetration will rise in price-sensitive markets, enhancing treatment access.
- Precision medicine tools will guide therapy selection and reduce discontinuation rates.
- Global health systems will prioritize mental health, strengthening long-term growth for the Antidepressants Market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Antidepressants Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Antidepressants Market projected to grow between 2024 and 2032?
Which Antidepressants Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Antidepressants Market?
Who are the leading companies in the Antidepressants Market?
Which region commanded the largest share of the Antidepressants Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Antidepressants Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Antidepressants Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 20,875.68 million → 2032: USD 33,982.32 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Antidepressants Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Antidepressants Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Antidepressants Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Antidepressants Market Drivers
- 3.3 Antidepressants Market Restraints & Challenges
- 3.4 Antidepressants Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Antidepressants Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Antidepressants Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Antidepressants category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Antidepressants Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Antidepressants Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Antidepressants market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Antidepressants Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Antidepressants Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Antidepressants Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Antidepressants (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Antidepressants Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Antidepressants Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Antidepressants Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Antidepressants Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Antidepressants Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Antidepressants Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Antidepressants Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Antidepressants Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Antidepressants Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
