
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Aortic Stent Grafts Market Size 2023 | USD 3,289.5 Million |
| Aortic Stent Grafts Market, CAGR | 5.30% |
| Aortic Stent Grafts Market Size 2032 | USD 4,972.29 Million |
Market Overview
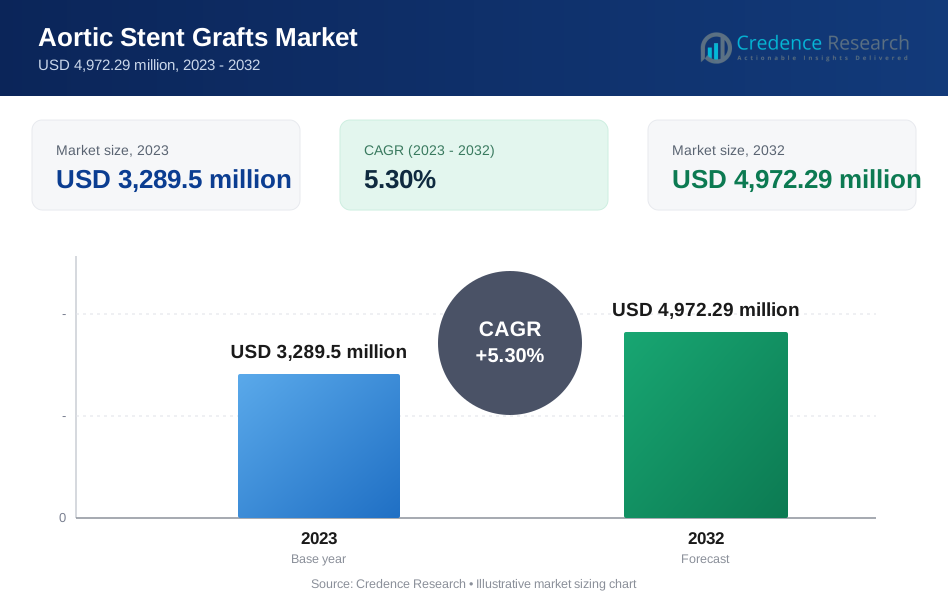
The Aortic Stent Grafts Market is projected to grow from USD 3,289.5 million in 2023 to an estimated USD 4,972.29 million by 2032, with a compound annual growth rate (CAGR) of 5.30% from 2024 to 2032. This growth is driven by an increase in the prevalence of aortic aneurysms and advancements in stent graft technology that enhance patient outcomes and minimize risks associated with traditional open surgeries.
Key drivers for this market include an aging population, rising incidences of cardiovascular diseases, and a shift toward minimally invasive surgical procedures. Advances in imaging technology and the development of customized stent grafts tailored to individual patient anatomy further contribute to market growth. Additionally, increased healthcare spending and favorable reimbursement policies in developed economies are also expected to bolster market demand for aortic stent grafts.
Geographically, North America holds a significant share of the aortic stent grafts market, driven by high healthcare expenditure, advanced medical infrastructure, and the presence of key market players. Europe follows closely, benefiting from increased awareness and a growing elderly population. Meanwhile, the Asia-Pacific region is anticipated to experience the fastest growth due to rising healthcare investments and improved access to healthcare services. Prominent players in this market include Medtronic, Cook Medical, Terumo Corporation, Endologix LLC, and Abbott Laboratories, which continue to innovate and expand their product portfolios to meet the growing demand.
Market Drivers
Rising Incidence of Aortic Aneurysms and Cardiovascular Diseases
The global burden of aortic aneurysms is on the rise, largely driven by an aging population and an increase in lifestyle-related risk factors, such as hypertension, smoking, and obesity. Aortic aneurysms, particularly abdominal aortic aneurysms (AAA), are more prevalent among older adults, and as the global population continues to age, the need for effective treatment options is growing. Traditional open surgeries for aortic aneurysms come with high risks, longer recovery times, and extended hospital stays. Aortic stent grafts, on the other hand, offer a minimally invasive solution with reduced procedural risks and shorter recovery periods, making them a preferred choice for both patients and healthcare providers. For instance, aortic abdominal aneurysm (AAA) is a multifactorial vascular disease with high mortality, estimated to cause 200,000 deaths per year worldwide. The growing incidence of cardiovascular diseases further amplifies this demand, positioning aortic stent grafts as a vital component in modern vascular care.
Technological Advancements in Aortic Stent Grafts
Innovations in medical technology have significantly transformed the aortic stent grafts market, making treatments more effective and accessible. The development of new materials has led to enhanced durability and flexibility of stent grafts, enabling them to conform better to the patient’s anatomy and minimize risks of endoleaks. Additionally, advanced imaging technologies have improved the accuracy of graft placements, enhancing the overall effectiveness of endovascular aneurysm repair (EVAR) and thoracic endovascular aneurysm repair (TEVAR) procedures. For instance, the use of 4D-printing technology in stent-grafts allows for adaptive functionality, enabling the implants to physically transform over time to perform programmed tasks. Customizable and patient-specific stent grafts are now available, allowing healthcare providers to tailor solutions to the unique anatomical needs of individual patients. This customization not only improves patient outcomes but also drives demand as physicians seek more reliable and effective treatment options. The continued focus on research and development by key industry players is expected to further propel technological advancements, making these devices more adaptable to complex cases.
Increasing Preference for Minimally Invasive Procedures
There is a growing shift in the healthcare industry toward minimally invasive procedures, driven by both patient demand and healthcare provider interest in reducing procedural risks and improving recovery times. Aortic stent grafts represent a less invasive alternative to traditional open surgical repairs, which often require larger incisions, prolonged hospitalization, and lengthy recovery periods. Minimally invasive procedures, like EVAR and TEVAR, are associated with fewer complications, shorter hospital stays, and faster recovery, which appeal to patients seeking quicker returns to normal activities. Moreover, minimally invasive approaches are often less costly in terms of post-operative care, providing a significant economic advantage for healthcare providers and insurance companies. As healthcare systems continue to prioritize value-based care, the preference for minimally invasive treatment options, including aortic stent grafts, is expected to strengthen and drive market growth.
Increasing Healthcare Expenditure and Favorable Reimbursement Policies
Rising healthcare expenditure across both developed and emerging economies is a critical driver for the aortic stent grafts market. Governments and private organizations are investing more in advanced medical technologies to improve patient outcomes and address the growing burden of chronic diseases. This increase in healthcare spending is creating greater access to innovative medical procedures, including endovascular aneurysm repairs utilizing stent grafts. Additionally, in regions like North America and parts of Europe, favorable reimbursement policies support the adoption of these procedures by offsetting the high costs associated with the devices and their implantation. Coverage and reimbursement for EVAR and TEVAR procedures have been improving as payers recognize the long-term cost savings associated with minimally invasive treatments compared to traditional open surgery. As a result, more patients can afford these procedures, and hospitals are encouraged to adopt advanced stent graft technologies, further boosting market demand.
Market Trends
Development of Patient-Specific and Customized Stent Grafts
One of the most significant trends in the aortic stent grafts market is the shift toward patient-specific and customized stent graft solutions. Traditional “one-size-fits-all” stent grafts often fail to accommodate the unique anatomical variations seen in individual patients, which can lead to complications such as endoleaks and graft migration. In response, manufacturers are investing in advanced imaging and 3D modeling technologies to design stent grafts that precisely match a patient’s vascular anatomy. For instance, a study demonstrated that using patient-specific virtual stent-graft deployment for type B aortic dissection can predict post-TEVAR stent-graft configuration and wall stress, helping to select the most appropriate stent-graft length for individual patients. This trend is further driven by a rise in complex cases that require highly customized solutions, such as those involving tortuous or highly calcified aortas. Customized stent grafts not only improve clinical outcomes but also reduce the likelihood of secondary procedures, enhancing the overall efficiency of vascular care. As research and development continue to progress, the customization trend is expected to make aortic stent grafts more adaptable and accessible, meeting a broader range of patient needs.
Growing Adoption of Hybrid Procedures in Aortic Repair
Another trend gaining traction in the aortic stent grafts market is the adoption of hybrid procedures that combine open surgery with endovascular techniques. Hybrid procedures are increasingly used for treating complex aortic aneurysms, particularly in cases where an entirely endovascular approach is not feasible due to anatomical challenges or other patient-specific factors. For example, hybrid techniques can be applied to thoracoabdominal aneurysms, allowing surgeons to perform bypass grafting alongside the placement of stent grafts. This approach minimizes the invasiveness of traditional open surgery while providing the advantages of endovascular repair. Hospitals and medical centers are investing in hybrid operating rooms, equipped with advanced imaging systems that facilitate these procedures. The hybrid approach is particularly appealing for high-risk patients who may not be candidates for extensive open surgeries, enabling aortic stent grafts to be used in a wider range of clinical scenarios. For instance, a study found that 33.9% of patients undergoing aortic arch surgery between June 2004 and June 2021 were treated using hybrid procedures due to high surgical risk. As this trend continues, the demand for stent grafts compatible with hybrid techniques is expected to rise, driving further innovation in the market.
Market Restraints and Challenges
High Costs and Limited Reimbursement in Emerging Markets
One of the primary restraints facing the aortic stent grafts market is the high cost associated with these devices and the limited reimbursement options available in emerging markets. Aortic stent graft procedures, particularly those involving advanced and customized grafts, can be costly, encompassing not only the device itself but also hospital stay, surgical fees, and follow-up care. While reimbursement policies in regions such as North America and Europe are more favorable, many developing countries struggle with limited healthcare budgets and lack comprehensive insurance coverage for these procedures. This financial barrier can restrict access to aortic stent grafts, particularly in lower-income populations. Additionally, hospitals in emerging markets may lack the necessary infrastructure and skilled personnel to perform such procedures, further limiting adoption. Addressing cost challenges, especially through strategic pricing and reimbursement support, will be crucial for expanding the market reach in these regions.
Complications and Long-Term Durability Concerns
Another significant challenge in the aortic stent grafts market relates to complications such as endoleaks, graft migration, and device failure, which can necessitate secondary interventions and impact long-term patient outcomes. While stent graft technology has advanced, ensuring long-term durability remains a concern. Complications can occur due to improper placement, anatomical mismatches, or wear and tear of the device over time. In some cases, secondary procedures may be required to address these issues, which adds to patient risk and increases healthcare costs. Moreover, healthcare providers may hesitate to adopt certain stent grafts if they lack sufficient long-term clinical data. As such, manufacturers are under pressure to improve device durability, minimize complications, and provide more extensive data on long-term performance. This ongoing need for enhanced product reliability and extensive post-market surveillance continues to challenge the growth potential of the aortic stent grafts market.
Market Segmentation Analysis
By Product Type
The abdominal aortic stent graft segment commands a significant share of the aortic stent grafts market due to the high prevalence of abdominal aortic aneurysms (AAA) worldwide. Abdominal aortic stent grafts, primarily used in Endovascular Aneurysm Repair (EVAR) procedures, have gained popularity as a minimally invasive alternative to traditional open surgeries. The rising incidence of lifestyle diseases, such as hypertension and smoking-related vascular damage, has led to increased demand for AAA treatments. Technological advancements, including bifurcated and fenestrated stent grafts, have further enhanced the precision and safety of these devices, supporting steady growth in this segment. Meanwhile, the thoracic aortic stent graft segment is experiencing notable growth due to the rising number of Thoracic Endovascular Aneurysm Repair (TEVAR) procedures, which provide a minimally invasive solution for the treatment of thoracic aortic aneurysms. Although less common than AAA, thoracic aneurysms are highly dangerous and require prompt intervention, often unsuitable for open surgery, especially in older patients or those with other risk factors. Innovations such as branched and multi-lumen stent grafts have made TEVAR procedures safer and more adaptable for complex thoracic anatomies. As the aging population grows and awareness of thoracic aortic aneurysm risks increases, demand for thoracic aortic stent grafts is expected to continue expanding.
By End use
Hospitals are the primary end users of aortic stent grafts, holding the largest market share due to their ability to provide comprehensive care, advanced diagnostic imaging, and access to skilled vascular surgeons and interventional radiologists. Equipped with hybrid operating rooms and cutting-edge imaging technologies essential for procedures like EVAR and TEVAR, hospitals are well-positioned to handle complex cases and are generally more accessible to insured patients, further driving demand. In contrast, ambulatory surgical centers (ASCs) are gaining traction for their cost-effective and efficient care models, particularly suited for less complex EVAR procedures that allow same-day discharge. ASCs appeal to patients and insurers due to lower overhead costs and shorter hospital stays, though they may be limited in scope by infrastructure needs. Despite these constraints, ASCs are expected to see increased adoption of aortic stent graft procedures as healthcare shifts toward outpatient settings, especially for healthier patients with fewer comorbidities.
Segments
Based on Product Type
- Abdominal Aortic Stent Graft
- Thoracic Aortic Stent Graft.
Based on End User
- Hospitals
- Ambulatory Surgical Centers/Outpatient Surgical Centers.
Based on Region
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
Regional Analysis
North America (40%),
North America holds the largest share of the aortic stent grafts market, accounting for approximately 40% of the global market. This dominance is driven by several factors, including a well-established healthcare infrastructure, high healthcare spending, and a significant prevalence of cardiovascular diseases, including aortic aneurysms. The United States, in particular, leads the region due to its advanced healthcare facilities, skilled professionals, and strong focus on minimally invasive procedures. Favorable reimbursement policies also support the widespread adoption of aortic stent grafts in this region. Additionally, a large number of key players, such as Medtronic and Cook Medical, have headquarters or significant operations in North America, further contributing to market growth through ongoing research and product innovation.
Europe (30%),
Europe represents approximately 30% of the global aortic stent grafts market, making it the second-largest regional market. This market share is primarily attributed to the growing elderly population and increased awareness of aortic aneurysm risks. Countries like Germany, France, and the United Kingdom are key contributors, driven by advanced healthcare systems and rising demand for minimally invasive solutions. The European market benefits from regulatory support and established reimbursement frameworks for aortic stent graft procedures, which facilitate wider adoption in the region. Ongoing research and collaborations between healthcare providers and manufacturers have also accelerated the development of innovative technologies in Europe, including patient-specific and customized stent graft solutions tailored to complex anatomical needs.
Key players
- Medtronic Plc
- Cook Medical Inc.
- Endologix Inc.
- L. Gore & Associates Inc.
- Terumo Corporation
- Lombard Medical Technologies
- MicroPort Scientific Corporation
- Merit Medical Systems Inc.
- JOTEC GmbH
- CryoLife Inc.
- Lifetech Scientific (Shenzhen) Co. Ltd.
- Becton, Dickinson and Company
- Endospan Ltd.
- Cardinal Health Inc.
- MicroVention Inc.
- Aptus Endosystems Inc.
- Altura Medical Inc.
- Penumbra Inc.
- Biomerics LLC
- Lombardi SA
Competitive Analysis
The aortic stent grafts market is highly competitive, with leading companies focusing on innovation, strategic partnerships, and geographical expansion to strengthen their market positions. Medtronic Plc, Cook Medical, and W.L. Gore & Associates dominate due to their extensive product portfolios, research and development capabilities, and established market presence. Emerging players like MicroPort Scientific and Lifetech Scientific are gaining traction, particularly in the Asia-Pacific region, by offering cost-effective solutions tailored to local market needs. Many competitors are prioritizing the development of customized stent grafts and leveraging advanced imaging technology to improve patient outcomes. Additionally, strategic acquisitions and collaborations are becoming common as companies seek to expand their product lines and enhance their distribution networks globally. This competitive landscape, marked by continuous innovation and strategic alliances, is expected to drive further advancements in the aortic stent grafts market.
Recent Developments
- In March 2024, Medtronic announced FDA approval of the Evolut FX+ transcatheter aortic valve replacement (TAVR) system for the treatment of symptomatic severe aortic stenosis.
- In January 2024, Gore received FDA approval for the GORE EXCLUDER Thoracoabdominal Branch Endoprosthesis (TAMBE), the first off-the-shelf endovascular solution for the treatment of complex aneurysmal disease involving the visceral aorta.
- In May 2023, Terumo Aortic announced FDA approval of the RelayPro Thoracic Stent-Graft device for the treatment of dissection and transection in the United States.
- In April 2024, MicroPort Endovastec’s Hector Multi-Branch Thoracic Aortic Stent-Graft completed its first clinical implantation in Switzerland.
Market Concentration and Characteristics
The aortic stent grafts market is moderately concentrated, with a few key players, such as Medtronic Plc, Cook Medical, and W.L. Gore & Associates, holding significant market shares due to their established product portfolios, advanced technologies, and strong global distribution networks. These leading companies are characterized by robust research and development efforts, which enable them to introduce innovative solutions tailored to the evolving needs of patients and healthcare providers. The market also features smaller and emerging players, especially in the Asia-Pacific region, who offer cost-effective and region-specific products to meet local demand. Market characteristics include a strong focus on technological advancements, particularly in patient-specific and minimally invasive stent grafts, as well as strategic mergers, acquisitions, and partnerships aimed at expanding product lines and enhancing global reach. Additionally, the market is driven by an aging population, a rise in cardiovascular disease prevalence, and a shift toward minimally invasive procedures, which collectively support steady growth and increased competition.
Report Coverage
The research report offers an in-depth analysis based on Product Type, End User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Innovations in stent graft materials and designs are expected to improve durability, flexibility, and patient outcomes, supporting wider adoption of aortic stent grafts globally.
- The demand for customized stent grafts tailored to individual patient anatomies is projected to grow, enhancing treatment precision and reducing complication rates.
- Increased healthcare spending and improving infrastructure in emerging markets, especially in Asia-Pacific and Latin America, will drive significant market growth in these regions.
- As healthcare providers prioritize less invasive approaches, the demand for aortic stent grafts used in EVAR and TEVAR procedures is expected to rise, reducing recovery times for patients.
- The adoption of hybrid procedures combining open and endovascular approaches will expand the application of stent grafts in complex cases, increasing their overall usage.
- Advances in imaging technologies will facilitate more accurate graft placements, resulting in fewer complications and improved long-term results for patients undergoing aortic repairs.
- As regulatory bodies emphasize long-term device safety, manufacturers will continue investing in post-market surveillance to monitor and improve the durability of stent grafts.
- Key players are likely to pursue partnerships and acquisitions to expand their product offerings and geographic reach, fostering innovation and market consolidation.
- Expanding reimbursement policies for minimally invasive procedures in regions such as North America and Europe will support broader patient access to aortic stent grafts.
- Increased awareness of aortic aneurysms and advancements in diagnostic methods will lead to earlier diagnoses, expanding the eligible patient pool for aortic stent graft procedures.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size for the Aortic Stent Grafts Market in 2023 and 2032, and what is its CAGR?
What are the main drivers of growth in the Aortic Stent Grafts Market?
Which regions hold the largest market share for aortic stent grafts?
How do aortic stent grafts improve patient outcomes?
Why is there a growing preference for minimally invasive procedures like EVAR and TEVAR?
What role do technological advancements play in the Aortic Stent Grafts Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Aortic Stent Grafts Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Aortic Stent Grafts Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 3,289.5 million → 2032: USD 4,972.29 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Aortic Stent Grafts Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Aortic Stent Grafts Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Aortic Stent Grafts Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Aortic Stent Grafts Market Drivers
- 3.3 Aortic Stent Grafts Market Restraints & Challenges
- 3.4 Aortic Stent Grafts Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Aortic Stent Grafts Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Aortic Stent Grafts Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Aortic Stent Grafts category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Aortic Stent Grafts Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Aortic Stent Grafts Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Aortic Stent Grafts market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Aortic Stent Grafts Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Aortic Stent Grafts Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Aortic Stent Grafts Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Aortic Stent Grafts (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Aortic Stent Grafts Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Aortic Stent Grafts Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Aortic Stent Grafts Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Aortic Stent Grafts Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Aortic Stent Grafts Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Aortic Stent Grafts Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Aortic Stent Grafts Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Aortic Stent Grafts Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Aortic Stent Grafts Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
