
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| App Analytics Market Size 2024 | USD 2,692.42 million |
| App Analytics Market, CAGR | 18.39% |
| App Analytics Market Size 2032 | USD 11,366.06 million |
Market Overview:
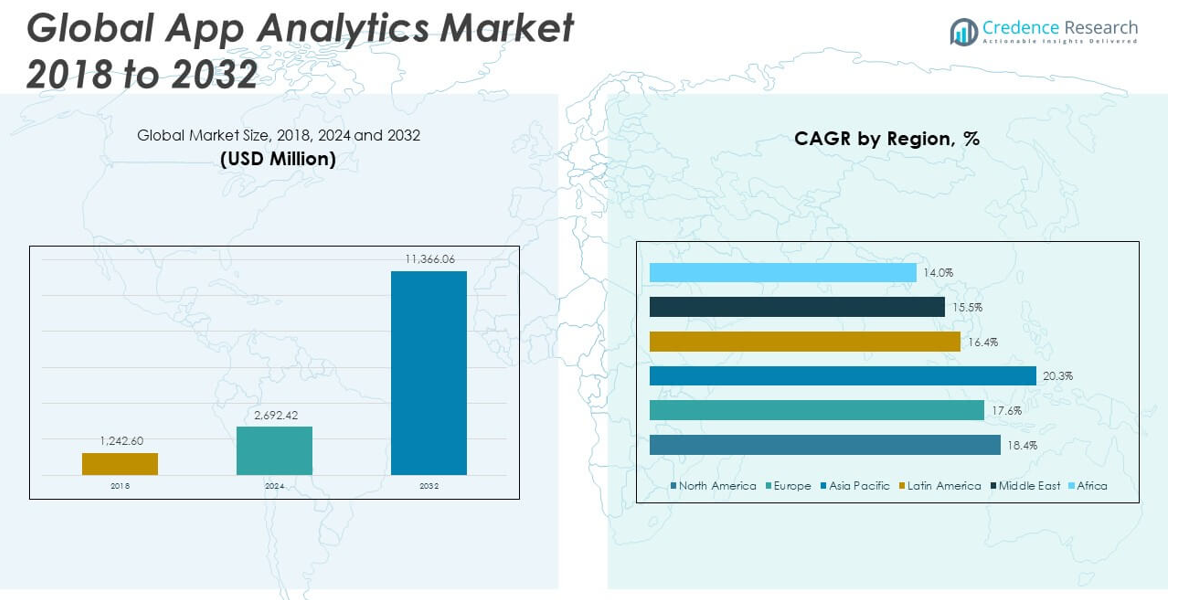
The Global App Analytics Market size was valued at USD 1,242.60 million in 2018 to USD 2,692.42 million in 2024 and is anticipated to reach USD 11,366.06 million by 2032, at a CAGR of 18.39% during the forecast period.
Several key factors are propelling the expansion of the app analytics market. The proliferation of smartphones and the growing number of mobile applications have led to a massive increase in user data, necessitating advanced analytics platforms to interpret this information effectively. Additionally, the integration of artificial intelligence (AI) and machine learning (ML) technologies in app analytics tools is enabling businesses to gain deeper insights into user behavior and predict future trends. The growing demand for personalized user experiences and the increasing need for real-time data analysis further contribute to the market's growth. Moreover, the rising emphasis on data privacy and security is pushing businesses to adopt more advanced analytics tools to comply with global data protection regulations, ensuring the safety and privacy of user information.
The app analytics market shows varying growth trends across regions. North America currently holds the largest market share, driven by its advanced technological infrastructure, high smartphone penetration, and the presence of leading tech companies investing heavily in app analytics solutions. Europe also represents a significant portion of the market, with countries such as the United Kingdom, Germany, and France leading in adoption rates, particularly in the retail, banking, and telecom sectors. The Asia-Pacific region is expected to experience the fastest growth, fueled by the increasing smartphone penetration, a rapidly growing middle class, and a burgeoning startup ecosystem in countries like China, India, and Japan. Additionally, regions such as Latin America and the Middle East are beginning to see a rise in investments and digital transformation, which are driving the adoption of mobile analytics platforms as businesses in these areas increasingly seek data-driven solutions.
Market Insights:
- The global app analytics market was valued at USD 1,242.60 million in 2018 and is projected to reach USD 11,366.06 million by 2032, growing at a CAGR of 18.39% during the forecast period.
- The proliferation of smartphones and mobile apps is driving a significant increase in user data, prompting businesses to adopt advanced analytics tools to optimize app performance and enhance user engagement.
- Artificial intelligence (AI) and machine learning (ML) integration are revolutionizing the app analytics landscape by providing deeper insights into user behavior and enabling more accurate segmentation.
- Real-time data analysis is becoming essential for businesses to respond swiftly to user interactions and provide personalized experiences, contributing to higher customer satisfaction and retention.
- Data privacy regulations like GDPR and CCPA are encouraging the development of secure app analytics tools that help businesses ensure compliance while offering actionable insights.
- North America leads the app analytics market, driven by high smartphone penetration, strong technological infrastructure, and significant investments in analytics solutions.
- The Asia Pacific region is expected to experience the highest growth due to increasing smartphone usage, a growing middle class, and the rise of startups in countries like China, India, and Japan.
Market Drivers:
Proliferation of Mobile Apps and User Data
The rapid increase in mobile app usage across various sectors is a significant driver of the global app analytics market. Businesses are investing heavily in mobile app development to enhance customer engagement, streamline operations, and deliver personalized experiences. This growing app usage has led to a surge in data generation, making it essential for companies to adopt advanced app analytics tools. By leveraging these tools, businesses can efficiently process and analyze vast amounts of user data, enabling data-driven decisions that improve app functionality and user retention. The demand for these solutions is expected to rise as more organizations seek to optimize their apps and stay competitive in an increasingly digital landscape.
Advancements in Artificial Intelligence and Machine Learning Integration
The integration of artificial intelligence (AI) and machine learning (ML) technologies into app analytics platforms is revolutionizing how businesses analyze user behavior. These technologies enable companies to gain deeper insights into how users interact with apps, predict future behavior, and identify potential issues before they affect performance. AI and ML also enhance the ability to segment users more accurately, allowing businesses to target specific user groups with tailored content and features. The application of AI-driven analytics helps organizations enhance app performance, optimize user experience, and drive higher engagement levels. As these technologies continue to evolve, their impact on the global app analytics market will likely intensify, further accelerating market growth.
- For example, Quantum Metric’s platform utilizes AI to correlate engagement, crashes, and API performance with business outcomes, supporting rapid iteration cycles some clients report new app releases every 4 to 6 weekswith measurable impact analysis in real time.
Increasing Demand for Real-Time Data Analysis and Personalization
The growing demand for personalized user experiences is another key factor propelling the global app analytics market. Users expect apps to adapt to their preferences, delivering customized content and features. Achieving this level of personalization requires businesses to analyze user behavior in real-time, making real-time data analysis a critical component of app optimization. App analytics platforms enable businesses to track user interactions instantaneously, providing them with the data needed to make informed decisions quickly. This ability to respond rapidly to user needs ensures higher satisfaction rates and improved retention, pushing companies to invest in analytics tools to stay ahead in the competitive mobile app market.
Focus on Data Privacy and Compliance with Regulations
As data privacy concerns become more prevalent, businesses are under increasing pressure to protect user information while complying with data protection regulations. The implementation of laws such as the General Data Protection Regulation (GDPR) in Europe has made it necessary for businesses to ensure that their data collection practices are transparent and secure. In response, app analytics platforms are incorporating features that help organizations meet these regulatory requirements, ensuring user data is handled responsibly and ethically. This growing focus on data security and compliance further drives the adoption of advanced app analytics solutions, as companies seek tools that not only provide insights but also protect their users' privacy.
- For instance, companies such as Piwik offer on-premise analytics solutions, ensuring data never leaves the organization’s infrastructure, while others employ homomorphic encryptionand blockchain-based consent management to enhance security and transparency.
Market Trends:
Shift Towards Cloud-Based App Analytics Solutions
The global app analytics market is witnessing a shift towards cloud-based solutions due to their flexibility, scalability, and cost-effectiveness. Cloud platforms allow businesses to access analytics tools without investing in expensive on-premise infrastructure, making these solutions more accessible to a wider range of organizations, from small startups to large enterprises. Cloud-based app analytics tools also offer real-time data processing capabilities, which is essential for businesses aiming to enhance user experience and app performance. This trend is expected to grow as more companies adopt cloud technology, integrating app analytics into their digital transformation strategies for better operational efficiency and reduced overhead costs.
- For instance, Domo’s cloud analytics platformenables organizations to integrate data from over 1,000 sources and provides live KPI tracking with automated insights and anomaly detection, all within a single, scalable dashboard.
Integration of Multi-Platform App Analytics
The growing use of multiple platforms such as smartphones, tablets, wearables, and smart TVs has led to a trend of integrating app analytics across various devices. Businesses are now adopting app analytics tools that provide cross-platform insights, enabling them to monitor user behavior and performance across different channels. This integration helps businesses gain a holistic view of their users' interactions and engagement, regardless of the platform they are using. The ability to track and analyze data from multiple devices helps companies optimize their apps for different environments and enhance their marketing strategies, thereby fostering better customer engagement and retention in the global app analytics market.
Focus on Predictive Analytics for Proactive Decision-Making
Predictive analytics is becoming an essential tool in the global app analytics market as businesses increasingly look to anticipate future trends and behaviors. By analyzing historical data, businesses can forecast future user actions, app performance, and market conditions, allowing them to make proactive, data-driven decisions. This trend is particularly important for user acquisition and retention strategies, as companies can adjust their marketing campaigns and app features based on predicted user behavior. Predictive analytics enhances the ability to identify high-value customers and optimize customer journeys, making it a key feature of modern app analytics platforms.
- For instance, Adaptyemploys a predictive analytics model powered by gradient boosting algorithms trained on millions of anonymized in-app transactions. Once integrated, Adapty’s model learns from the app’s own transactional data to deliver highly accurate forecasts of subscriber.
Rise in Adoption of Mobile App Optimization Techniques
The rise in app usage across different sectors has led to a growing trend towards mobile app optimization. Businesses are focusing on improving the performance, speed, and usability of their apps to maintain user interest and increase retention rates. App analytics tools that provide insights into app crashes, load times, and user flows are becoming crucial in identifying areas for improvement. By leveraging these tools, businesses can ensure that their apps function smoothly and offer an optimal user experience. The emphasis on mobile app optimization aligns with the increasing reliance on mobile platforms for consumer engagement, driving the demand for app analytics solutions.
Market Challenges Analysis:
Data Privacy and Compliance Challenges in the Global App Analytics Market
Data privacy concerns present a significant challenge in the global app analytics market. With the implementation of stricter data protection regulations such as GDPR and CCPA, businesses must ensure that their app analytics tools comply with these standards. The complexity of adhering to these regulations can hinder the adoption of app analytics solutions, as organizations must balance the need for detailed user insights with the protection of user data. Non-compliance can result in hefty fines and damage to a company’s reputation, making businesses cautious in adopting analytics tools that require the collection and processing of personal data. Ensuring that app analytics solutions meet privacy requirements while still offering valuable insights is a critical challenge facing market players.
Integration and Compatibility Issues with Existing Systems
Another challenge in the global app analytics market is the integration of analytics tools with existing systems. Many businesses already have established infrastructure for app development, customer relationship management (CRM), and other key functions. Integrating app analytics with these systems can be technically complex and time-consuming, especially for companies with legacy systems. Compatibility issues may arise between different software and data sources, leading to inefficiencies and potential errors in data analysis. Companies must invest in robust solutions that seamlessly integrate with their current platforms, which can increase operational costs and delay the deployment of app analytics solutions. Ensuring smooth integration across multiple systems is essential for businesses aiming to leverage app analytics effectively.
Market Opportunities:
Growing Demand for Personalization and Customer-Centric Strategies in the Global App Analytics Market
The global app analytics market presents significant opportunities driven by the growing demand for personalization and customer-centric strategies. Businesses across various sectors are increasingly prioritizing personalized experiences to engage users more effectively. App analytics tools that offer in-depth insights into user behavior allow companies to tailor their offerings, enhancing customer satisfaction and loyalty. By leveraging data to customize content, features, and recommendations, businesses can optimize user interactions and drive higher retention rates. The opportunity lies in providing more advanced analytics solutions that enable businesses to create targeted strategies based on individual user preferences, making personalized app experiences a key growth driver in the market.
Expanding Adoption of Cloud Solutions and AI in App Analytics
Another promising opportunity in the global app analytics market lies in the expanding adoption of cloud-based solutions and artificial intelligence (AI) technologies. Cloud platforms offer scalability and flexibility that appeal to businesses of all sizes, enabling them to access powerful analytics tools without heavy upfront investments in infrastructure. The integration of AI enhances the accuracy and efficiency of data analysis, allowing businesses to gain deeper insights and make data-driven decisions more effectively. As more companies move toward digital transformation and embrace AI-powered analytics, the market will see increased demand for solutions that provide real-time insights and predictive capabilities, creating new growth opportunities for providers in the app analytics space.
Market Segmentation Analysis:
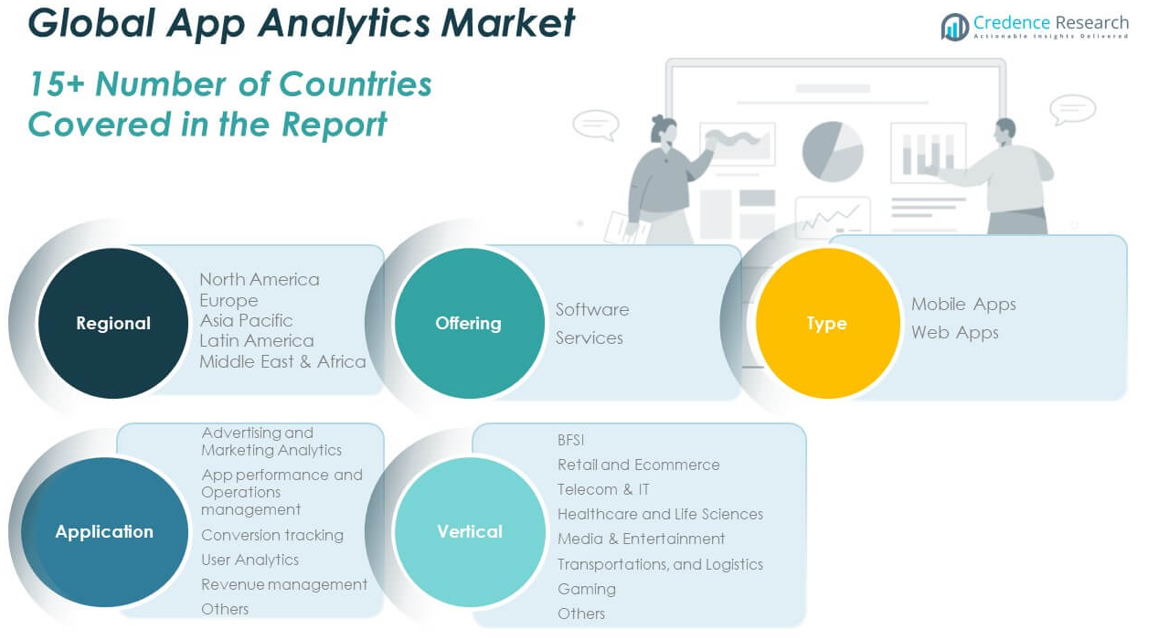
The global app analytics market is segmented across several dimensions, each contributing to its growth.
By offering segment includes software and services, with software solutions leading due to their scalability and automation capabilities, while services focus on consulting, implementation, and support.
- For instance, Userpilot’s software solution enables product and growth teams to autocapture user actions on web and event-based tracking for mobile, all with a no-code setup. This platform supports session replays, custom analytics reports, and centralized dashboards that track retention, feature adoption, and conversion trends, as evidenced by a G2 rating of 4.6/5 from over 700 verified reviews.
By type segment includes mobile apps and web apps, with mobile apps dominating as businesses increasingly prioritize mobile-first strategies to engage users.
By application segment covers various functions including advertising and marketing analytics, which enable targeted campaigns, app performance and operations management for optimizing user experience, and conversion tracking to measure campaign effectiveness. User analytics helps in understanding behavior patterns, while revenue management optimizes pricing and sales strategies. Other applications focus on more niche areas, such as app security and fraud detection.
- For instance, Branch’s event-based analytics and deep linking technology have enabled companies like Payoneer to increase app engagement, with 46% of Payoneer consumers actively using the app, up from 33% in 2020, and 204,000 installs attributed to Branch’s Journeys smart banners in a single year.
By vertical segment highlights the broad applicability of app analytics across industries. BFSI utilizes app analytics for financial services, while retail and ecommerce focus on customer engagement and conversion optimization. Telecom & IT uses app performance insights to maintain network efficiency, and healthcare leverages analytics for patient engagement and service optimization. Media & entertainment, transportation and logistics, and gaming sectors use app analytics to improve user experience and content delivery.
Segmentation:
By Offering:
- Software
- Services
By Type:
- Mobile Apps
- Web Apps
By Application:
- Advertising and Marketing Analytics
- App Performance and Operations Management
- Conversion Tracking
- User Analytics
- Revenue Management
- Others
By Vertical:
- BFSI (Banking, Financial Services, and Insurance)
- Retail and Ecommerce
- Telecom & IT
- Healthcare and Life Sciences
- Media & Entertainment
- Transportation and Logistics
- Gaming
- Others
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America App Analytics Market
The North America App Analytics Market size was valued at USD 523.43 million in 2018, projected to reach USD 1,121.93 million in 2024, and anticipated to grow to USD 4,749.87 million by 2032, at a CAGR of 18.4% during the forecast period. North America holds the largest market share in the global app analytics market. The rapid adoption of advanced technologies, a strong presence of leading tech companies, and high smartphone penetration contribute to the region’s dominance. The increasing need for businesses to optimize mobile app performance and provide personalized user experiences drives demand for app analytics solutions. Companies in North America are heavily investing in cloud-based analytics platforms and artificial intelligence to enhance data-driven decision-making. The region’s robust technological infrastructure and the growing emphasis on data privacy regulations further boost market growth.
Europe App Analytics Market
The Europe App Analytics Market size was valued at USD 393.08 million in 2018, projected to reach USD 824.18 million in 2024, and anticipated to grow to USD 3,297.44 million by 2032, at a CAGR of 17.6% during the forecast period. Europe holds a significant share in the global app analytics market. Countries such as the United Kingdom, Germany, and France are leading the way in adopting advanced app analytics solutions across industries like retail, banking, and telecommunications. The growing focus on customer-centric strategies, data privacy compliance, and enhanced mobile app performance fuels market expansion in the region. Furthermore, businesses in Europe are increasingly investing in artificial intelligence and machine learning technologies to refine their app analytics capabilities.
Asia Pacific App Analytics Market
The Asia Pacific App Analytics Market size was valued at USD 227.67 million in 2018, projected to reach USD 536.75 million in 2024, and anticipated to grow to USD 2,580.07 million by 2032, at a CAGR of 20.3% during the forecast period. The Asia Pacific region is expected to witness the highest growth rate in the global app analytics market. Rapid urbanization, increasing smartphone adoption, and a large number of mobile app developers in countries like China, India, and Japan are driving the demand for app analytics solutions. The region’s fast-growing middle class, along with the expanding e-commerce and digital sectors, creates ample opportunities for app analytics providers. Companies are adopting cloud-based platforms and AI-driven analytics tools to enhance user experience and app performance.
Latin America App Analytics Market
The Latin America App Analytics Market size was valued at USD 52.34 million in 2018, projected to reach USD 111.82 million in 2024, and anticipated to grow to USD 411.14 million by 2032, at a CAGR of 16.4% during the forecast period. The Latin American app analytics market is expanding as businesses in the region increasingly focus on digital transformation. The growing adoption of smartphones and mobile applications in countries like Brazil, Mexico, and Argentina is driving the need for app performance optimization and user engagement analytics. Furthermore, the demand for personalized content and data-driven marketing strategies is fueling the growth of app analytics platforms. While the market is still developing, Latin America offers substantial opportunities for expansion.
Middle East App Analytics Market
The Middle East App Analytics Market size was valued at USD 31.21 million in 2018, projected to reach USD 61.15 million in 2024, and anticipated to grow to USD 212.70 million by 2032, at a CAGR of 15.5% during the forecast period. The Middle East app analytics market is growing steadily, driven by the region’s focus on technological innovation and digitalization. Countries like the United Arab Emirates, Saudi Arabia, and Qatar are seeing increasing adoption of mobile applications across various sectors such as retail, banking, and healthcare. The region’s investments in smart city projects and increasing smartphone penetration are creating new opportunities for app analytics. As businesses seek to improve customer experiences and drive better app performance, demand for app analytics solutions continues to rise.
Africa App Analytics Market
The Africa App Analytics Market size was valued at USD 14.87 million in 2018, projected to reach USD 36.57 million in 2024, and anticipated to grow to USD 114.84 million by 2032, at a CAGR of 14.0% during the forecast period. The African app analytics market is in its early stages but shows strong growth potential due to increasing mobile phone penetration and the rise of mobile app developers. Many businesses in the region are exploring app analytics solutions to enhance customer experiences and optimize app performance. The growing adoption of smartphones, coupled with the expansion of mobile internet networks, provides a fertile ground for app analytics adoption. While challenges such as data security and infrastructure limitations remain, the market presents opportunities for growth as businesses in Africa seek to leverage app analytics for improved decision-making and user engagement.
Key Player Analysis:
- AppsFlyer
- Kochava
- Amazon Web Services (AWS)
- Adobe
- Mixpanel
- Countly
- AppDynamics
- Flurry
- App Annie
Competitive Analysis:
The competitive landscape of the global app analytics market is highly dynamic, with several key players offering advanced analytics solutions across industries. Major companies such as Google, Adobe, and Mixpanel dominate the market by providing robust platforms that enable businesses to track user behavior, optimize app performance, and drive engagement. These companies focus on integrating artificial intelligence, machine learning, and real-time data processing to enhance their product offerings. Smaller players and emerging startups are also carving out niches by offering specialized analytics tools tailored to specific industries or use cases. Intense competition and rapid technological advancements are pushing companies to innovate continuously and refine their solutions. The market is characterized by strategic partnerships, acquisitions, and investments aimed at expanding product capabilities and enhancing market presence. With the increasing demand for data-driven insights, the competition is expected to intensify, driving further innovation and development in the global app analytics market.
Recent Developments:
- In June 2025, Kochava announced a partnership with Fetch to launch Loyalty+, a performance-based rewards solution for streaming services. This collaboration integrates Fetch’s rewards ecosystem with Kochava’s measurement and attribution technology, enabling brands to incentivize and track user engagement across devices and platforms.
- In February 2025, Amazon Web Services (AWS)and General Catalyst announced a strategic partnership focused on deploying AI-powered healthcare analytics. Their joint initiative targets predictive care and operational efficiencies, leveraging app analytics to deliver improved health outcomes and cost savings in the healthcare sector.
- In January 2025, AppsFlyer launched a Data Collaboration Partnershipwith Wolt Ads. This partnership leverages AppsFlyer's Data Collaboration Platform to drive measurable revenue uplift for global brands, as demonstrated by a campaign that showed a 32% increase in attributed revenue.
Market Concentration & Characteristics:
The global app analytics market exhibits a moderately concentrated structure, with a few key players holding significant market share, such as Google, Adobe, and Mixpanel. These companies lead the market by offering comprehensive and scalable analytics solutions that cater to a wide range of industries, including retail, healthcare, and finance. Smaller players and startups focus on niche segments, providing specialized features or targeting specific geographic regions. The market is characterized by rapid technological advancements, particularly in artificial intelligence and machine learning, driving continuous innovation in app analytics tools. Strategic partnerships and acquisitions further contribute to the competitive dynamics, enabling companies to expand their capabilities and customer base. As businesses increasingly prioritize data-driven insights, the demand for app analytics solutions continues to grow, leading to a competitive market environment where both large and emerging companies strive to meet evolving customer needs.
Report Coverage:
The research report offers an in-depth analysis based on Offering, Type, Application and Vertical. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The global app analytics market is expected to grow rapidly, driven by increasing mobile app usage across diverse industries.
- Integration of artificial intelligence and machine learning into analytics platforms will enhance predictive capabilities and improve user experience.
- Cloud-based solutions will see a surge in adoption due to their scalability and cost-effectiveness for businesses of all sizes.
- Real-time analytics will become a key requirement as businesses strive to respond instantly to user behavior and market trends.
- Mobile app developers will continue to seek deeper insights into user engagement to optimize retention and increase profitability.
- Data privacy regulations, such as GDPR, will push the market towards more secure and compliant analytics solutions.
- The demand for cross-platform analytics will grow as businesses seek comprehensive insights across mobile, web, and other digital platforms.
- Regional expansion, particularly in Asia Pacific and Latin America, will drive new opportunities as mobile app usage accelerates.
- Small and medium-sized businesses will increasingly adopt app analytics tools to compete with larger enterprises.
- Strategic partnerships and acquisitions in the app analytics space will foster innovation and enhance product offerings.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Proliferation of Mobile Apps and User Data
The rapid increase in mobile app usage across industries is generating vast amounts of user data, prompting businesses to adopt advanced app analytics tools to optimize app performance and enhance user engagement.
Advancements in Artificial Intelligence and Machine Learning Integration
AI and ML technologies are being integrated into app analytics platforms, enabling deeper insights into user behavior, more accurate segmentation, and predictive analytics that help businesses anticipate trends and optimize user experiences.
Increasing Demand for Real-Time Data Analysis and Personalization
Businesses are seeking real-time analytics to instantly respond to user interactions and deliver personalized experiences, which drives the adoption of sophisticated app analytics solutions capable of processing and analyzing data on the fly.
Focus on Data Privacy and Compliance with Regulations
Stricter data privacy regulations such as GDPR and CCPA are compelling organizations to invest in secure and compliant app analytics tools, ensuring user data is protected while still enabling actionable insights.
Shift Towards Cloud-Based App Analytics Solutions
The flexibility, scalability, and cost-effectiveness of cloud-based analytics platforms are making them increasingly attractive, allowing organizations of all sizes to access powerful analytics capabilities without heavy infrastructure investments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global App Analytics Market?
What are the key segments within the Global App Analytics Market?
What are some challenges faced by the Global App Analytics Market?
Who are the major players in the Global App Analytics Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Mobile Apps
- 1.2.2 Web Apps
- 1.3 By Offering
- 1.3.1 Software
- 1.3.2 Services
- 1.4 By Vertical
- 1.4.1 BFSI (Banking, Financial Services, and Insurance)
- 1.4.2 Retail and Ecommerce
- 1.4.3 Telecom & IT
- 1.4.4 Healthcare and Life Sciences
- 1.4.5 Media & Entertainment
- 1.4.6 Transportation and Logistics
- 1.4.7 Gaming
- 1.4.8 Others
- 1.5 By Application
- 1.5.1 Advertising and Marketing Analytics
- 1.5.2 App Performance and Operations Management
- 1.5.3 Conversion Tracking
- 1.5.4 User Analytics
- 1.5.5 Revenue Management
- 1.5.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 1,242.60 million → 2024: USD 2,692.42 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2024
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2024
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global App Analytics Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global App Analytics Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2024
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global App Analytics Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2024
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global App Analytics Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global App Analytics Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global App Analytics Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global App Analytics Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global App Analytics Market Outlook, 2018-2024
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 1,242.60 million → 2024: USD 2,692.42 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2024
- 11.2.1 Revenue Forecast to 2024
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global App Analytics Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2018-2024
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2018-2024
- 12.3.4 Base-Year Market Share, 2018
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Mobile Apps
- 12.3.6.2 Web Apps
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Offering - Market Size and Forecast, 2018-2024
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2018-2024
- 12.4.4 Base-Year Market Share, 2018
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Software
- 12.4.6.2 Services
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Vertical - Market Size and Forecast, 2018-2024
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2018-2024
- 12.5.4 Base-Year Market Share, 2018
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 BFSI (Banking, Financial Services, and Insurance)
- 12.5.6.2 Retail and Ecommerce
- 12.5.6.3 Telecom & IT
- 12.5.6.4 Healthcare and Life Sciences
- 12.5.6.5 Media & Entertainment
- 12.5.6.6 Transportation and Logistics
- 12.5.6.7 Gaming
- 12.5.6.8 Others
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2018-2024
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2018-2024
- 12.6.4 Base-Year Market Share, 2018
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 Advertising and Marketing Analytics
- 12.6.6.2 App Performance and Operations Management
- 12.6.6.3 Conversion Tracking
- 12.6.6.4 User Analytics
- 12.6.6.5 Revenue Management
- 12.6.6.6 Others
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global App Analytics End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global App Analytics Geographic Market Outlook, 2018-2024
- 14.1 Regional Market Size and Share, 2018
- 14.2 Regional Market Forecast, 2018-2024
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global App Analytics Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2018-2024
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global App Analytics Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2018
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2018-2024
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 AppsFlyer
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Kochava
- 18.4 Google
- 18.5 Amazon Web Services (AWS)
- 18.6 Adobe
- 18.7 Mixpanel
- 18.8 Countly
- 18.9 AppDynamics
- 18.10 Flurry
- 18.11 App Annie
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

