
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Artificial Intelligence in Construction Market Size 2024 | USD 1620 million |
| Artificial Intelligence in Construction Market, CAGR | 32.36% |
| Artificial Intelligence in Construction Market Size 2032 | USD 15260.51 million |
Market Overview
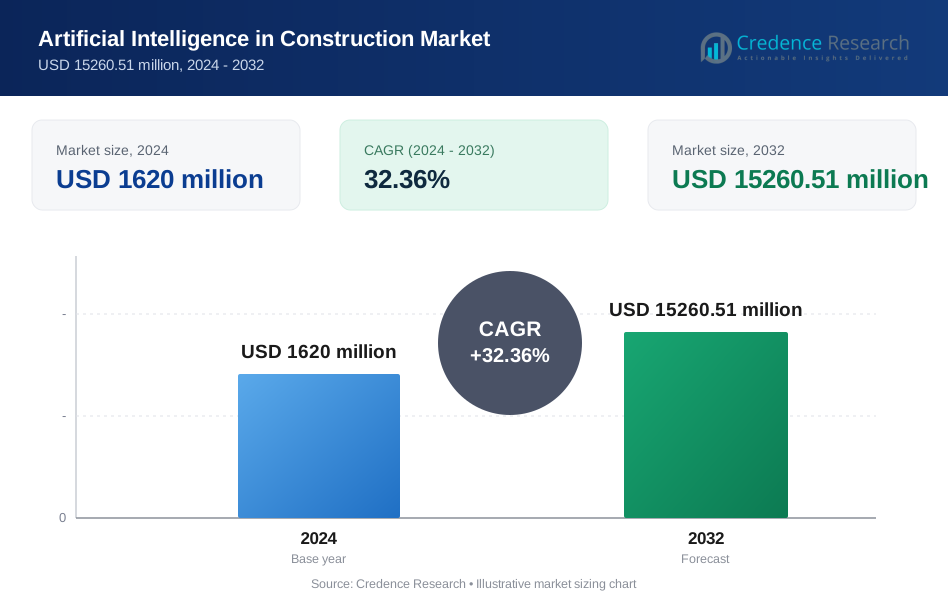
Artificial Intelligence in Construction Market size was valued at USD 1620 million in 2024 and is anticipated to reach USD 15260.51 million by 2032, at a CAGR of 32.36% during the forecast period (2024-2032).
The growth of AI in construction is primarily driven by the increasing adoption of AI-based technologies to address challenges such as project delays, labor shortages, and high operational costs. AI tools in construction help optimize planning, design, and execution, leading to faster decision-making, reduced risks, and improved productivity. Additionally, AI applications such as predictive maintenance, robotic automation, and AI-powered project management solutions are contributing to the operational efficiency of construction firms. The integration of AI with Internet of Things (IoT) devices and building information modeling (BIM) is also enhancing construction project outcomes by improving real-time data analysis and decision-making processes. Furthermore, the ability of AI to predict potential issues in the construction lifecycle is reducing downtime and ensuring better resource allocation. As AI technologies continue to evolve, their impact on project delivery timelines and budget management will become increasingly significant.
Regionally, North America dominates the AI in construction market, holding a significant share due to the early adoption of advanced technologies and the presence of key AI solution providers. The U.S., in particular, is witnessing high demand for AI applications in construction, driven by technological advancements and large-scale infrastructure projects. Europe is also experiencing substantial growth, with countries like the UK, Germany, and France embracing AI to improve construction productivity and reduce costs. Meanwhile, the Asia-Pacific region is anticipated to register the highest CAGR during the forecast period, owing to rapid urbanization, growing infrastructure investments, and technological advancements in countries such as China, Japan, and India. The rising demand for smart cities and sustainable infrastructure is further fueling AI adoption in the region. Additionally, significant government initiatives and funding for AI development are helping accelerate market growth in emerging economies.
Market Insights:
- The Artificial Intelligence in Construction market was valued at USD 1620 million in 2024 and is expected to reach USD 51 million by 2032, growing at a CAGR of 32.36% during the forecast period.
- The market growth is driven by the increasing adoption of AI technologies to address challenges such as labor shortages, project delays, and high operational costs.
- AI applications such as predictive maintenance, robotic automation, and AI-powered project management solutions are enhancing operational efficiency in the construction industry.
- Integration of AI with IoT and BIM is improving real-time data analysis and decision-making, leading to better construction project outcomes.
- North America dominates the market with a significant share due to early adoption of AI technologies and major investments from technology providers and construction firms.
- Europe holds a 30% market share, driven by government incentives and regulatory frameworks that encourage AI adoption in construction projects, particularly in countries like Germany, the UK, and France.
- The Asia-Pacific region is the fastest-growing market, fueled by rapid urbanization, large-scale infrastructure development, and increasing government investment in smart city projects in countries like China, Japan, and India.
Market Drivers:
Increasing Demand for Automation:
The construction industry faces challenges such as inefficiencies, manual errors, and resource wastage, all of which impact project timelines and budgets. To address these issues, there is a growing demand for automation in construction processes. AI technologies like robotic automation, machine learning, and AI-powered project management systems streamline tasks such as data entry, resource allocation, and scheduling. By reducing human error and improving decision-making speed, AI enhances productivity and safety, driving efficiency in the construction sector. Automation is particularly crucial in overcoming labor shortages and controlling rising construction costs, further promoting AI adoption.
AI-Driven Predictive Analytics for Risk Management:
Risk management is another area where AI is playing a transformative role in the construction market. The industry faces inherent risks, including project delays, cost overruns, and safety hazards. For instance, Turner Construction has integrated AI-driven risk management strategies into its project management procedures, enabling early detection of high-risk regions and allowing the company to take proactive measures to address issues before they escalate. AI-powered predictive analytics analyze historical data to identify potential risks, forecast project outcomes, and recommend proactive solutions. This capability allows construction managers to address potential issues before they escalate, reducing downtime, improving resource allocation, and preventing delays. By using AI to predict and mitigate risks, construction projects become more efficient, cost-effective, and successful.
Improvement in Project Design and Decision-Making:
AI is enhancing the design and decision-making processes in construction. Traditional design methods often involve inefficiencies and trial-and-error approaches. For example, Autodesk’s generative design technology enables architects and designers to generate multiple design options for structures based on predefined goals and constraints, such as building materials, energy efficiency, and structural integrity. AI, through machine learning algorithms, helps generate optimized designs based on multiple factors like cost, materials, and energy efficiency. AI also enables real-time data analysis from construction sites, such as worker productivity and weather conditions, facilitating better decision-making. This data-driven approach not only accelerates the design process but also improves the quality and efficiency of construction projects.
Government Support and Technological Advancements:
Government initiatives and technological advancements are key enablers of AI adoption in the construction sector. Governments worldwide are promoting AI integration through funding programs and incentives, particularly in regions like North America and Europe. These efforts help construction companies adopt AI-driven solutions that improve operational efficiency, safety, and sustainability. Additionally, advancements in AI technologies like natural language processing, computer vision, and deep learning, along with the integration of IoT and BIM, continue to drive innovation, making AI an increasingly integral part of the construction industry’s future.
Market Trends:
Integration of AI with Building Information Modeling (BIM):
The adoption of Artificial Intelligence (AI) in the construction industry has witnessed substantial growth in recent years, driven by the increasing demand for enhanced operational efficiency and productivity. One of the prominent trends is the integration of AI with building information modeling (BIM) and construction management software. AI-powered BIM tools are enabling construction firms to streamline project planning, design, and execution processes, resulting in faster decision-making and reduced errors. These technologies facilitate real-time data analysis, which optimizes resource allocation and improves collaboration among various stakeholders, ultimately reducing project delays and costs.
AI-Driven Predictive Analytics for Safety:
Another significant trend is the use of AI-driven predictive analytics to enhance construction site safety. For instance, Turner Construction implemented predictive analytics during a high-rise development in New York City by analyzing data from wearable IoT devices and historical incident records to proactively identify fall-prone areas and target interventions, which resulted in a notable reduction in fall-related incidents. AI systems can analyze vast amounts of data from past projects, equipment performance, and worker behavior to identify potential safety hazards before they occur. Predictive models enable construction companies to implement preventive measures, ensuring safer work environments. Additionally, AI-powered safety solutions are helping detect and mitigate risks related to machinery malfunctions or adverse environmental conditions, providing a more proactive approach to safety management.
Rise of Robotics and Automation:
The rise of robotics and automation is also transforming the construction industry, with AI playing a pivotal role in this shift. For instance, Spot, an autonomous construction robot developed by Trimble and Boston Dynamics, is now used on job sites to autonomously perform scans, monitor progress, and collect data in hazardous or hard-to-reach environments, reducing the need for human workers to enter dangerous areas. AI-powered robots are increasingly being used for tasks such as bricklaying, welding, and demolition. These autonomous systems are not only improving construction speed but also reducing human error and labor costs. Furthermore, the development of autonomous vehicles and drones equipped with AI algorithms is enabling construction companies to monitor progress, perform site inspections, and transport materials efficiently. As these technologies evolve, the level of automation in construction processes is expected to increase significantly.
AI for Sustainability and Predictive Maintenance:
Lastly, AI is playing a crucial role in the sustainability efforts of the construction industry. AI algorithms are being utilized to design energy-efficient buildings and optimize material usage, which significantly reduces waste and environmental impact. Moreover, AI is helping companies implement predictive maintenance for equipment, reducing downtime and extending the lifespan of machinery. By incorporating AI into construction operations, companies are not only improving their bottom line but also contributing to environmental conservation and sustainability efforts.
Market Challenges Analysis:
High Implementation Costs and Technical Complexity:
One of the primary challenges hindering the widespread adoption of Artificial Intelligence (AI) in the construction industry is the high cost of implementation and the technical complexity involved. Integrating AI technologies into existing construction processes requires significant investment in infrastructure, software, and skilled personnel. For instance, a survey among industry professionals highlighted that many construction firms, such as those participating in the Saudi construction sector, face substantial financial barriers to adopting AI solutions due to high operational costs and equipment expenses. Many construction companies, particularly small and medium-sized enterprises (SMEs), struggle with the financial burden of adopting these advanced solutions. Additionally, the complexity of integrating AI with existing construction management tools and workflows poses a considerable barrier. Firms must overcome technical difficulties related to data interoperability, AI model accuracy, and system customization, making it difficult for some companies to fully leverage AI’s potential.
Data Privacy and Security Concerns:
Another significant challenge facing the AI-driven construction market is the issue of data privacy and security. Construction projects generate vast amounts of data, from design specifications to worker activities, which is essential for AI algorithms to function effectively. However, safeguarding this data from cyber threats and ensuring compliance with data protection regulations remains a major concern. Many construction companies are hesitant to share sensitive project data due to fears of data breaches, intellectual property theft, or unauthorized access. Moreover, the use of AI in construction often requires data sharing across various stakeholders, further complicating the security and privacy landscape. Addressing these concerns will require robust cybersecurity measures, strict regulatory compliance, and industry-wide collaboration to ensure that the adoption of AI does not compromise data integrity and security.
Market Opportunities:
The artificial intelligence (AI) market in the construction industry presents significant opportunities as the sector increasingly embraces digital transformation. One of the key opportunities lies in the optimization of project management processes. AI-driven tools can enhance scheduling, resource allocation, and cost estimation, ultimately streamlining project execution. By reducing human error and improving decision-making through predictive analytics, AI helps construction companies stay within budget and meet deadlines more consistently. The growing demand for smarter, more efficient construction practices opens the door for AI applications across various stages of the project lifecycle, from design and planning to execution and maintenance.
Furthermore, the AI market in construction has substantial growth potential through advancements in automation and robotics. The adoption of AI-powered robots for tasks such as bricklaying, welding, and inspection offers the potential to increase productivity while reducing labor costs and safety risks. As AI technologies continue to evolve, their integration with autonomous machinery, such as drones and self-driving vehicles, will enhance construction efficiency and enable real-time project monitoring. Moreover, AI’s role in driving sustainability initiatives, such as designing energy-efficient buildings and optimizing material usage, presents a unique opportunity to align with global sustainability goals. As the construction industry continues to prioritize environmental impact, AI can play a vital role in reducing waste and carbon footprints, further expanding its market presence and value proposition.
Market Segmentation Analysis:
By Offering
The Artificial Intelligence in Construction market is segmented based on offerings, which include solutions and services. Solutions dominate the market, accounting for the majority of the revenue due to the growing demand for AI-powered software in construction project management, predictive maintenance, and automation. These solutions are being integrated with existing construction management platforms to improve efficiency, reduce human error, and optimize resources. Services, such as AI consulting, system integration, and maintenance, are also gaining traction as construction firms seek expert guidance for AI adoption and implementation.
By Stage
In terms of market stages, the AI in construction industry is divided into three phases: planning, execution, and operations. The execution stage holds the largest share, as AI tools are predominantly used during the construction phase for tasks such as project management, risk assessment, and process automation. The planning stage is also significant, as AI assists with project design, scheduling, and resource allocation. The operations stage, although smaller in comparison, is growing as AI is increasingly used for predictive maintenance and facility management after construction is completed.
By Application
AI in construction is applied across several areas, including design and planning, construction site management, and safety monitoring. The construction site management segment is the largest due to AI's role in optimizing workflows, ensuring safety, and improving productivity. Safety monitoring is also a key application, where AI technologies such as computer vision are used to detect hazards and ensure compliance with safety protocols.
Segmentations:
By Offering:
- Solutions
- Services
- Planning
- Execution
- Operations
- Design and Planning
- Construction Site Management
- Safety Monitoring
- Project Management
- Predictive Maintenance
- Cloud-based Deployment
- On-premise Deployment
- Residential Construction
- Commercial Construction
- Industrial Construction
- Infrastructure
- Small and Medium-sized Enterprises (SMEs)
- Large Enterprises
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America
North America holds the largest market share, accounting for 40% of the global artificial intelligence in construction market. The region’s leadership can be attributed to early adoption of AI technologies across the construction sector, driven by significant investments in research and development by major construction firms and technology providers. The U.S. and Canada have developed robust infrastructure and regulatory frameworks that support the integration of AI solutions, from project management to safety monitoring. The region's focus on enhancing operational efficiency and sustainability in construction projects continues to drive AI adoption, fostering further innovation in the sector. As the demand for smart building solutions increases, North America is well-positioned to maintain its dominant role in AI-powered construction technologies.
Europe
Europe follows closely with a market share of 30%, with strong growth driven by government incentives and regulatory frameworks that encourage digitalization in construction. The European Union’s focus on sustainability, energy-efficient buildings, and the development of smart cities has created a favorable environment for AI applications in the construction sector. Countries like Germany, the UK, and France lead the charge in integrating AI into construction management, building information modeling (BIM), and predictive analytics. The increasing emphasis on reducing carbon footprints and optimizing resources also boosts AI adoption. As the region continues to implement stringent regulations on environmental standards, AI-driven construction solutions will likely expand further in Europe, enhancing productivity and operational efficiency across the sector.
Asia-Pacific
The Asia-Pacific region, with a market share of 20%, is the fastest-growing segment for AI in construction. This growth is fueled by rapid urbanization, large-scale infrastructure development, and the increasing adoption of advanced technologies in countries such as China, Japan, and India. Governments in the region are investing heavily in smart city projects, which provide ample opportunities for AI integration into construction processes. Additionally, the increasing need for automation, predictive maintenance, and AI-powered project management tools to improve efficiency and reduce costs is driving market growth. As the demand for infrastructure projects continues to surge, the Asia-Pacific market will be pivotal in expanding the use of AI-driven technologies, further solidifying its potential for future growth.
Key Player Analysis:
- Microsoft
- Oracle
- SAP SE
- Autodesk Inc.
- International Business Machines Corporation
- Trimble Inc.
- ALICE Technologies Inc.
- Building Connected
- The Access Group
- Doxel.
Competitive Analysis:
The competitive landscape of the Artificial Intelligence in Construction market is characterized by the presence of both established technology providers and emerging AI-focused startups. Major players such as Autodesk, IBM, and Trimble dominate the market, leveraging their extensive experience in construction software and AI technologies to provide comprehensive solutions that enhance project management, safety, and design efficiency. These companies are investing heavily in research and development to integrate AI into building information modeling (BIM), predictive analytics, and automation tools. In addition to these large companies, several AI-focused startups are innovating in niche areas such as robotics, autonomous vehicles, and real-time monitoring systems. These startups are offering specialized AI solutions that improve construction site safety, reduce costs, and optimize resource allocation. Strategic partnerships and collaborations between technology providers and construction firms are common, fostering innovation and accelerating the adoption of AI technologies across the construction industry.
Recent Developments:
- In April 2024, Engineers India Limited (EIL) partnered with Detect Technologies Private Limited to implement real-time AI-based monitoring solutions across EIL construction sites worldwide.
- In January 2024, Autodesk experts highlighted AI's growing role in construction, including advanced project management, predictive risk analytics, automation of tedious tasks, and integration with BIM for better design and planning efficiency.
Market Concentration & Characteristics:
The Artificial Intelligence in Construction market is moderately concentrated, with a few large players holding significant market share, alongside a growing number of specialized startups. Established companies like Autodesk, IBM, and Trimble lead the market by providing comprehensive AI-driven solutions for project management, design optimization, and safety improvements. These companies benefit from their established reputation, vast resources, and strong R&D capabilities, enabling them to integrate AI into various aspects of the construction process. However, the market is also witnessing the rise of smaller, niche players focusing on specific AI applications such as robotics, autonomous vehicles, and real-time data analytics for construction sites. These startups are driving innovation by offering cutting-edge technologies that enhance operational efficiency and reduce costs. Overall, the market is characterized by a combination of consolidation among key players and rapid innovation from emerging companies, creating a dynamic and competitive landscape.
Report Coverage:
The research report offers an in-depth analysis based on Offering, Stage, Application, Deployment, Industry, Organization Size and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- AI technologies are anticipated to significantly enhance construction productivity by optimizing project planning, resource allocation, and risk management.
- Generative AI is set to revolutionize design processes by automating the creation of building layouts and structural systems, leading to more efficient and sustainable designs.
- The integration of AI with Building Information Modeling (BIM) is expected to streamline construction workflows, improving coordination and reducing errors across project stages.
- AI-powered robotics and automation are projected to take on repetitive tasks such as bricklaying and welding, enhancing construction speed and safety.
- Predictive maintenance driven by AI is anticipated to reduce equipment downtime and extend the lifespan of machinery, leading to cost savings.
- AI is expected to play a crucial role in smart city initiatives by optimizing energy usage, waste management, and infrastructure planning.
- The adoption of AI in construction is likely to improve safety by identifying and mitigating potential hazards in real-time.
- AI's ability to analyze large datasets is expected to enhance decision-making processes, leading to more informed and efficient project executions.
- The growing demand for AI solutions is anticipated to drive innovation and competition among technology providers in the construction sector.
- As AI technologies become more accessible, small and medium-sized enterprises are expected to increasingly adopt AI tools, leveling the playing field in the construction industry.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the size of the Artificial Intelligence in Construction market?
What are the key drivers of growth in the AI in Construction market?
Which region leads the AI in Construction market?
How is AI being integrated into construction?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Artificial Intelligence in Construction Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Artificial Intelligence in Construction Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1620 million → 2032: USD 15260.51 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Artificial Intelligence in Construction Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Artificial Intelligence in Construction Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Artificial Intelligence in Construction Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Artificial Intelligence in Construction Market Drivers
- 3.3 Artificial Intelligence in Construction Market Restraints & Challenges
- 3.4 Artificial Intelligence in Construction Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Artificial Intelligence in Construction Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Artificial Intelligence in Construction Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Artificial Intelligence in Construction category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Artificial Intelligence in Construction Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Artificial Intelligence in Construction Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Artificial Intelligence in Construction. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Artificial Intelligence in Construction Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Artificial Intelligence in Construction Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Artificial Intelligence in Construction Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Artificial Intelligence in Construction (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Artificial Intelligence in Construction
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Artificial Intelligence in Construction Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Artificial Intelligence in Construction Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Artificial Intelligence in Construction Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Artificial Intelligence in Construction Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Artificial Intelligence in Construction Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Artificial Intelligence in Construction Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Artificial Intelligence in Construction Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Artificial Intelligence in Construction Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
