
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Asia Pacific Grid Modernization Market Size 2024 | USD 12,683.42 million |
| Asia Pacific Grid Modernization Market, CAGR | 19.16% |
| Asia Pacific Grid Modernization Market Size 2032 | USD 51,572.06 million |
Market Overview
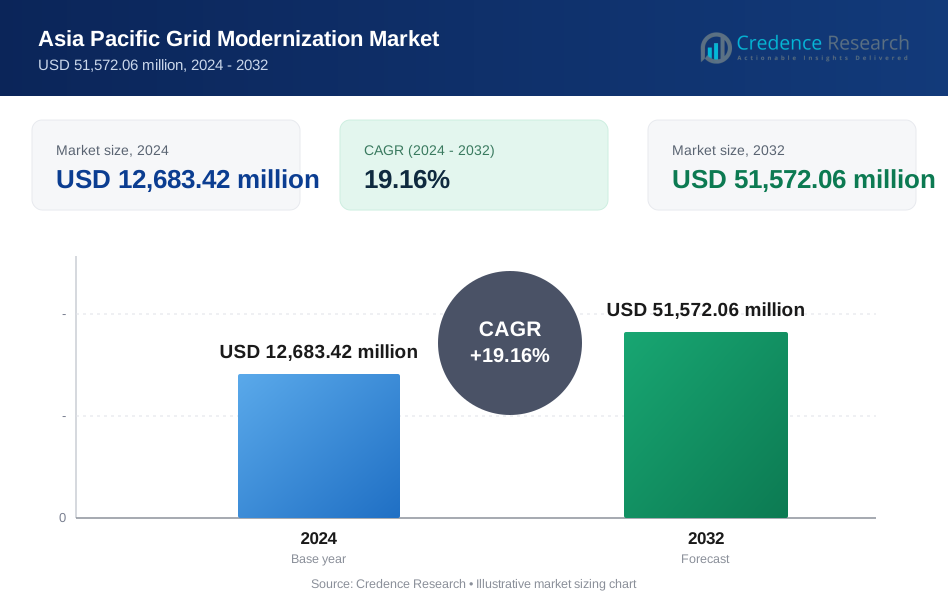
Asia Pacific Grid Modernization market size was valued at USD 12,683.42 million in 2024 and is anticipated to reach USD 51,572.06 million by 2032, at a CAGR of 19.16% during the forecast period (2024-2032).
The Asia Pacific Grid Modernization market is driven by increasing demand for efficient, reliable, and sustainable energy distribution systems. Rapid urbanization, industrial growth, and the integration of renewable energy sources are key factors propelling market growth. Governments are investing in modernizing outdated grid infrastructure to improve energy security and support the transition to cleaner energy. The rise of smart grid technologies, including advanced metering infrastructure, demand response systems, and automation, is also a significant driver, enabling better grid management and real-time monitoring. Additionally, the growing focus on reducing carbon emissions and improving energy efficiency is boosting the adoption of smart grids. Market trends indicate a shift towards digitalization, energy storage solutions, and decentralized grid systems, further enhancing the region’s ability to meet future energy demands. As the region continues to prioritize sustainable energy solutions, grid modernization efforts are expected to play a pivotal role in shaping the future of energy distribution.
The Asia Pacific Grid Modernization market is driven by key players such as ABB Ltd., Siemens AG, Schneider Electric SE, Hitachi Energy, and General Electric Asia Pacific, who are actively involved in providing advanced grid solutions across the region. These companies play a pivotal role in enhancing grid efficiency, integrating renewable energy, and developing smart grid technologies to address the growing energy demands of countries like China, India, Japan, and Australia. In Southeast Asia, companies like Toshiba Asia Pacific and Eaton Asia Pacific are contributing to the modernization of energy infrastructure, focusing on energy storage solutions and automation. As the region continues to prioritize sustainability, the role of these key players in supporting grid resilience and advancing energy transition technologies is crucial. Their ongoing investments in research and development, along with strategic collaborations with local governments, are shaping the future of grid modernization in the Asia Pacific market.
Market Insights
- The Asia Pacific Grid Modernization market was valued at USD 12,683.42 million in 2024 and is projected to reach USD 51,572.06 million by 2032, growing at a CAGR of 19.16%.
- Increasing demand for energy efficiency and reliable power distribution is driving investments in grid modernization technologies.
- The integration of renewable energy sources like solar and wind is a major trend, pushing for smarter, more flexible grids.
- Digitalization, including the adoption of smart grids and energy storage solutions, is transforming grid management.
- Major companies such as ABB Ltd., Siemens AG, and Schneider Electric SE are key players in the market, focusing on technology innovations and strategic partnerships.
- High infrastructure costs and regulatory challenges are major market restraints, limiting growth in some regions.
- China, India, and Japan lead the market, with other countries in Southeast Asia gradually increasing investments in grid modernization.
Market Drivers
Increasing Demand for Energy Efficiency
The Asia Pacific region’s rapid urbanization and industrialization have led to a surge in energy demand, necessitating the modernization of grid infrastructure. The need for more efficient power distribution systems is driving investments in grid modernization to meet rising consumption levels. Governments and private sector players are actively pursuing technologies that can optimize energy usage, reduce transmission losses, and enhance overall grid reliability. This growing focus on energy efficiency is fueling the expansion of the grid modernization market across the region.
Integration of Renewable Energy Sources
As countries in Asia Pacific aim to reduce their carbon footprints, the integration of renewable energy sources such as wind, solar, and hydropower has become a key focus. Grid modernization enables the seamless integration of these intermittent energy sources into existing power grids by improving flexibility, stability, and reliability. For example, in Australia, the Australian Renewable Energy Agency (ARENA) has funded projects to integrate renewable energy into the grid, enhancing grid stability and reliability. Smart grid technologies, such as energy storage systems and real-time monitoring, support the integration of renewables and help balance supply and demand efficiently, ensuring that the grid remains stable while accommodating green energy sources.
Government Support and Policy Initiatives
Governments in the Asia Pacific region are actively supporting grid modernization efforts through policy initiatives, funding, and regulatory reforms. National and local governments are prioritizing energy transition programs that focus on enhancing grid infrastructure to support the growth of renewable energy and ensure reliable power distribution. For instance, Japan's Ministry of Economy, Trade and Industry (METI) has introduced policies to promote smart grid technologies, aiming to reduce energy consumption and integrate more renewable energy into the grid. For example, countries like India, China, and Japan have introduced large-scale initiatives to develop and upgrade their power grids, creating a conducive environment for the expansion of grid modernization technologies and solutions in the region.
Technological Advancements and Smart Grid Adoption
Advancements in smart grid technologies are transforming the way power grids are managed in Asia Pacific. The rise of automation, demand response systems, and advanced metering infrastructure is enabling better real-time monitoring and control of energy flows. These technologies allow utilities to predict and respond to fluctuations in demand, reduce outages, and improve grid resilience. As businesses and consumers demand more reliable and responsive energy systems, the adoption of smart grids is accelerating, driving the growth of the grid modernization market in the region.
Market Trends
Digitalization of Grid Infrastructure
A major trend in the Asia Pacific Grid Modernization market is the increasing digitalization of grid infrastructure. The implementation of advanced sensors, communication systems, and data analytics is transforming traditional grids into intelligent networks. These digital tools enable utilities to monitor grid performance in real time, predict potential issues, and implement proactive maintenance strategies. For instance, the State Grid Corporation of China has invested heavily in digital technologies to enhance grid efficiency and reliability. The use of digital technologies such as advanced metering infrastructure (AMI) and supervisory control and data acquisition (SCADA) systems is enhancing grid efficiency and reducing downtime, ensuring more reliable energy distribution across the region.
Decentralized Energy Systems
Decentralized energy systems are becoming more prominent in Asia Pacific as part of grid modernization efforts. With the rise of distributed energy resources (DERs), such as rooftop solar panels and local battery storage, energy generation is moving closer to end users. Modern grids are being designed to manage these decentralized systems efficiently, facilitating energy sharing and enhancing grid flexibility. This trend is driven by the increasing desire for energy independence and sustainability, particularly in remote or off-grid areas. As the region adopts decentralized energy models, grid infrastructure must evolve to accommodate these changes.
Focus on Energy Storage Solutions
Energy storage technologies are playing a critical role in the grid modernization process, particularly as the demand for renewable energy increases. Battery storage systems, such as lithium-ion batteries, are being integrated into power grids to store excess energy generated by renewable sources like solar and wind. These storage solutions allow for energy to be released when demand peaks, ensuring grid stability and reducing reliance on fossil fuels. The growing emphasis on energy storage technologies in the Asia Pacific region is helping to address intermittency issues associated with renewable energy sources and improving the overall reliability of the grid.
Adoption of Electric Vehicles (EVs)
The increasing adoption of electric vehicles (EVs) in the Asia Pacific region is another key trend shaping grid modernization. As the number of EVs rises, the demand for charging infrastructure and grid capacity is growing. Grid modernization allows utilities to integrate EV charging stations efficiently, managing energy load fluctuations caused by EV charging. Additionally, EVs can be leveraged as mobile energy storage units, providing further flexibility to the grid. This trend highlights the intersection of transportation and energy sectors and underscores the need for modernized grids to accommodate the growing EV infrastructure.
Market Challenges Analysis
High Infrastructure Costs and Investment
One of the primary challenges facing grid modernization in the Asia Pacific region is the high cost of upgrading and expanding grid infrastructure. Modernizing outdated power grids requires substantial investments in advanced technologies, such as smart meters, sensors, and energy storage systems. The financial burden of these upgrades can be particularly challenging for developing nations, where budget constraints and limited access to financing may hinder progress. Additionally, retrofitting existing grids to accommodate new technologies without disrupting service can further increase the complexity and cost of the modernization process. Despite the long-term benefits of improved grid reliability and energy efficiency, the upfront investment required remains a significant barrier to widespread grid modernization across the region.
Regulatory and Policy Challenges
Another challenge faced by the Asia Pacific Grid Modernization market is navigating the complex regulatory and policy landscape. Different countries in the region have varying levels of government support, regulatory frameworks, and energy policies, which can create inconsistencies in the implementation of grid modernization projects. For instance, in India, numerous studies have flagged several issues, including poor operational performance and rising accumulated losses of discoms, tremendous pressure on tariffs, and little/no improvement in cross-subsidy levels. Some nations may lack the necessary regulatory infrastructure to encourage the adoption of new technologies or incentivize private sector investment. Additionally, the integration of renewable energy sources and decentralized systems into existing grids often requires comprehensive policy reforms to ensure grid stability and fairness in energy distribution. The absence of clear, standardized regulations can slow down progress and create uncertainty for investors and utility providers, further complicating efforts to modernize grids effectively.
Market Opportunities
Expansion of Renewable Energy Integration
The growing focus on renewable energy in the Asia Pacific region presents a significant market opportunity for grid modernization. As countries increasingly transition to cleaner energy sources, such as solar, wind, and hydropower, the demand for advanced grid systems capable of efficiently integrating these intermittent power sources is rising. Grid modernization technologies, such as energy storage systems, demand response solutions, and smart grids, are essential to maintaining grid stability and reliability while accommodating renewable energy. This shift towards greener energy offers opportunities for the development of infrastructure that supports the seamless integration of renewables, fostering a cleaner and more resilient energy landscape in the region.
Digital Transformation and Smart Grid Adoption
Another key opportunity lies in the digital transformation of power grids. The adoption of smart grid technologies, including real-time monitoring, advanced metering infrastructure, and predictive analytics, offers immense potential for improving grid efficiency and reliability. As utilities in the region move towards digitalization, there is an opportunity to modernize grid management systems, reducing operational costs, minimizing outages, and enhancing energy distribution. Additionally, the implementation of automation and artificial intelligence in grid operations can lead to more responsive energy systems that cater to the growing demands of both urban and rural areas. The increasing focus on digital technologies presents a robust opportunity for companies to provide innovative solutions that help utilities manage complex grids and optimize energy usage.
Market Segmentation Analysis:
By Component:
The Asia Pacific Grid Modernization market is segmented into hardware, software, and services. The hardware segment, which includes components like transformers, circuit breakers, sensors, and energy storage systems, plays a vital role in modernizing the grid infrastructure. With the growing adoption of renewable energy and the need for grid resilience, demand for robust hardware solutions is expected to rise. The software segment focuses on advanced metering infrastructure, grid management software, and analytics tools, enabling real-time monitoring, control, and optimization of energy distribution. The software-driven shift towards smart grids is key to enhancing efficiency and reliability. The services segment, encompassing installation, maintenance, and consulting, is also crucial, ensuring the effective implementation and long-term operation of grid modernization projects. This segment is expected to grow as utilities require specialized expertise to integrate advanced technologies and maintain the evolving grid infrastructure.
By Application:
The market is further segmented by application into residential, commercial, and industrial sectors. In the residential sector, grid modernization efforts aim to improve energy efficiency and reliability, particularly with the integration of renewable energy sources and energy storage systems. Smart meters and home energy management systems (HEMS) are becoming increasingly popular in residential applications, offering consumers greater control over their energy usage. In the commercial and industrial sectors, grid modernization supports larger-scale energy management solutions, reducing operational costs and enhancing energy efficiency. These sectors are increasingly adopting automation, demand response systems, and advanced grid management tools to optimize energy consumption and reduce carbon footprints. As industries and businesses move toward sustainability, the demand for efficient grid systems to support these applications will continue to grow, further driving the market's expansion across the Asia Pacific region.
Segments:
Based on Component:
- Hardware
- Software
- Services
Based on Application:
- Residential
- Commercial
- Industrial
Based on End-User:
- Utilities
- Independent Power Producers (IPPs)
- Government and Municipalities
Based on the Geography:
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
Regional Analysis
China and India
China and India dominate the Asia Pacific Grid Modernization market due to their large populations, rapid industrialization, and significant energy consumption. As the largest energy consumers in the region, these two countries have been at the forefront of grid modernization initiatives. China holds the largest market share, contributing approximately 40% of the total market in the region, driven by its extensive investment in renewable energy, energy storage solutions, and smart grid technologies. The country’s ambitious plans for reducing carbon emissions and transitioning to green energy have accelerated the adoption of grid modernization technologies. India, on the other hand, holds around 25% of the market share, with its government’s focus on enhancing energy access, integrating renewable sources, and expanding infrastructure in rural and urban areas. Both countries are expected to maintain strong growth in grid modernization, with China continuing to lead in large-scale infrastructure projects and India increasing its investments in smart grid technologies and energy storage solutions.
Japan
Japan holds a significant share in the Asia Pacific Grid Modernization market, accounting for around 12%. The country is a pioneer in implementing advanced grid technologies, with a strong focus on energy efficiency, disaster resilience, and the integration of renewable energy. Japan's commitment to reducing greenhouse gas emissions and its focus on energy security drive the demand for innovative grid solutions. The adoption of smart grids and energy storage technologies has become a central part of Japan's energy strategy, helping the country manage the integration of solar and wind power effectively. Additionally, Japan's position as a leader in technology development further propels the market, with numerous companies and research institutes focusing on the innovation of grid management solutions. The country’s proactive approach to modernizing its grid infrastructure, combined with its high technological capabilities, positions it as a key player in the Asia Pacific market.
South Korea and Australia
South Korea and Australia are also contributing significantly to the growth of the Asia Pacific Grid Modernization market. South Korea holds a market share of approximately 8%, with ongoing efforts to improve grid efficiency and integrate renewable energy into its grid. The country is heavily investing in smart grid technology, particularly in urban areas, to manage energy consumption and enhance grid reliability. Meanwhile, Australia has a market share of around 6%, driven by its increasing demand for energy solutions that support the transition to renewable energy. The adoption of energy storage systems, smart meters, and grid automation technologies is rising in Australia, where the government’s commitment to achieving net-zero emissions by 2050 is pushing grid modernization initiatives. Both South Korea and Australia are expected to see steady growth in their respective grid modernization markets, thanks to supportive government policies and technological advancements.
Southeast Asia and Rest of Asia Pacific
Southeast Asia, including countries such as Thailand, Indonesia, Vietnam, Malaysia, and the Philippines, represents a growing market for grid modernization. Together, these countries contribute approximately 9% to the overall market share. The rising demand for energy, coupled with the need for energy infrastructure development, presents opportunities for grid modernization in this region. Countries like Indonesia and Vietnam are focusing on upgrading their grids to support economic development and renewable energy integration. Meanwhile, countries in Southeast Asia are also prioritizing energy security and sustainability, driving investments in modern grid systems. The Rest of Asia Pacific, including regions like Taiwan and smaller economies, accounts for the remaining 4% of the market share. While these markets are smaller, they are emerging with increasing investments in energy modernization and renewable energy integration, contributing to the overall growth of grid modernization in the Asia Pacific region.
Key Player Analysis
- ABB Ltd.
- Siemens AG
- Schneider Electric SE
- Hitachi Energy
- General Electric Asia Pacific
- Alstom SA
- Toshiba Asia Pacific
- Landis+Gyr AG
- Siemens Gamesa
- Eaton Asia Pacific
Competitive Analysis
The Asia Pacific Grid Modernization market is highly competitive, with several global players leading the charge in advancing smart grid technologies and energy solutions. Key players such as ABB Ltd., Siemens AG, Schneider Electric SE, Hitachi Energy, General Electric Asia Pacific, Alstom SA, Toshiba Asia Pacific, Landis+Gyr AG, Siemens Gamesa, and Eaton Asia Pacific dominate the market. These companies offer a wide range of products, including smart meters, energy storage solutions, grid automation systems, and renewable energy integration technologies. Companies in this market are offering a wide range of products, including smart meters, energy storage solutions, grid automation systems, and renewable energy integration technologies. The competition is driven by the growing need for efficient, resilient, and sustainable energy grids in response to rising energy demands and the integration of renewable energy sources. The leading players are leveraging their expertise in energy management and automation systems to enhance operational efficiency for utilities. For instance, ABB Ltd. has been involved in providing smart grid solutions that help utilities manage energy more effectively. Companies are also focusing on the development of advanced grid equipment to optimize performance and ensure grid stability. Energy storage and smart grid solutions are gaining traction, particularly in addressing the challenges associated with renewable energy integration and grid resilience. Additionally, strategic partnerships, research and development, and acquisitions are key tactics used by market leaders to stay competitive. Companies are also responding to the increasing demand for sustainable energy solutions by advancing technologies that support renewable energy integration, improve grid efficiency, and strengthen grid infrastructure across the Asia Pacific region. The market remains dynamic, with players continuing to innovate to meet the evolving needs of the energy sector.
Recent Developments
- In October 2024, Hitachi Energy introduced Grid-enSure in India to advance the country's transition to sustainable energy. The company also announced plans to invest around INR 2,000 crore over the next four to five years in capacity expansion and upgrades for various transformer factories.
- In August 2024, Hitachi Energy called for urgent action to expand global power grids, reduce connection bottlenecks, and accelerate the energy transition. They launched Grid-enSure™ at the CIGRE 2024 Paris Session, a portfolio of solutions to enhance grid flexibility, resilience, and stability.
- In May 2024, Siemens revealed the Gridscale X software, a "co-pilot" for flexible low voltage grid management, aiming to reduce outages by up to 30%.
Market Concentration & Characteristics
The Asia Pacific Grid Modernization market is characterized by moderate concentration, with a mix of established global players and regional companies actively driving innovation and development. The market's concentration is influenced by the need for specialized expertise, large-scale infrastructure investments, and advanced technological solutions to modernize aging grid systems. Leading companies have a significant presence, particularly in countries with large energy consumption like China, India, and Japan. These players are focusing on smart grid technologies, energy storage solutions, and renewable energy integration to meet the region's growing demand for more efficient and resilient power grids. The market exhibits a high level of competition, with companies striving to provide cutting-edge solutions that enhance grid reliability, optimize energy usage, and support the integration of renewable energy sources. Technological advancements, such as real-time monitoring systems, automation, and predictive analytics, are key drivers of market growth. At the same time, regional players play a crucial role in addressing local market needs, including regulatory compliance and infrastructure challenges. This dynamic environment encourages both innovation and collaboration, as players seek to expand their market share through partnerships, mergers, and acquisitions. The market’s characteristics highlight the importance of both large multinational corporations and specialized regional firms in driving grid modernization efforts across the Asia Pacific region.
Report Coverage
The research report offers an in-depth analysis based on Component, Application, End-User, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Asia Pacific Grid Modernization market is expected to continue its rapid growth, driven by increasing energy demand and the need for infrastructure upgrades.
- The integration of renewable energy sources, such as solar and wind, will remain a key focus, driving demand for more advanced grid systems.
- Smart grid technologies, including automation and real-time monitoring, will become more widespread to enhance grid efficiency and reliability.
- Energy storage solutions will play an increasingly important role in stabilizing grids and supporting renewable energy integration.
- Government initiatives and regulatory frameworks promoting clean energy and sustainability will encourage further investments in grid modernization.
- The adoption of artificial intelligence and machine learning in grid management will enhance predictive capabilities and operational efficiency.
- Utilities will increasingly adopt demand response systems to manage energy consumption and reduce peak load demand.
- Public-private partnerships will become more common as governments and companies collaborate to modernize grid infrastructure.
- Cybersecurity will be a critical focus as grids become more connected and vulnerable to potential cyber threats.
- The market will see increased investments from both global players and regional companies to enhance grid resilience and support energy transitions across the region.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Asia Pacific Grid Modernization market?
What factors are driving the growth of the Asia Pacific Grid Modernization market?
What are the key segments within the Asia Pacific Grid Modernization market?
What are some challenges faced by the Asia Pacific Grid Modernization market?
Who are the major players in the Asia Pacific Grid Modernization market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Asia Pacific Grid Modernization Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Selected Region & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Asia Pacific Grid Modernization Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 12,683.42 million → 2032: USD 51,572.06 million)
- 2.1.2 Volume & Revenue – Regional Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Asia Pacific Grid Modernization Segmentation Snapshot
- 2.2.1 Market Split by Country – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Asia Pacific Grid Modernization Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Asia Pacific Grid Modernization Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Country
- 3.2 Asia Pacific Grid Modernization Drivers
- 3.3 Asia Pacific Grid Modernization Restraints & Challenges
- 3.4 Asia Pacific Grid Modernization Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Asia Pacific Grid Modernization Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Asia Pacific Grid Modernization Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regional & Country Regulatory Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Asia Pacific Grid Modernization category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Asia Pacific Grid Modernization Attractiveness Analysis
- 4.1.1 By Country – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Country – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Country – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Country Opportunity Scorecards
- 4.5.1 Priority Country 1
- 4.5.2 Priority Country 2
- 4.5.3 Priority Country 3
- 4.5.4 Priority Country 4
Note: Priority countries are selected from within the region covered by the study. Numbered entries are indicative and are populated with relevant country names based on market size, growth potential, and strategic relevance.
Chapter 5. Asia Pacific Grid Modernization Cross-Border Trade & Market Access Analysis
- 5.1 Intra-Regional & Extra-Regional Trade Overview
- 5.1.1 Regional Export Value by Country (2024)
- 5.1.2 Regional Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Regional Import Value by Country (2024)
- 5.1.4 Regional Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: Cross-border analysis applies where relevant to Asia Pacific Grid Modernization. Country trade flows distinguish intra-regional activity from trade with markets outside the region. Regional external trade totals exclude intra-regional flows to avoid double counting. Classifications and transaction measures follow the market scope; volume and route analyses apply only where meaningful.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Asia Pacific Grid Modernization Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Asia Pacific Grid Modernization Share Analysis – 2024
- 6.2.1 Regional Revenue Share by Company
- 6.2.2 Regional Volume Share by Company (Volume Where Applicable)
- 6.2.3 Company Revenue Share by Country
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Regional Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Asia Pacific Grid Modernization Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Revenue Exposure by Country Within the Region
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Asia Pacific Grid Modernization (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Asia Pacific Grid Modernization
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Asia Pacific Grid Modernization – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Country Market Analysis – Regional Overview
- 8.1 Country Market Overview Within the Region
- 8.1.1 Country Volume Share Within the Region (Where Applicable)
- 8.1.2 Country Revenue Share Within the Region
- 8.1.3 Market Volume by Country (Where Applicable)
- 8.1.4 Market Revenue by Country
- 8.1.5 Country Forecasts Through 2032
- 8.2 Cross-Country Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. Asia Pacific Grid Modernization – Priority Country 1
Chapter 10. Asia Pacific Grid Modernization – Priority Country 2
Chapter 11. Asia Pacific Grid Modernization – Priority Country 3
Chapter 12. Asia Pacific Grid Modernization – Priority Country 4
Chapter 13. Asia Pacific Grid Modernization Company Profiles
- 13.1 [Company 01]
- 13.1.1 Company Overview
- 13.1.2 Key Management Personnel
- 13.1.3 Products & Services Portfolio
- 13.1.4 Financial Performance
- 13.1.5 Regional Market Focus & Country Presence
- 13.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 14. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 15. Research Methodology
- 15.1 Research Framework & Philosophy
- 15.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 15.3 Data Modeling – Country-Level Estimates & Regional Aggregation
- 15.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 15.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 15.6 Quality Control – Four-Layer Validation Framework
- 15.7 Limitations & Standard Assumptions
- 15.8 Disclaimer
