
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
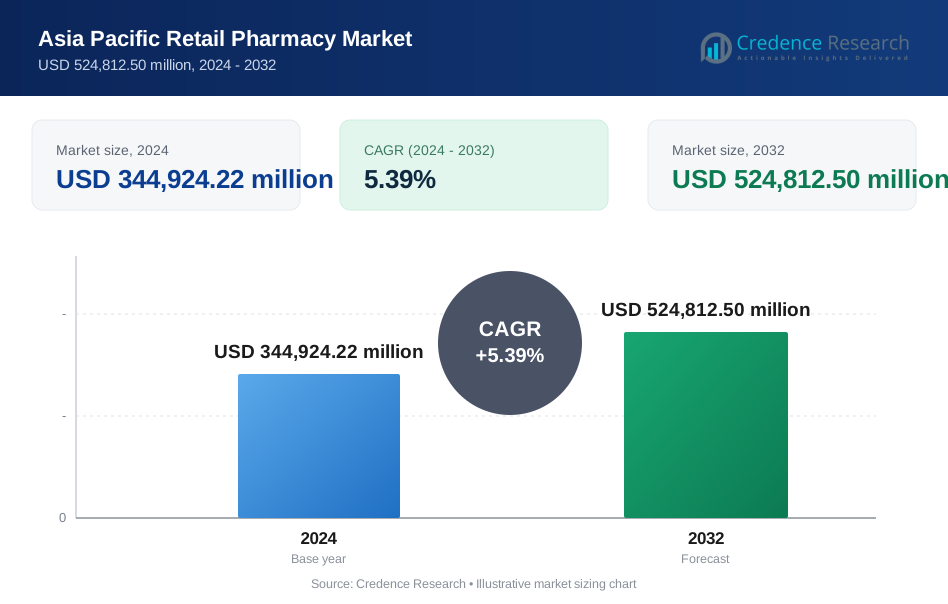
| Asia Pacific Retail Pharmacy Market Size 2024 | USD 344.9 billion |
| Asia Pacific Retail Pharmacy Market, CGR | 5.39% |
| Asia Pacific Retail Pharmacy Market Size 2032 | USD 524.8 billion |
Market Overview
The Asia Pacific Retail Pharmacy Market is projected to grow from USD 344.9 Billion in 2024 to an estimated USD 524.8 Billion by 2032, with a compound annual growth rate (CAGR) of 5.39% from 2025 to 2032. The market is experiencing robust growth due to the increasing demand for pharmaceutical products and services, driven by a larger, aging population, and growing awareness of health and wellness.
Key drivers of this market include the rise in demand for over-the-counter (OTC) medications, which offer consumers convenience and cost savings. Additionally, the expanding retail pharmacy chains in both urban and rural areas, along with improvements in healthcare infrastructure and government initiatives, are expected to further boost market growth. The growing popularity of e-pharmacy services, which offer home delivery of medications, is another major trend driving the retail pharmacy market in the region. The focus on customer-centric services, including personalized consultations and health screenings, is also contributing to the market’s expansion.
Geographically, the Asia Pacific region is witnessing varied growth trends, with countries such as China, India, and Japan leading the market due to their large populations and increasing healthcare investments. Key players in the market include pharmacy chains like Walgreens Boots Alliance, PharmaChoice, and local players such as MedPlus and Guardian Pharmacy, all competing to expand their presence and offerings in this rapidly growing sector.
Market Insights
- The Asia Pacific Retail Pharmacy Market is projected to grow from USD 344.9 Billion in 2024 to USD 524.8 Billion by 2032, at a CAGR of 5.39% from 2025 to 2032. The market is driven by increasing demand for pharmaceuticals, especially in response to aging populations and rising health awareness.
- The Global Retail Pharmacy Market is expected to grow from USD 1445.9 Billion in 2024 to USD 1965.9 Billion by 2032, at a CAGR of 3.92% from 2025 to 2032.
- Key drivers include the increasing demand for OTC medications, the growth of retail pharmacy chains in urban and rural areas, and government initiatives aimed at improving healthcare access. The rise of e-pharmacy services is another major factor driving market growth.
- High competition and regulatory hurdles in different countries may restrict market growth. Additionally, price sensitivity and the increasing presence of generic drugs may pressure profit margins for retail pharmacy chains.
- The rapid growth of e-pharmacy platforms is transforming the retail pharmacy landscape, offering consumers greater convenience through home delivery services and online consultations, thus expanding market reach and customer base.
- The increasing aging population, particularly in countries like Japan and South Korea, is a significant factor driving demand for prescription drugs and chronic disease management services offered by retail pharmacies.
- The market is dominated by East Asia, especially Japan and China, which account for a large share due to their large populations and substantial healthcare investments. Southeast Asia is also experiencing significant growth driven by rising healthcare awareness and expanding infrastructure.
- The market is competitive, with both global players like Walgreens Boots Alliance and local brands such as MedPlus and Guardian Pharmacy striving to expand their footprint. Retail pharmacies are increasingly diversifying services to include health consultations, chronic disease management, and wellness products.
Report Scope
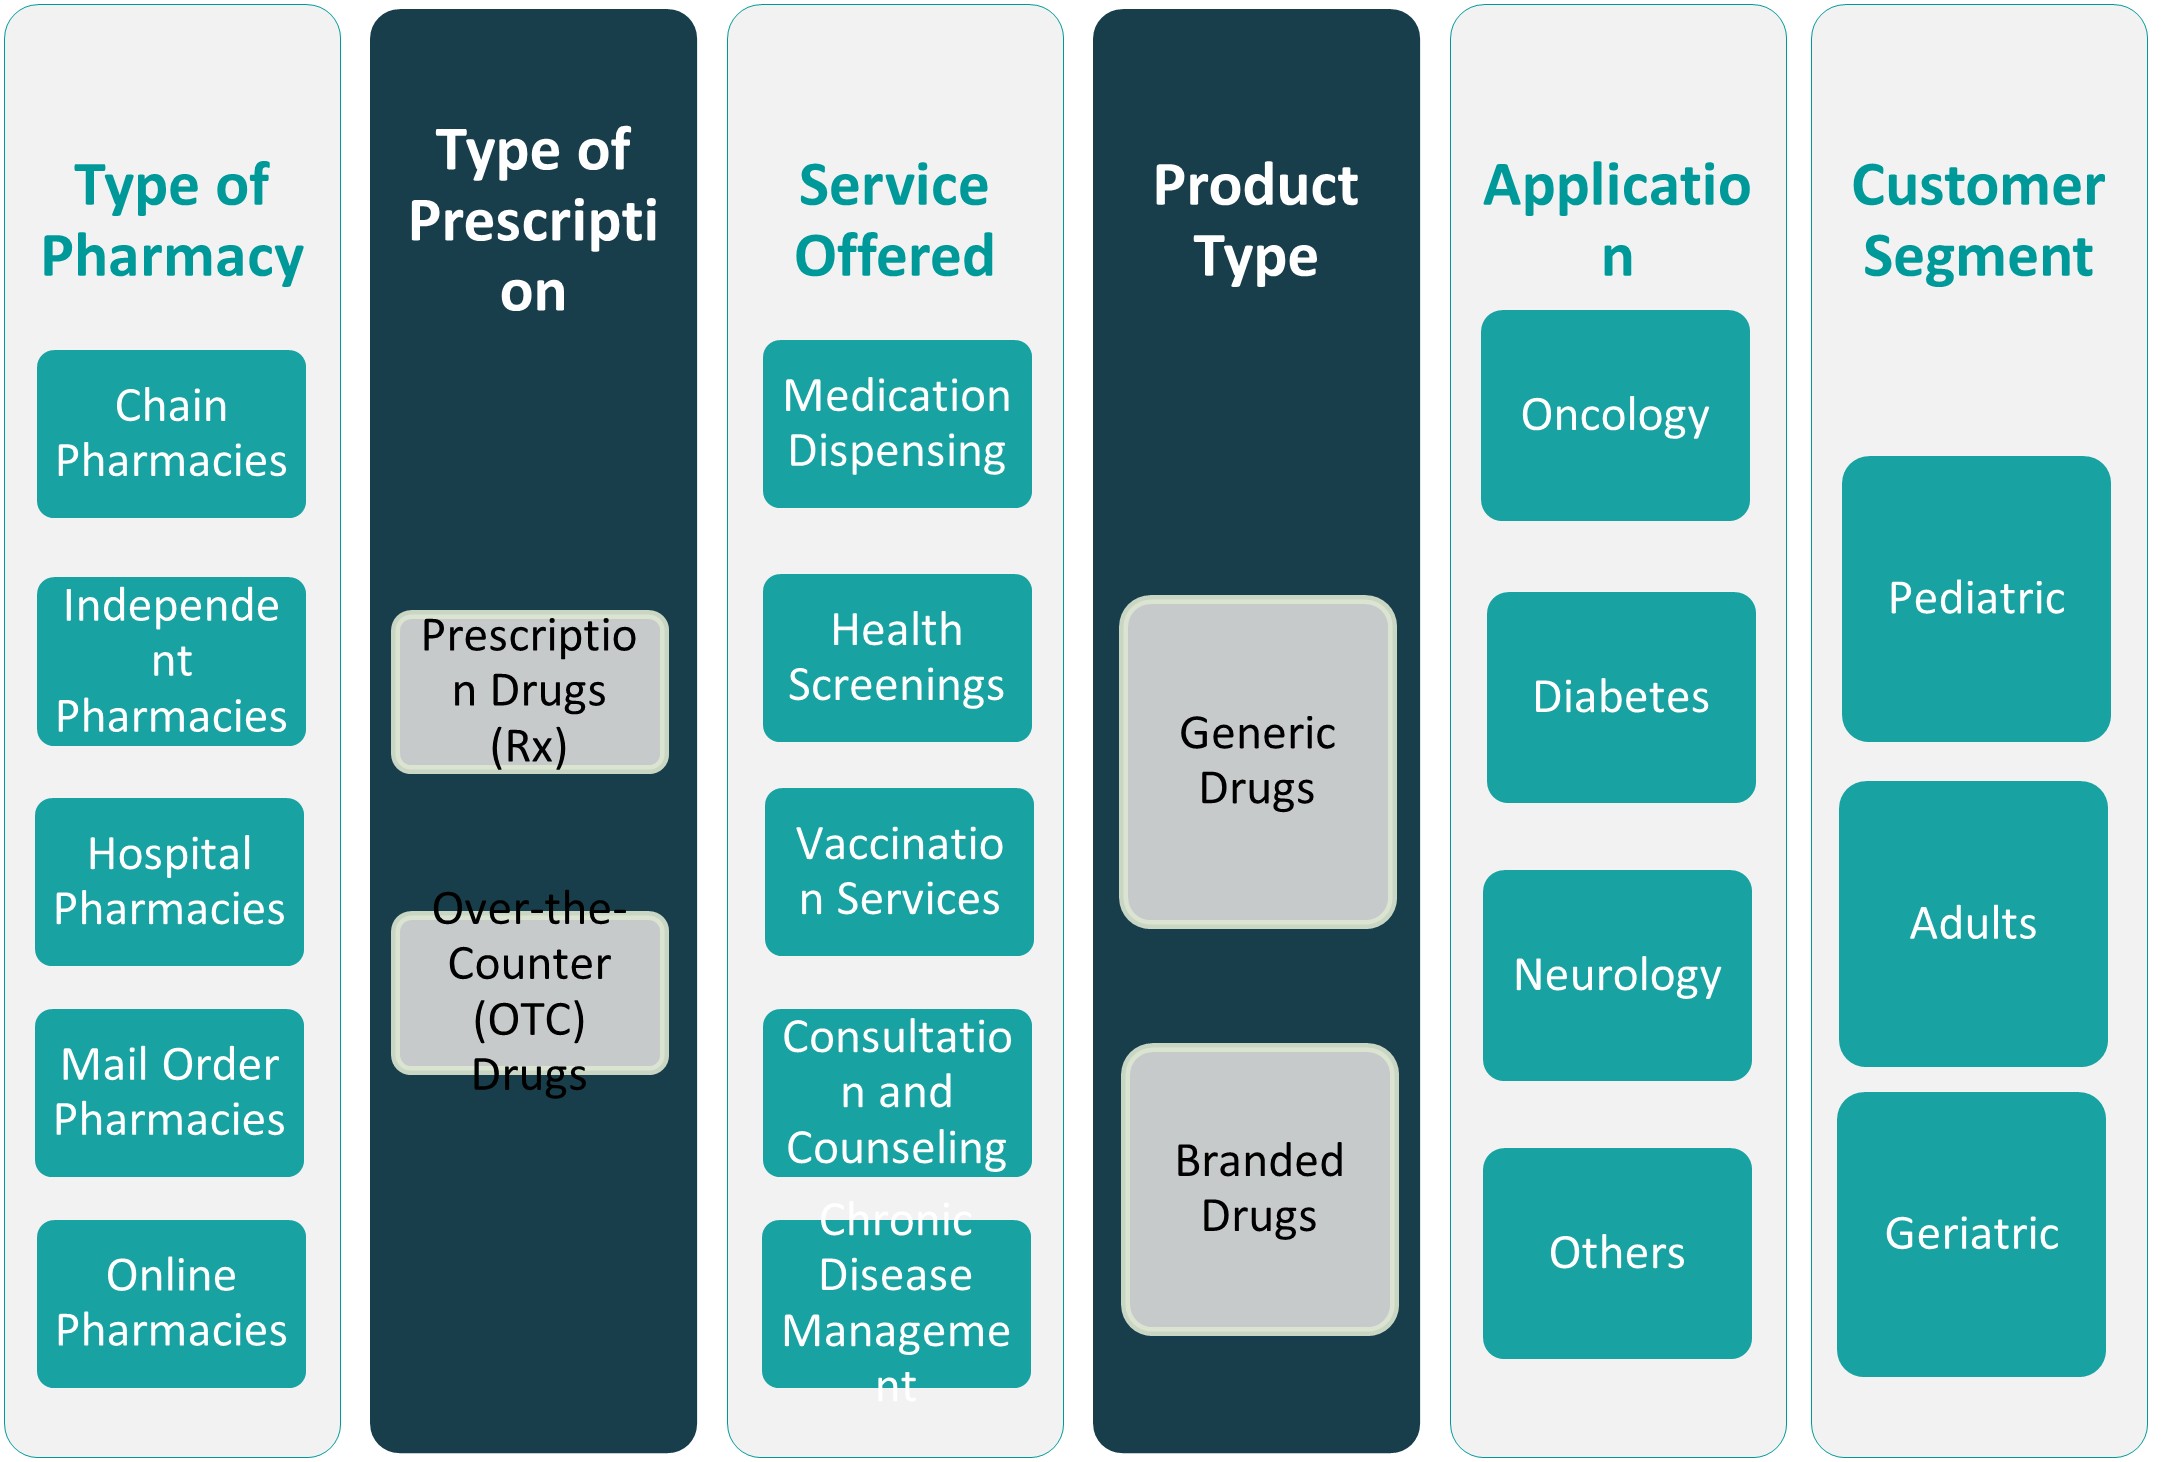
This report segments the Asia Pacific Retail Pharmacy Market as follows:
Market Drivers
Increased Adoption of E-Pharmacy and Digital Health Services
The growing adoption of e-pharmacy and digital health services is revolutionizing the retail pharmacy market in the Asia Pacific region. With the rise of internet connectivity, especially in urban areas, consumers are increasingly turning to online platforms for purchasing medications and healthcare products. The convenience of home delivery and the ability to easily compare prices are major factors contributing to the rapid growth of e-pharmacies. Moreover, the COVID-19 pandemic accelerated the shift toward online shopping for pharmaceuticals, as people sought to minimize in-person visits to physical stores.
In countries like India, China, and Australia, numerous e-pharmacy platforms have emerged, catering to the rising demand for online pharmaceutical services. These platforms also offer additional services such as telemedicine consultations, where consumers can consult doctors online before purchasing medications, enhancing the customer experience. The growing trend of digital health services, including online consultations, prescription refills, and health monitoring, is expected to contribute to the retail pharmacy market's growth by offering more convenience and accessibility to consumers.
Government Initiatives and Healthcare Reforms
Government policies and healthcare reforms play a crucial role in driving the growth of the retail pharmacy market in Asia Pacific. Several countries in the region are focusing on improving healthcare infrastructure and making medications more accessible to their populations. For example, in India, the government has been actively promoting the use of generic drugs through programs like Jan Aushadhi Yojana, which aims to make affordable medications available to the public.
Similarly, the Chinese government has been pushing for healthcare reforms that prioritize access to pharmaceuticals and medical services. These initiatives not only make medications more affordable but also ensure that retail pharmacies play a central role in meeting public healthcare needs. Additionally, regulations supporting the establishment and expansion of pharmacy chains in both urban and rural areas are encouraging investment in the retail pharmacy sector. The widespread adoption of insurance coverage in many parts of Asia Pacific is also driving demand for pharmacy services, as insured patients are more likely to seek regular medication refills and health consultations at retail pharmacies. These government-driven initiatives are expected to further fuel the demand for retail pharmacy services in the region.
Growing Population and Aging Demographics
The Asia Pacific region is home to some of the world's largest and fastest-growing populations. This demographic shift plays a crucial role in the expansion of the retail pharmacy market. For instance, Japan's aging population has reached over 36 million individuals aged 65 and above, accounting for nearly 29% of its total population. Similarly, South Korea reported that 17.5% of its population is aged 65 and older, highlighting the growing demand for healthcare services and medications.
According to UN estimates, the proportion of people aged 60 and above in Asia is expected to rise significantly over the coming decades, particularly in countries like China, where the elderly population is projected to exceed 400 million by 2040. Retail pharmacies are pivotal in providing easy access to medications, making them an essential part of the healthcare infrastructure. The increasing healthcare needs of this demographic, alongside government initiatives such as Japan's "Community Pharmacy Vision," which aims to enhance pharmacy services for the elderly, are driving the demand for retail parmacy services in the region.
Growing Prevalence of Chronic Diseases
The rise in chronic diseases, such as diabetes, cardiovascular disorders, and respiratory conditions, is another primary driver for the Asia Pacific Retail Pharmacy Market. For instance, India has over 77 million individuals diagnosed with diabetes, making it one of the highest diabetes-burdened countries globally. Similarly, China reported that approximately 116 million adults suffer from diabetes, further increasing the demand for medications and healthcare services. Retail pharmacies are positioned as essential points for the management of these long-term conditions. Many retail pharmacies in Southeast Asia have introduced wellness programs and monitoring services, such as blood glucose tracking, to support patients with chronic diseases. These services improve the customer experience and drive continued engagement, further boosting market growth.
Market Trends
Growing Demand for Personalized Medicine and Health Consultations
The demand for personalized medicine and health consultations is another significant trend in the Asia Pacific retail pharmacy market. With increasing awareness about preventive healthcare and wellness, consumers are now seeking more tailored healthcare solutions. Retail pharmacies are responding by offering personalized medication counseling, health screenings, and wellness services.
Pharmacies are also collaborating with healthcare professionals to provide customized solutions based on individual health needs. For instance, some pharmacies are offering genetic testing to personalize drug prescriptions, ensuring optimal treatment plans based on a patient’s unique genetic makeup. Additionally, pharmacists are increasingly offering counseling services to help patients manage chronic diseases such as diabetes and hypertension. As consumers continue to prioritize health and wellness, the trend of personalized pharmacy services is expected to strengthen, particularly in urban areas with higher health awareness.
Focus on OTC Medications and Wellness Products
A growing trend in the Asia Pacific retail pharmacy market is the increasing demand for over-the-counter (OTC) medications and wellness products. With rising awareness about health and self-care, consumers are more inclined to purchase OTC medications for common ailments like headaches, colds, and digestive issues. Pharmacies are expanding their offerings of OTC medications, dietary supplements, vitamins, and other wellness products to meet the growing consumer demand. This trend is fueled by the increasing preference for self-medication, convenience, and cost-effectiveness.
As consumers become more proactive in managing their health, they are also turning to pharmacies for products that promote overall well-being, such as immunity boosters, natural remedies, and fitness supplements. The rise in health-conscious consumers, coupled with the growing acceptance of self-care and preventive healthcare, positions the retail pharmacy market to benefit from the expanding sales of OTC products, making this segment a key focus area for many pharmacy chains.
Expansion of E-Pharmacy and Online Platforms
One of the most notable trends in the Asia Pacific Retail Pharmacy Market is the significant expansion of e-pharmacy platforms. The increasing use of smartphones and improved internet connectivity across the region has enabled more consumers to access pharmaceuticals and healthcare services online. For instance, PharmEasy in India reported processing over 2 million orders monthly in 2024, showcasing the growing reliance on e-pharmacy platforms.
E-pharmacies provide the convenience of home delivery, competitive pricing, and access to a wide range of medications, which appeals to a tech-savvy consumer base. The COVID-19 pandemic further accelerated this trend as consumers preferred online shopping to reduce in-person visits to physical stores. These platforms are also integrating advanced technologies, such as artificial intelligence (AI), for personalized health recommendations and real-time medication tracking. The convenience of e-pharmacy, combined with its growing accessibility, is reshaping the retail pharmacy market, and the trend is expected to continue its upward trajectory.
Integration of Telehealth and In-Store Services
Another key trend in the Asia Pacific retail pharmacy market is the integration of telehealth and in-store pharmacy services. As consumers seek more personalized and convenient healthcare experiences, retail pharmacies are offering value-added services, including telemedicine consultations. For example, Matsumotokiyoshi in Japan reported conducting over 500,000 telehealth consultations in 2023, highlighting the growing adoption of these services. These services not only improve customer engagement but also create an efficient, one-stop-shop for healthcare needs.
The rise in chronic diseases and the aging population have further fueled the demand for such integrated services, allowing pharmacies to play a more active role in patient care management. This trend is particularly beneficial in rural or underserved areas where access to healthcare professionals may be limited. As healthcare continues to sift toward more patient-centric and integrated care, pharmacies are positioning themselves as key players in delivering both pharmaceutical and healthcare services.
Market Challenges
Regulatory and Compliance Issues
One of the significant challenges facing the Asia Pacific retail pharmacy market is the complex and varied regulatory environment across different countries in the region. Each country has its own set of rules governing the sale of pharmaceuticals, over-the-counter (OTC) medications, and health products, making it challenging for retail pharmacies to navigate these diverse regulatory requirements. For instance, in India, the Drugs and Cosmetics Act regulates the sale of pharmaceuticals, while Japan enforces strict guidelines under the Pharmaceutical and Medical Device Act, which includes detailed requirements for product labeling and advertising.
In some countries, stringent regulations related to the sale and distribution of pharmaceuticals, including restrictions on e-pharmacies and online medication sales, can limit market growth. Additionally, there are varying standards for product labeling, advertising, and quality control across the region, which can lead to compliance challenges for pharmacy chains that operate in multiple markets. Non-compliance with these regulations could result in legal repercussions, financial penalties, and damage to a company’s reputation.
Furthermore, the regulatory landscape for digital health services and e-pharmacies is still evolving in many countries, creating uncertainty for market players who are looking to expand their online platforms and telemedicine offerings. As governments in the region continue to tighten healthcare regulations, retail pharmacies must invest in compliance mechanisms and stay updated on changing laws, which can increase operational costs and complexity.
Intense Competition and Price Pressure
The Asia Pacific retail pharmacy market is characterized by intense competition, with numerous local and international players vying for market share. The presence of both large retail pharmacy chains and smaller, independent pharmacies results in price wars, particularly in OTC medications, which can erode profit margins. Additionally, the growing trend of e-pharmacies and online platforms has introduced further competition for traditional brick-and-mortar pharmacies.
E-pharmacies can often offer lower prices and more convenient services, such as home delivery and online consultations, which make them attractive to a broader customer base. This price pressure is particularly acute in price-sensitive markets like India, where consumers are highly price-conscious and often opt for generic medications over branded options. As a result, traditional pharmacies face challenges in differentiating themselves and maintaining customer loyalty in the face of price competition. Retail pharmacies must continuously innovate by offering value-added services, such as personalized consultations, wellness programs, and home delivery, to stay competitive. However, this requires substantial investment in technology, infrastructure, and customer service, further increasing operational costs.
Market Opportunities
Expansion of E-Pharmacy and Digital Health Services
One of the most significant opportunities in the Asia Pacific retail pharmacy market lies in the rapid growth of e-pharmacy and digital health services. With increasing internet penetration and a growing preference for convenience, e-pharmacies are poised to revolutionize the retail pharmacy landscape. Consumers are increasingly turning to online platforms for the purchase of pharmaceuticals, health supplements, and wellness products, particularly in urban areas where digital infrastructure is robust.
Retail pharmacies can capitalize on this shift by developing user-friendly e-commerce platforms, offering home delivery services, and integrating telemedicine consultations to provide holistic healthcare solutions. The convenience, accessibility, and lower costs associated with e-pharmacies present a strong growth opportunity. Additionally, the growing trend of digital health services, such as online health monitoring, prescription refills, and virtual consultations, is further expanding the market potential. Retail pharmacies that invest in these digital innovations are likely to capture a larger market share by catering to the evolving needs of tech-savvy consumers.
Rising Demand for Preventive Healthcare and Wellness Products
As consumers become increasingly health-conscious, there is a rising demand for preventive healthcare and wellness products. This presents a significant opportunity for retail pharmacies to diversify their offerings beyond traditional pharmaceuticals to include vitamins, dietary supplements, fitness products, and natural remedies. The growing awareness of healthy living, particularly in countries like Japan, South Korea, and Australia, is driving this trend.
Retail pharmacies can tap into this opportunity by expanding their product ranges to include wellness and preventive health products, creating specialized health and wellness sections in their stores, or even offering personalized health consultations. Additionally, partnerships with local wellness brands or global health and fitness companies can help pharmacies cater to the growing consumer interest in maintaining overall health and well-being. This shift toward preventive care offers long-term growth potential for retail pharmacies, particularly as consumers prioritize self-care and proactive health management.
Market Segmentation Analysis
By Type of Pharmacy
The Asia Pacific retail pharmacy market can be broadly segmented based on the type of pharmacy. Chain pharmacies are the dominant segment, particularly in urban areas, where they benefit from economies of scale, wide product offerings, and increased accessibility. These pharmacies often have a nationwide presence, such as those seen in countries like Japan and Australia, and are characterized by standardized services and significant brand recognition. Independent pharmacies, on the other hand, play a vital role in rural and underserved areas, offering personalized services and a more tailored approach to customer needs.
Hospital pharmacies serve patients within healthcare settings, dispensing medications prescribed during hospital stays, and are generally a part of larger healthcare institutions. Additionally, mail-order pharmacies are gaining traction in markets with increasing demand for convenience, particularly in countries like India and China. These pharmacies offer the advantage of home delivery and greater access to medications in remote locations. Online pharmacies have also witnessed tremendous growth, driven by the shift toward e-commerce and consumer preference for home delivery and telemedicine services. This segment is expected to continue growing as digital platforms offer consumers easier access to medications and healthcare products.
By Type of Prescription
The market is also segmented by the type of prescription. Prescription drugs (Rx) remain a significant component, with a steady demand driven by the increasing prevalence of chronic diseases, an aging population, and the growing need for specialized treatments. The growth in the prescription segment is also supported by government initiatives promoting healthcare accessibility. In contrast, over-the-counter (OTC) drugs have seen an uptick in demand as consumers become more proactive about their health, seeking solutions for minor ailments and preventive care. This demand is amplified by the rise in self-medication, the availability of a broader range of OTC products, and the increasing consumer awareness of non-prescription alternatives for common health concerns.
Segments
Based on Type of Pharmacy
- Chain Pharmacies
- Independent Pharmacies
- Hospital Pharmacies
- Mail Order Pharmacies
- Online Pharmacies
Based on Type of prescription
- Prescription Drugs (Rx)
- Over-the-Counter (OTC) Drugs
Based on Service offered
- Medication Dispensing
- Health Screenings
- Vaccination Services
- Consultation and Counseling
- Chronic Disease Management
Based on Product Type
- Generic Drugs
- Branded Drugs
Based on Application
- Oncology
- Diabetes
- Neurology
- Others
Based on Customer
- Paediatric
- Adults
- Geriatric
Based on Region
- East Asia
- Southeast Asia
- South Asia
- Australia and New Zealand
- Other Regions
Regional Analysis
East Asia (35%)
East Asia, particularly Japan and South Korea, holds the largest share of the retail pharmacy market in the region, accounting for approximately 35% of the total market. Japan, with its aging population, is a major contributor to the market's growth, as elderly individuals require more medications and healthcare services. The market is further supported by the advanced healthcare infrastructure and government initiatives aimed at improving access to pharmaceuticals. In South Korea, a similar demographic trend, combined with high urbanization and a tech-savvy population, is driving growth in both traditional and digital pharmacy segments. E-pharmacies and digital health services are also gaining momentum in this region, enhancing the overall market potential.
Southeast Asia (25%)
Southeast Asia holds about 25% of the market share in the Asia Pacific retail pharmacy sector. The region's large and rapidly growing population, combined with rising healthcare awareness, is driving demand for pharmaceuticals and pharmacy services. Countries such as Indonesia, Thailand, and Malaysia are experiencing rapid urbanization, which increases access to retail pharmacy services. Moreover, the expansion of healthcare infrastructure and the increasing prevalence of chronic diseases, such as diabetes and hypertension, are contributing to market growth. E-pharmacies are also seeing notable adoption in urban centers, and there is increasing investment in both public and private healthcare sectors to improve pharmaceutical accessibility in rural areas.
Key players
- CK Life Sciences
- MedPlus
- Watsons
- Apollo Pharmacy
- 7-Eleven
Competitive Analysis
The Asia Pacific retail pharmacy market is highly competitive, with both regional and international players vying for market share. Companies like CK Life Sciences leverage extensive product portfolios and strategic business models, focusing on both traditional and digital pharmacy services. MedPlus, one of the leading retail pharmacy chains in India, capitalizes on its wide network of stores and a strong focus on providing affordable medications.
Watsons, a well-established brand across East Asia, differentiates itself through a broad range of healthcare and wellness products and an expanding e-commerce presence. Apollo Pharmacy, part of the Apollo Hospitals Group, stands out with its integrated healthcare services, offering a seamless blend of pharmaceutical and healthcare offerings. Lastly, 7-Eleven is gaining traction in convenience pharmacy services, expanding its footprint in urban areas. The competition is intensifying as companies adopt digitalization, expand service offerings, and focus on customer convenience to stay ahead in the market.
Recent Developments
- In April 2026, Lotus Pharmaceutical announced an agreement to acquire Sandoz AG’s Philippines business, strengthening its Southeast Asia presence through a generics and biosimilars portfolio and expanding its local commercial capabilities in the Philippines.
- In April 2026, BIG CARiNG Group launched a telehealth kiosk for the Bandar Tun Razak community in Malaysia, reflecting retail pharmacy’s continued shift toward accessible digital health and community-based primary-care services.
- In March 2026, Watsons International marked International Women’s Day by spotlighting women-made products and women-led brands across its Asian and European retail network, positioning its stores as platforms for purpose-led health and beauty retailing.
- In January 2026, AS Watson committed to a major 2026 store rollout plan, including new store openings across its health, beauty, and personal care retail formats, reinforcing expansion momentum for Watsons and related pharmacy-led retail banners in Asia.
Market Concentration and Characteristics
The Asia Pacific retail pharmacy market is moderately concentrated, with a mix of large, well-established pharmacy chains and smaller, independent pharmacies. Key players like Watsons, Apollo Pharmacy, and MedPlus dominate the market in terms of both market share and geographic presence, particularly in urban areas. These large pharmacy chains benefit from economies of scale, extensive distribution networks, and strong brand recognition. However, the market also features a significant number of independent pharmacies, particularly in rural and underserved regions, offering personalized services to cater to local needs.
The market is characterized by increasing competition from e-pharmacies and online platforms, which are reshaping the retail landscape by offering greater convenience, home delivery, and telemedicine services. As consumer demand for both traditional and digital healthcare solutions grows, the market is experiencing a shift towards service diversification, with pharmacies expanding into wellness products, health screenings, and chronic disease management. The overall market structure is evolving, driven by innovation, regulatory support, and the growing trend of digital healthcare integration.
Report Coverage
The research report offers an in-depth analysis based on Type of Pharmacy, Type of prescription, Service offered, Product Type, Application, Customer and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- E-pharmacy platforms are expected to see continued expansion due to growing internet penetration and the convenience of online services. The shift toward digital healthcare and home delivery services will drive this growth.
- Consumers are increasingly focusing on preventive healthcare, which will lead to greater demand for wellness products, vitamins, and health screenings. Retail pharmacies are poised to capitalize on this growing trend.
- With an aging population across key markets like Japan, South Korea, and China, the demand for pharmaceutical services, especially for chronic disease management, will significantly increase. This demographic shift presents a long-term growth opportunity for pharmacies.
- Government policies promoting affordable healthcare and pharmaceutical accessibility will continue to shape the market. Regulations supporting generic drug use will drive growth, particularly in price-sensitive markets like India.
- Retail pharmacies are likely to expand their service offerings, including telemedicine consultations, vaccination services, and chronic disease management programs. This diversification will strengthen their role in integrated healthcare.
- The demand for over-the-counter (OTC) medications is expected to rise, driven by increasing consumer awareness of self-care and minor health concerns. Pharmacies willcontinue to expand their OTC product ranges to meet this demand.
- The integration of digital health technologies, such as AI for personalized health recommendations, will enhance pharmacy services. Retail pharmacies will adopt these innovations to improve customer engagement and care quality.
- As retail pharmacy chains expand into rural and underserved areas, accessibility to essential medications will increase. This expansion will be supported by government initiatives and growing e-pharmacy presence.
- Larger retail pharmacy chains will continue to consolidate market share through mergers, acquisitions, and partnerships. This trend will enable these players to strengthen their competitive position and expand their service offerings.
- Sustainability will become a key focus, with retail pharmacies adopting eco-friendly packaging and promoting green initiatives. This aligns with the growing consumer preference for environmentally conscious brands.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of E-Pharmacy and Digital Health Services
The rapid adoption of e-pharmacy platforms and digital health services is transforming the retail pharmacy landscape in Asia Pacific, offering consumers convenient access to medications, home delivery, and telemedicine consultations. This shift is driven by increasing internet penetration and changing consumer preferences, especially in urban areas.
Government Initiatives and Healthcare Reforms
Proactive government policies and healthcare reforms across countries like India and China are improving access to affordable medications and supporting the expansion of pharmacy chains. These initiatives include promoting generic drug use, expanding insurance coverage, and investing in healthcare infrastructure.
Aging Population and Chronic Disease Prevalence
The region's large and growing elderly population, particularly in Japan, South Korea, and China, is driving sustained demand for prescription medications and chronic disease management services. Retail pharmacies are essential in meeting the healthcare needs of this demographic shift.
Rising Demand for OTC Medications and Wellness Products
Increasing health awareness and a preference for self-care are fueling demand for over-the-counter medications, dietary supplements, and wellness products. Pharmacies are expanding their OTC and wellness offerings to cater to proactive, health-conscious consumers.
Retail Pharmacy Chain Expansion into Rural and Underserved Areas
Major pharmacy chains are extending their reach into rural and underserved regions, improving accessibility to essential medications and healthcare services. This expansion is supported by government efforts and the growing presence of e-pharmacy platforms, bridging gaps in healthcare delivery.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
is the market size of the Asia Pacific Retail Pharmacy Market in 2023 and 2032?
What factors are driving the growth of the Asia Pacific Retail Pharmacy Market?
How are e-pharmacy services influencing the retail pharmacy market?
What are the key players in the Asia Pacific Retail Pharmacy Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Service Offered
- 1.2.1 Medication Dispensing
- 1.2.2 Health Screenings
- 1.2.3 Vaccination Services
- 1.2.4 Consultation and Counseling
- 1.2.5 Chronic Disease Management
- 1.3 By Type of Pharmacy
- 1.3.1 Chain Pharmacies
- 1.3.2 Independent Pharmacies
- 1.3.3 Hospital Pharmacies
- 1.3.4 Mail Order Pharmacies
- 1.3.5 Online Pharmacies
- 1.4 By Type of Prescription
- 1.4.1 Prescription Drugs (Rx)
- 1.4.2 Over-the-Counter (OTC) Drugs
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 344,924.22 million → 2032: USD 524,812.50 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Asia Pacific Retail Pharmacy Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Asia Pacific Retail Pharmacy Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Asia Pacific Retail Pharmacy Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Asia Pacific Retail Pharmacy Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Asia Pacific Retail Pharmacy Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Asia Pacific Retail Pharmacy Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Asia Pacific Retail Pharmacy Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Asia Pacific Retail Pharmacy Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 344,924.22 million → 2032: USD 524,812.50 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Asia Pacific Retail Pharmacy Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Service Offered - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Medication Dispensing
- 12.3.7.2 Health Screenings
- 12.3.7.3 Vaccination Services
- 12.3.7.4 Consultation and Counseling
- 12.3.7.5 Chronic Disease Management
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Type of Pharmacy - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Chain Pharmacies
- 12.4.7.2 Independent Pharmacies
- 12.4.7.3 Hospital Pharmacies
- 12.4.7.4 Mail Order Pharmacies
- 12.4.7.5 Online Pharmacies
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Type of Prescription - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Prescription Drugs (Rx)
- 12.5.7.2 Over-the-Counter (OTC) Drugs
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Asia Pacific Retail Pharmacy Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Country-Level Shares, 2024
- 13.2 Country Market Size Comparison, 2024
- 13.3 Country Market Forecasts, 2024-2032
- 13.4 Subregional Industrial and Demand Clusters
- 13.5 Intra-Regional Pricing and Cost Differences
- 13.6 Cross-Border Trade and Supply Networks
- 13.7 Regional Supply and Demand Balances
- 13.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 14 Asia Pacific Retail Pharmacy Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Asia Pacific Retail Pharmacy Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 CK Life Sciences
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 MedPlus
- 17.4 Watsons
- 17.5 Apollo Pharmacy
- 17.6 7-Eleven
- 17.7 Guardian Pharmacy
- 17.8 Walgreens Boots Alliance
- 17.9 PharmaChoice
- 17.10 Matsumotokiyoshi
- 17.11 Lotus Pharmaceutical
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

