
Korean skincare moves from niche imports to mass shelves
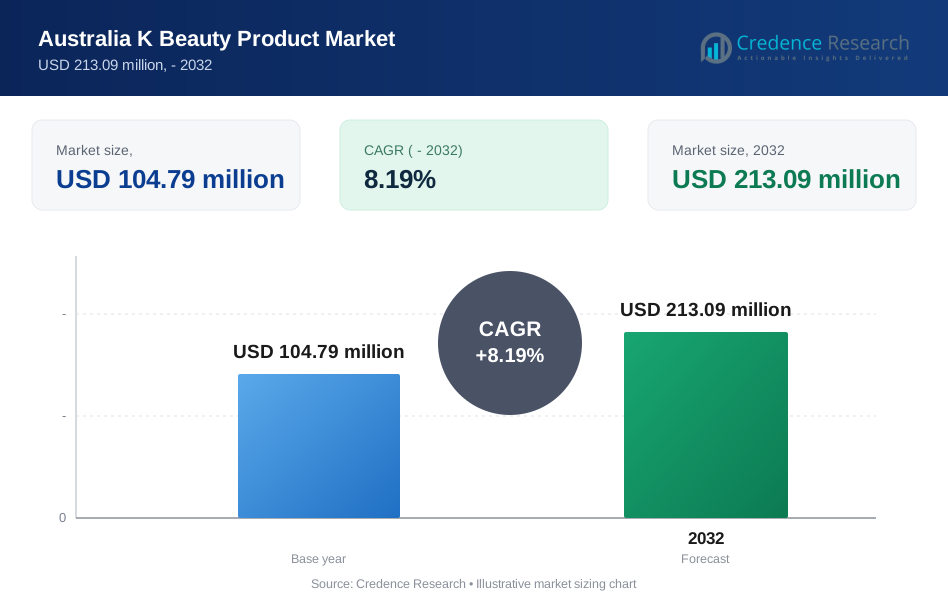
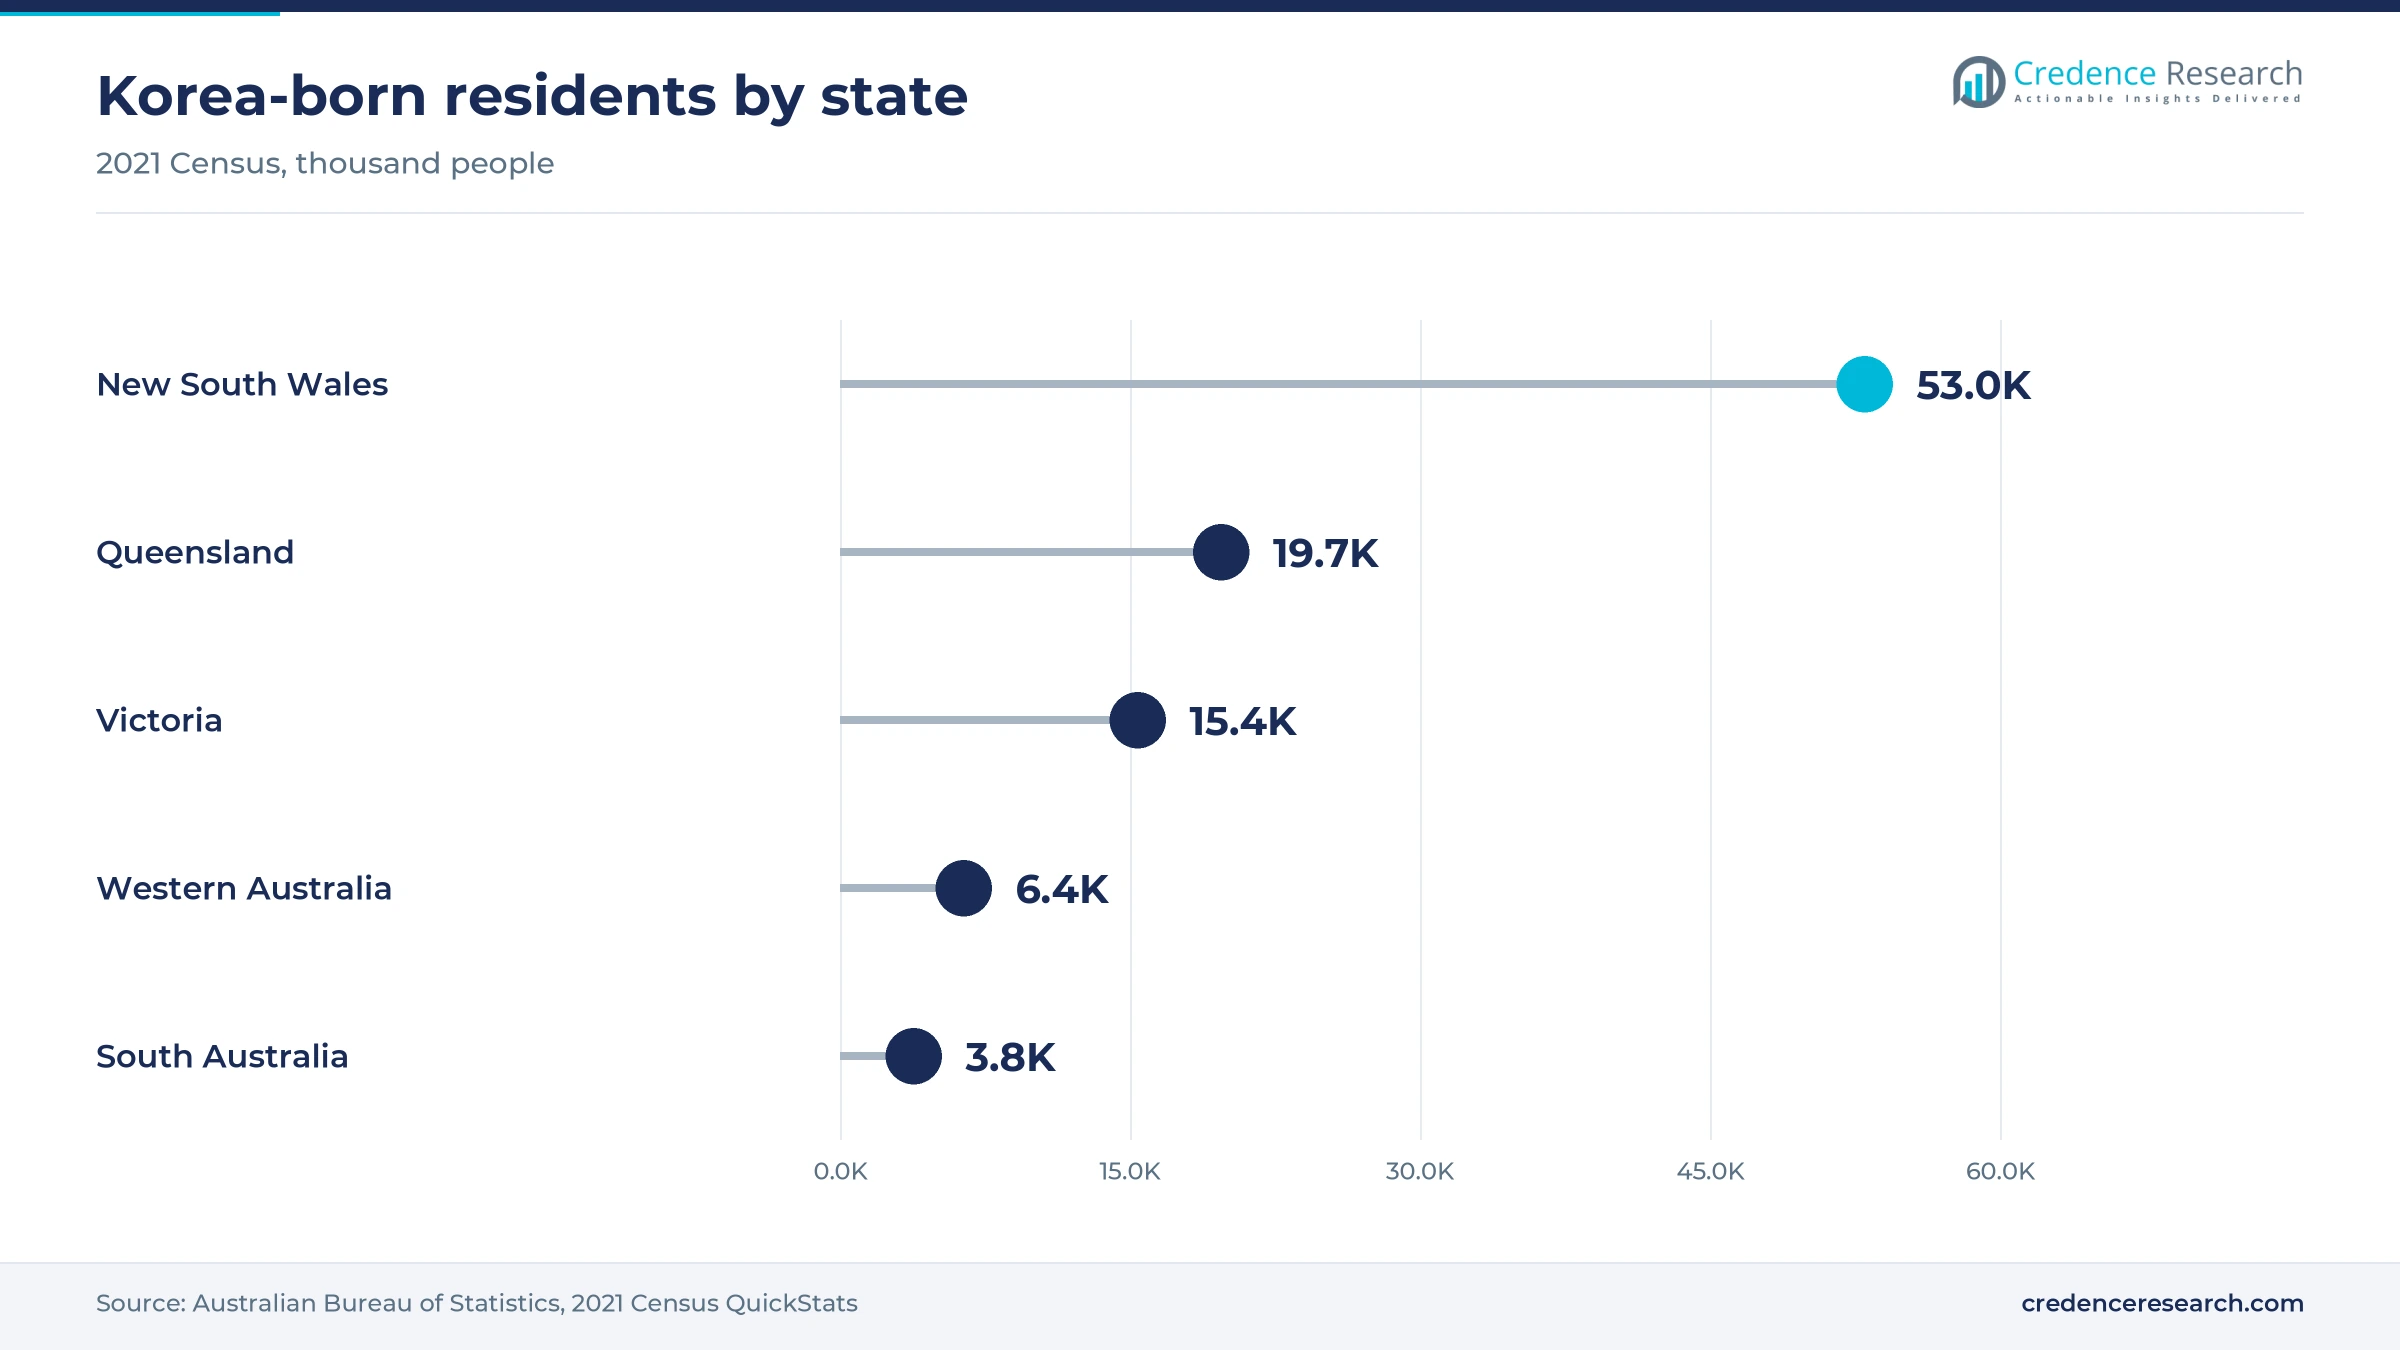
The Australia K beauty product market was valued at USD 238.5 million in 2025 and is projected to increase from USD 258.0 million in 2026 to USD 524.0 million by 2035, registering a CAGR of 8.19% during 2026–2035. Demand comes from Korean skincare and makeup sold through online stores, specialty beauty chains, pharmacies and, from 2026, grocery chains, while South Korea shipped USD 166.0 million of cosmetics to Australia in 2025, up 48.7% on 2024. New South Wales held the largest regional share, 36.0% in 2025, because the state was home to 53,046 of the 102,092 Korea-born residents counted in the 2021 Census. Western Australia is the fastest-growing region at 8.9% a year, as its population grew 2.2% in the year to June 2025. The channel mix is also changing, because Beauty of Joseon entered Coles supermarkets nationwide in August 2026 as the first Korean brand stocked by the chain.
Which Korean-brand beauty sales count toward this estimate?
The estimate measures the retail sales value of skincare, sun care and color cosmetics sold in Australia under South Korean brands, whether shoppers buy them in stores, on Australian websites or from overseas platforms that ship to Australian addresses. It covers moisturizers, serums and essences, cleansers, sheet masks, sunscreens and other items such as toners, lip care and makeup.
The estimate excludes products made in South Korea under contract for Australian or Western brands, professional aesthetic treatments and injectables. The value chain runs from Korean brand owners and contract manufacturers through importers and distributors to retailers such as Sephora, Mecca, Priceline Pharmacy, W Cosmetics and Coles.
Australia K Beauty Product Market Insights
- The Australia K beauty product market was valued at USD 238.5 million in 2025 and is projected to reach USD 524.0 million by 2035, registering a CAGR of 8.19% during 2026–2035.
- New South Wales held a 36.0% share of 2025 value, because more than half of Australia's Korea-born residents lived in the state at the 2021 Census.
- Moisturizers led with a 24.0% share of 2025 value, because barrier creams close every Korean routine and sell at higher prices than masks or toners.
- Australia imported USD 76.36 million of Korean skin care and makeup preparations in 2023, making Korea the third-largest supplier after the United States and France.
- Serums and essences grow fastest at 9.1% a year during 2026–2035, as hero serums from Korean brands moved from online sellers into supermarket aisles in 2026.
Moisturizers and online sales lead Korean beauty spend
Why do moisturizers lead Korean skincare sales in Australia?
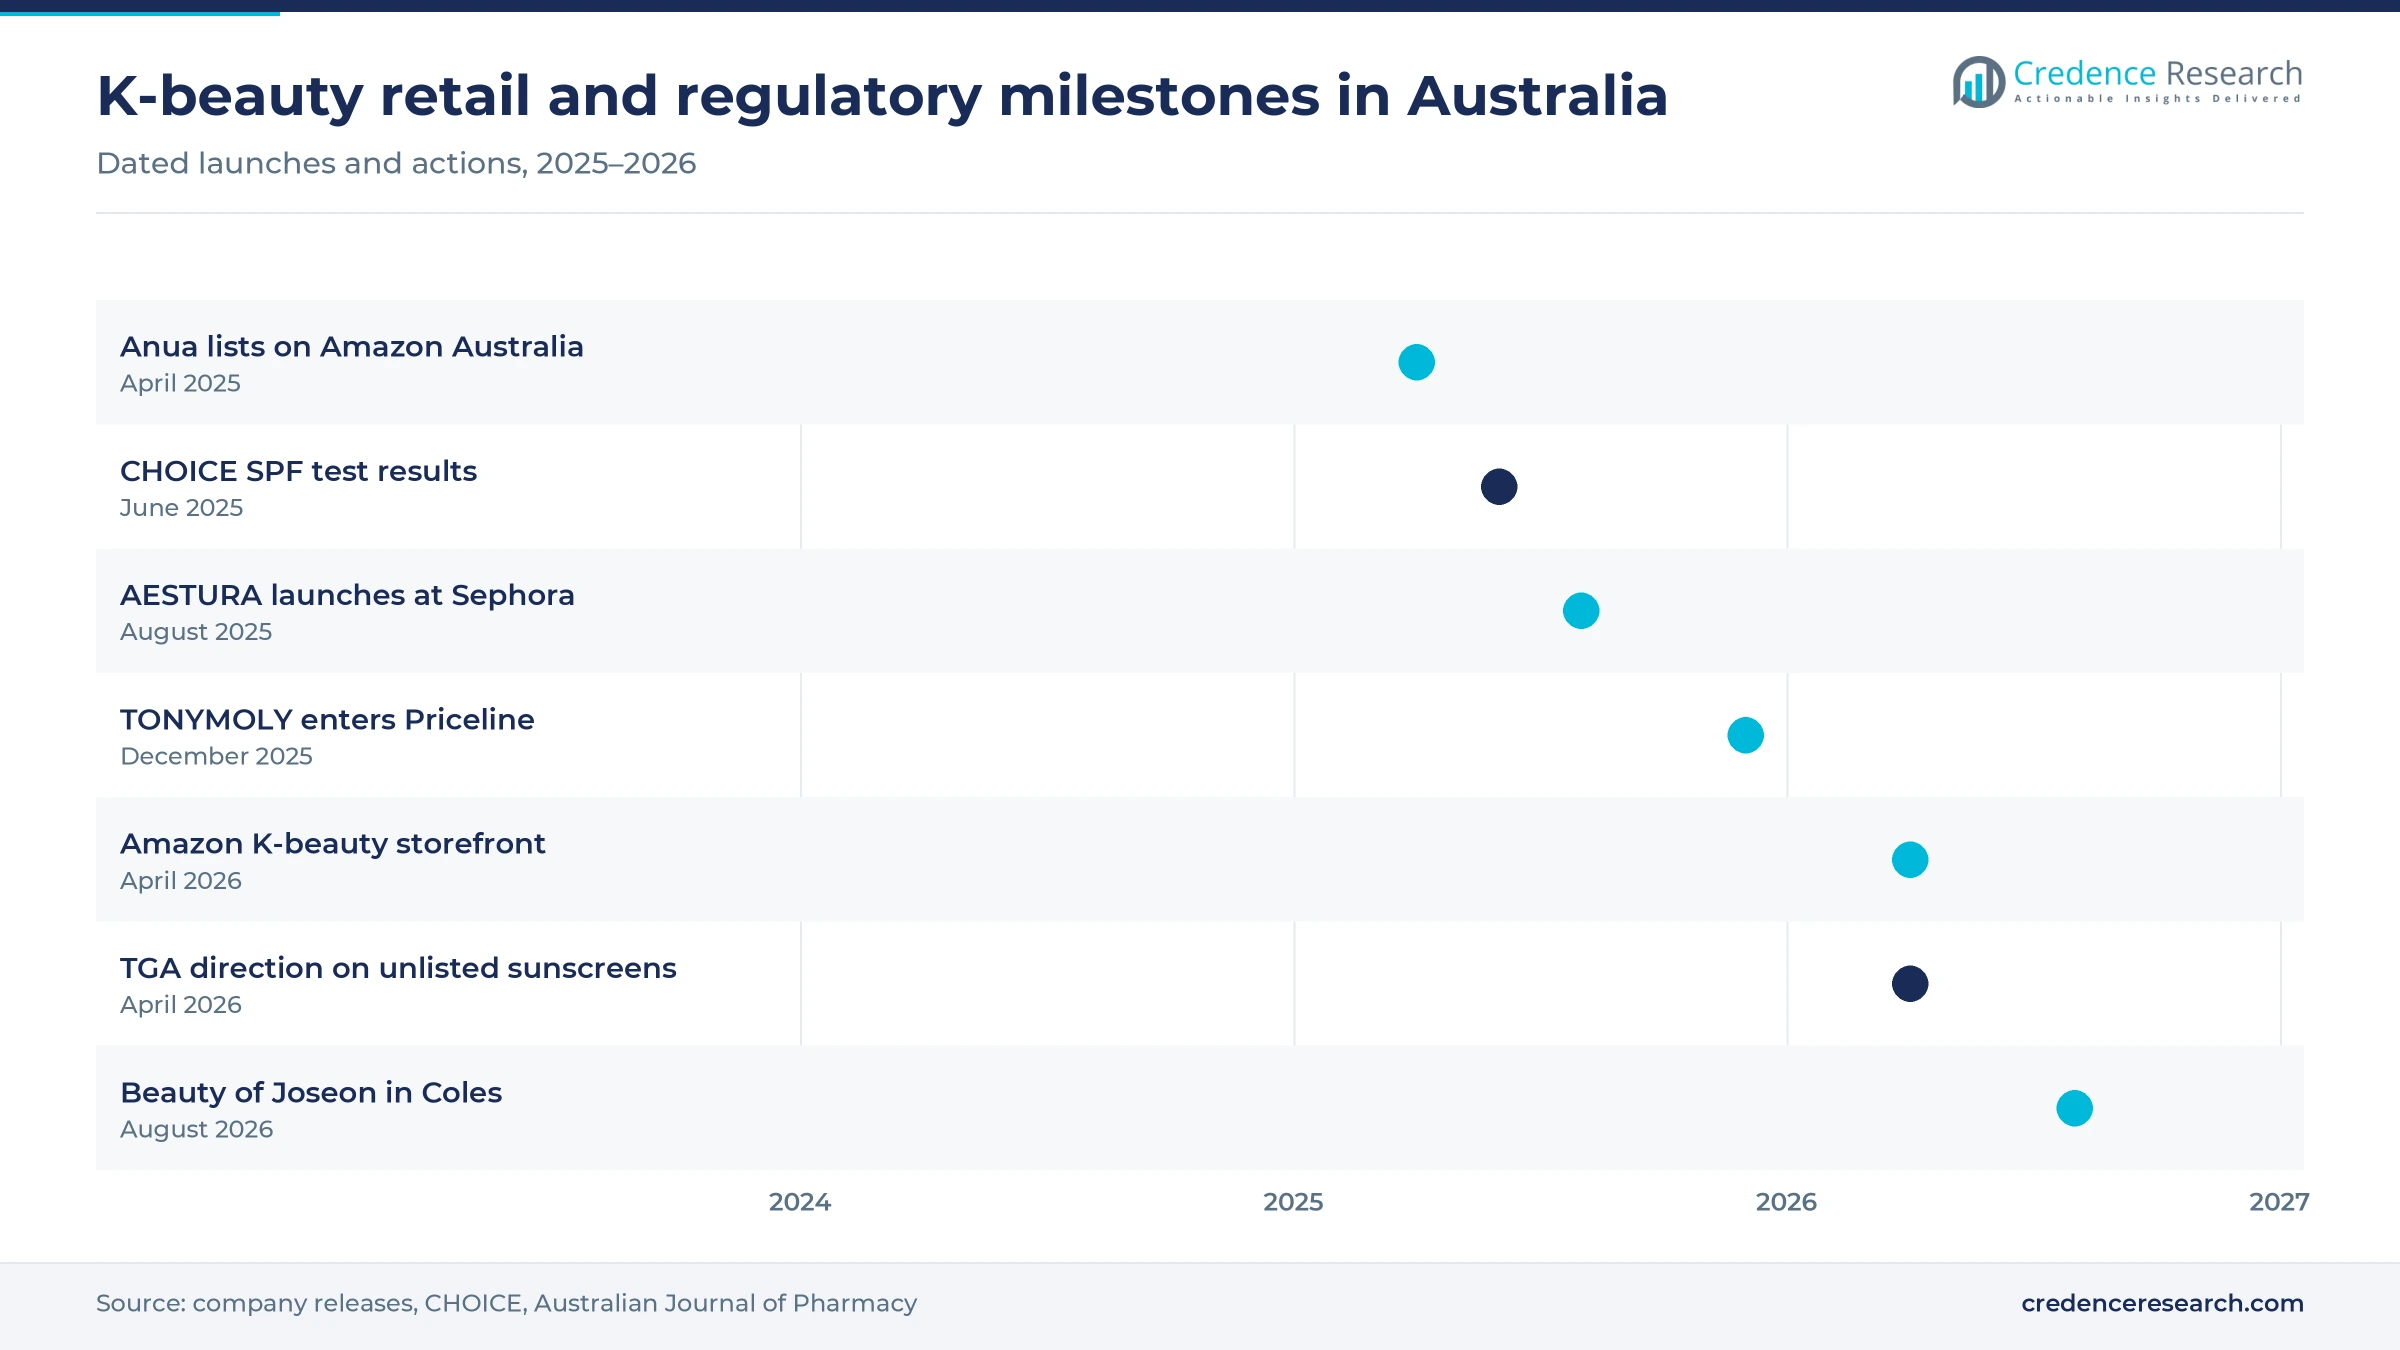
Based on type, the market is categorized into moisturizers, serums and essences, cleansers, sheet masks, sunscreens and others. Moisturizers led with 24.0% of 2025 value, because barrier-repair creams close every Korean routine and sell at higher prices than sheet face masks or toners. AESTURA reached Sephora Australia in August 2025, and Amorepacific said in March 2026 that its ATOBARRIER365 Cream had passed 10 million units in cumulative sales. Serums & Essences is the fastest-growing type at 9.1% a year, as Beauty of Joseon placed its Glow Propolis Serum in Coles supermarkets in August 2026. COSBEAUTY also listed a niacinamide and tranexamic acid dark-spot serum at AUD 69 in October 2025.
Why do female shoppers still dominate K-beauty spending?
Based on end user, the market is categorized into female, male and children and teenage buyers. Female led with 74.0% of 2025 value, because women buy both the skincare steps and the color cosmetics that Korean brands sell in Australia. COSBEAUTY reported in October 2025 that the color brands Amuse and Muzigae Mansion ranked among the bestsellers at W Cosmetics, a Korean and Japanese beauty chain. Children and Teenage is the fastest-growing group at 9.2% a year, as CHOICE reported in February 2024 that children as young as eight or nine were being marketed skincare through TikTok and YouTube influencers. That report also found a kids face cream priced at AUD 54 at Sephora.
Why does online retail lead while supermarkets grow fastest?
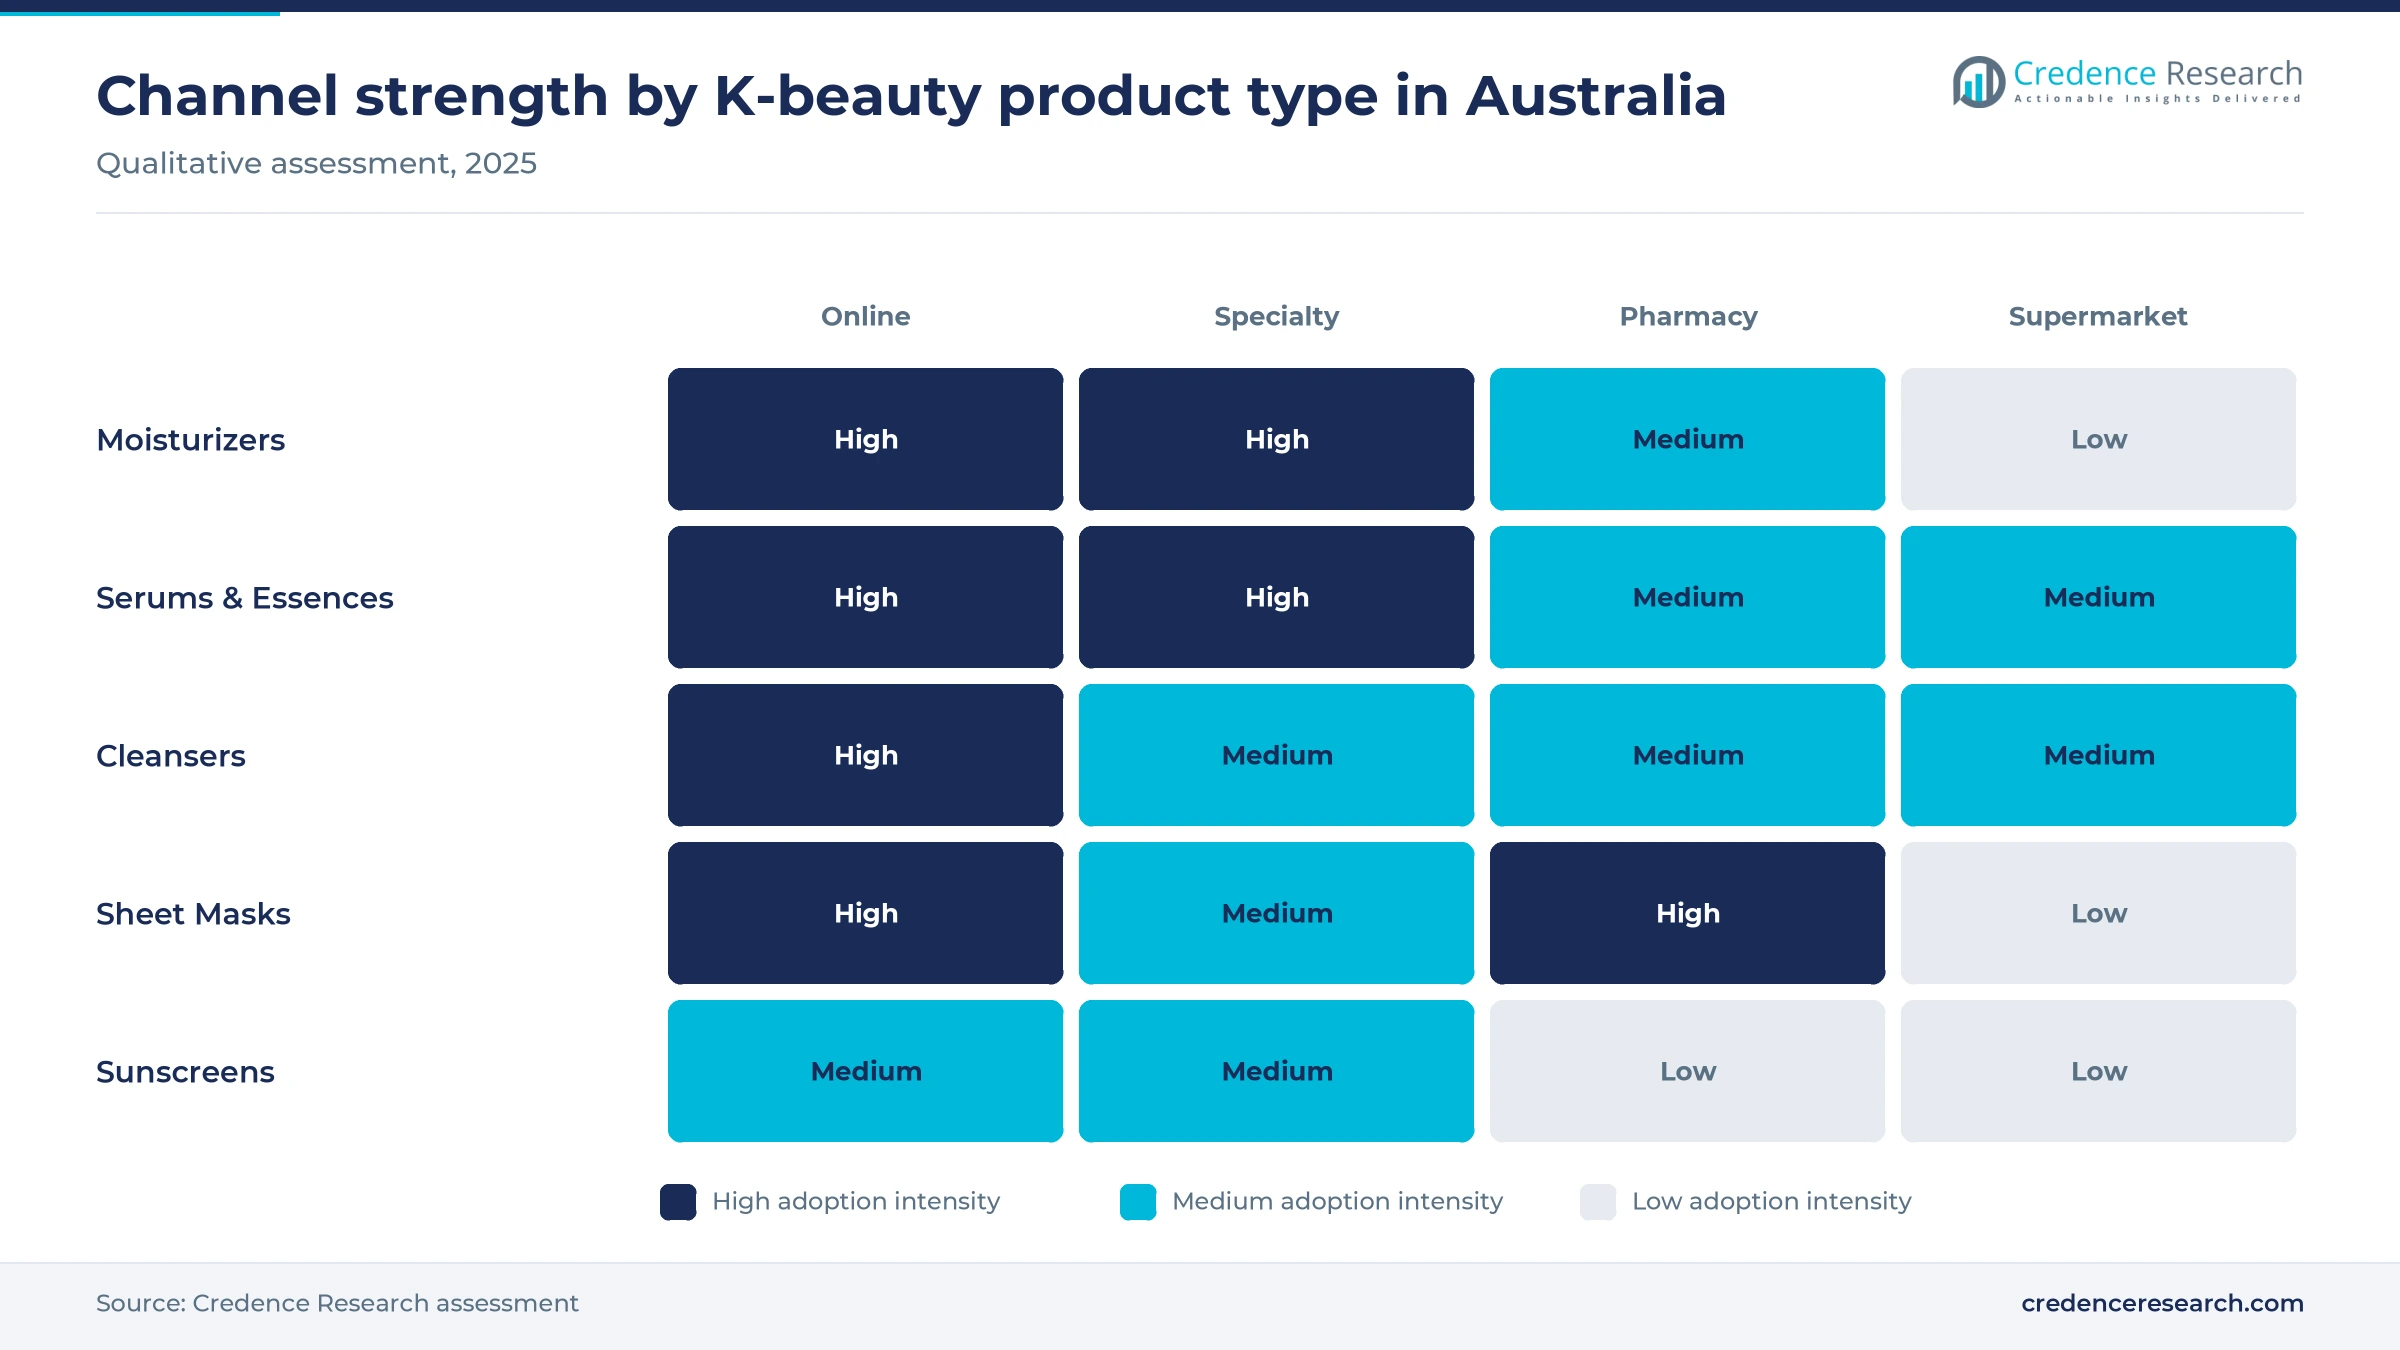
Based on distribution channel, the market is categorized into online retail, specialty and monobrand stores, pharmacies and drugstores, and supermarkets and hypermarkets. Online Retail led with 38.0% of 2025 value, because many Korean brands reached Australians through marketplaces before any store listing. Anua launched on Amazon Australia in April 2025, and Beauty Directory reported in April 2026 that Amazon Australia opened a K-beauty storefront with more than 60 brands. Supermarket/Hypermarket is the fastest-growing channel at 9.4% a year, as Beauty of Joseon entered all 800 Coles stores in August 2026. Asia Economy described it as the first Korean brand stocked by the chain.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Type | Moisturizers | 24.0% | Serums & Essences | 9.1% |
| By End User | Female | 74.0% | Children and Teenage | 9.2% |
| By Distribution Channel | Online Retail | 38.0% | Supermarket/Hypermarket | 9.4% |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Export surge, store access and diaspora lift demand
Record Korean cosmetics shipments to Australia lift supply
Rising shipments from South Korea are the clearest sign that Australian demand for Korean beauty has moved beyond niche importers. According to Korean export data compiled by REACH24H, cosmetics exports to Australia rose from USD 111.6 million in 2024 to USD 166.0 million in 2025, a 48.7% jump that lifted Australia to 14th among Korea's export markets. This growth far outpaced Korea's total cosmetics exports, which rose 12.2% to about USD 11.42 billion in 2025. Australia already imported USD 76.36 million of Korean skin care and makeup preparations in 2023, making Korea the third-largest supplier after the United States and France, according to World Bank WITS trade data. As a result, distributors now hold deeper stock and wider ranges for Australian retailers.
Beauty chains and pharmacies widen shelf space for Korean brands
Store access is widening as Australian beauty chains and pharmacies add Korean ranges that shoppers can test before they buy. Amorepacific's AESTURA launched exclusively in Sephora Australia and New Zealand stores and online on Aug. 26, 2025, according to a PR Newswire release. The same release said about 3 million ATOBARRIER365 Cream units had sold cumulatively from September 2018 to January 2024. COSBEAUTY reported in October 2025 that W Cosmetics, which opened its first store in Auburn, New South Wales, in 2014, now runs 38 stores across Australia. Beauty News Australia reported in September 2025 that Mecca had set aside K-beauty space in its Sydney flagship store, while Chemist Warehouse had added Korean masks, serums and haircare. As a result, first-time buyers can find Korean brands without ordering from overseas.
Korean diaspora and travel to Seoul build brand familiarity
A large Korean community and fast-growing travel to South Korea give Korean brands a base of informed buyers in Australia's largest cities. The 2021 Census counted 102,092 Korea-born residents nationally, and ABS QuickStats for New South Wales show that 53,046 of them lived in the state. Korea Tourism Organization data cited by Australian Community Media in November 2025 show that Australian visits to Korea in 2024 were 41% above the 2019 level. PassportCard Australia also reported a 47% rise in travel insurance sales to Korea for October 2024 to March 2025, and its chief executive said Australians were spending more on Korean goods. In turn, Sydney and Brisbane, home to the two largest Korean communities, give new brands their first test markets in Australia.
Global hero products arrive in Australia with proven demand
Korean brands enter Australia with products that have already sold at scale abroad, which lowers the risk for local retailers that list them. Amorepacific moved to raise its stake in COSRX to 93.2% on Oct. 31, 2023, and COSRX already sold its Advanced Snail line in about 140 countries, with overseas sales above 90% of its total. The Korea Times reported in October 2026 that Mediheal had sold more than 3.1 billion sheet masks by 2025 and exported to more than 40 countries. COSBEAUTY listed the Anua heartleaf pore control cleansing oil at AUD 32 in October 2025, a price close to pharmacy brands. As a result, Australian retailers can list proven sellers such as COSRX essences and Anua cleansers with less risk of slow-moving stock.
Grocery aisles and marketplaces reshape K-beauty retail
Shift of Korean skincare into supermarket aisles
Korean skincare is shifting from specialist shops into mass grocery, a change that puts it in front of shoppers who rarely visit beauty chains. Asia Economy reported on Aug. 18, 2026, that Beauty of Joseon entered all 800 Coles stores with its Glow Propolis Serum, Ginseng Cleansing Oil, Ginseng Essence Water and Green Plum Cleanser. Woolworths had earlier added Korean brands such as COSRX, Laneige and Innisfree to its online Everyday Market through Style Story in March 2022, Fashion Journal reported. Priceline Pharmacy then began selling TONYMOLY nationally in December 2025, Sitchu reported, carrying the same move into pharmacy aisles. Consequently, Supermarket/Hypermarket is the fastest-growing channel at 9.4% a year during 2026–2035.
Rise of marketplace storefronts and faster delivery
Marketplace storefronts are rising as a direct route for Korean brands that lack a local distributor. Anua, owned by The Founders, launched on Amazon in Australia and Germany in April 2025, after its U.K. and Dubai entries earlier that year, according to a PR Newswire release. Beauty Directory reported in April 2026 that Amazon Australia opened a K-beauty storefront with more than 60 brands sourced directly from Korea, with free same-day Prime delivery in Sydney and Perth and free next-day delivery in 11 other areas, including Brisbane and Melbourne. Global sellers such as YesStyle and Stylevana also ship to Australian customers, Beauty News Australia noted in September 2025. Therefore, Online Retail holds 38.0% of 2025 value, and faster delivery narrows the gap with store shopping.
Opportunity in curated K-beauty zones inside Sephora
Curated store zones offer an opening for smaller Korean brands that cannot fund a standalone Australian launch. The Korea Times reported on Jan. 21, 2026, that Olive Young had signed a partnership to act as Sephora's K-beauty curator, opening zones in the United States, Canada and four Asian markets in the second half of 2026. The same report said the zones would later extend to Sephora outlets in Australia, the Middle East and the U.K. Sephora has already shown how quickly one listing can scale, because AESTURA rolled out to about 680 Sephora stores in 17 European countries from March 2026, according to Amorepacific. As a result, specialty and monobrand stores can widen Korean ranges without each brand carrying its own import risk.
Opportunity for clinic-grade sensitive-skin lines
Sensitive-skin care is an opening for Korean brands with clinical credentials, because Australian shoppers already pay a premium for dermocosmetics sold through pharmacies and beauty chains. AESTURA says it has been the No. 1 cosmetic brand sold in Korean skin clinics for nine consecutive years, citing Korea Consumer Agency data for 2016 to 2024. Its July 2025 Australian launch release also stated that each 80 mL bottle of ATOBARRIER365 Cream holds one million ceramide capsules. The brand is distributed to every tertiary general hospital in South Korea, the same release said. Consequently, barrier-repair moisturizers and soothing serums can win pharmacist recommendations and repeat purchases in Australia.
Import rules, SPF scrutiny and discounts weigh on brands
Chemical import registration adds cost for small sellers
Every business that imports cosmetics containing industrial chemicals must register with AICIS, and the regulator enforces the rule. AICIS issued a Melbourne cosmetic distributor an AUD 16,500 infringement notice, equal to 60 penalty units, for importing chemicals without registration under section 13.1 of the Industrial Chemicals Act 2019. Small online sellers that ship Korean products in bulk face the same duty. As a result, registration and record keeping raise entry costs for new importers.
Concern over young skincare users may slow teen demand
Concern over children using adult skincare could slow the fastest-growing user group. CHOICE reported in February 2024 that a 13-year-old developed a rash and facial burns after store staff in Sydney recommended a serum. Pediatric dermatologist Dr. Li-Chuen Wong told CHOICE that active products had not been tested on tweens. In turn, parents may limit teen routines to cleansing, moisturizer and sunscreen, which cuts spending on serums and multi-step sets.
SPF scrutiny raises the bar for Korean sunscreens
Sunscreens are regulated as therapeutic goods in Australia, which makes Korean sun care harder to sell than skincare. CHOICE testing published in June 2025 found that 16 of 20 SPF 50 or 50+ sunscreens failed their labeled SPF, with one product returning SPF 4. On April 23, 2026, the TGA directed Veganic SKN to stop supplying sunscreens not entered in the Australian Register of Therapeutic Goods, the Australian Journal of Pharmacy reported. Consequently, Korean SPF lines need local testing and registration before mainstream retailers list them.
Discounting and direct imports squeeze brand margins
Price competition is squeezing margins, because shoppers can compare local shelves with overseas sellers in seconds. Priceline Pharmacy opened its TONYMOLY range in December 2025 with a 40% introductory discount, Sitchu reported. COSBEAUTY listed a Torriden hyaluronic acid mask at AUD 4 a piece in October 2025, while YesStyle and Stylevana ship directly to Australian buyers. Consequently, distributors that pay for local stock and registration must defend prices against parallel sellers.
Sydney leads Korean beauty spend as Perth grows fastest
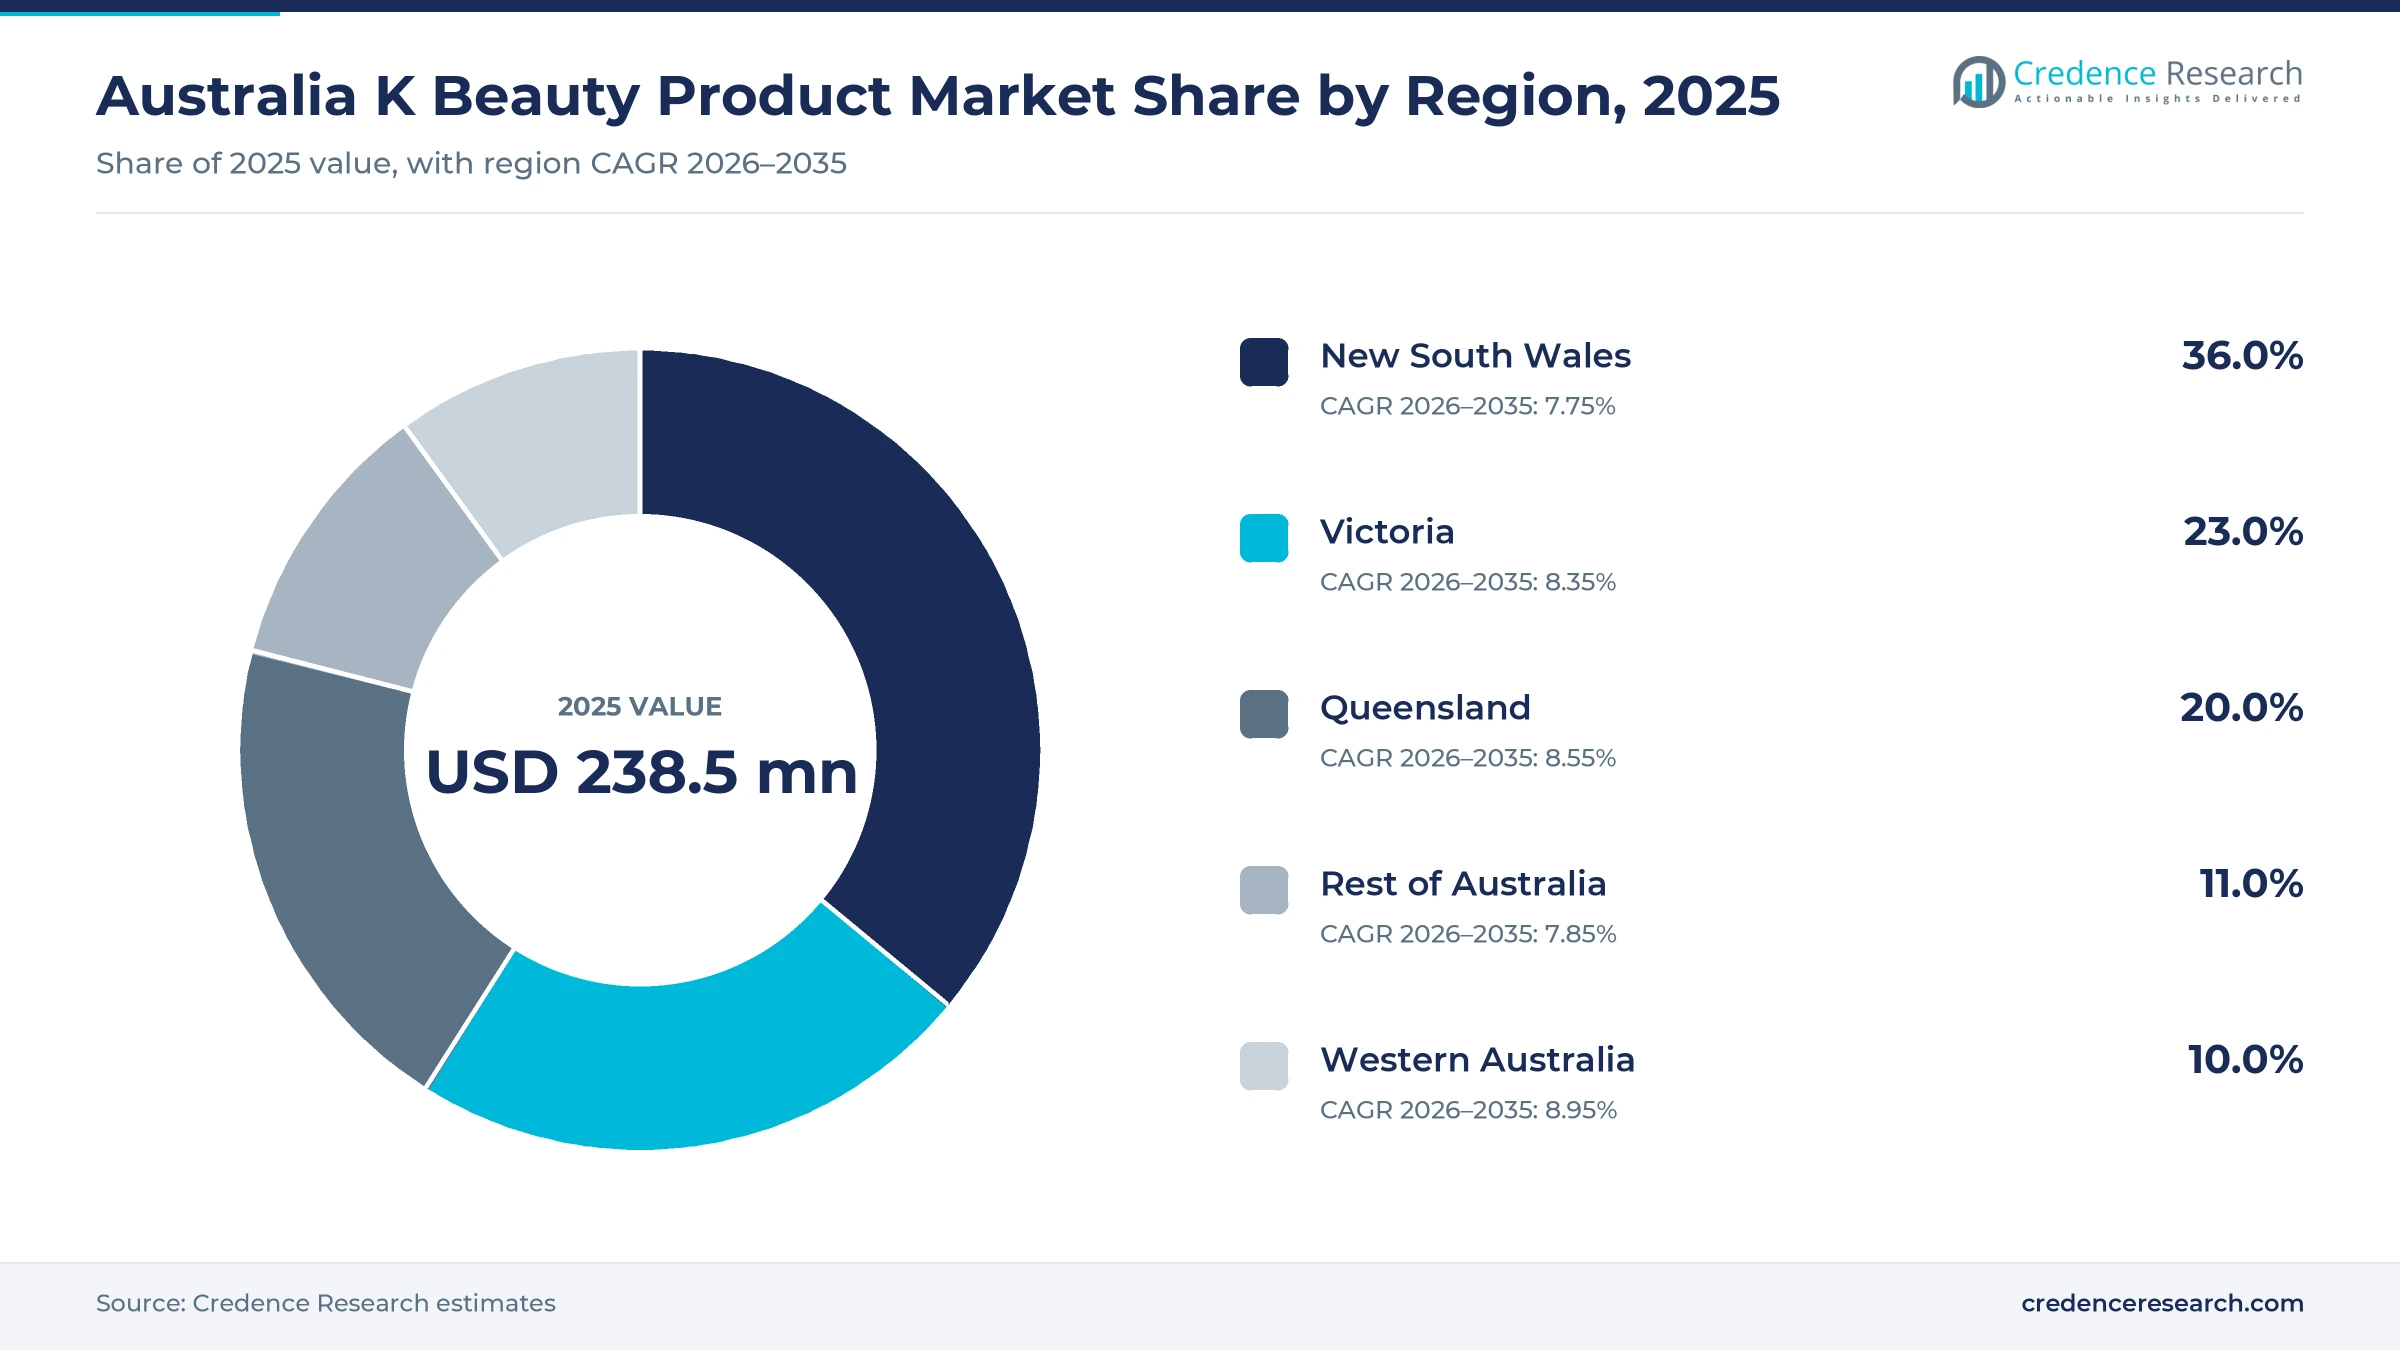
Regional shares are Credence Research estimates built from ABS state population at June 2025 and 2021 Census counts of Korea-born residents by state. Queensland, with 20.0% of 2025 value, ranks third among the five regions in the Credence Research regional model.
| Region | Value, 2025 (USD million) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| New South Wales | 85.9 | 36.0% | 7.8% |
| Victoria | 54.9 | 23.0% | 8.3% |
| Queensland | 47.7 | 20.0% | 8.6% |
| Rest of Australia | 26.2 | 11.0% | 7.8% |
| Western Australia | 23.9 | 10.0% | 8.9% |
New South Wales leads on its Korean community and Sydney retail
New South Wales held 36.0% of 2025 value and grows at 7.8% a year, the largest regional base in the country. More than half of Australia's Korea-born residents lived in the state at the 2021 Census, and its population reached 8,593,900 at June 30, 2025, according to the ABS. Sydney also hosts the Mecca flagship with dedicated K-beauty space, while W Cosmetics began in Auburn. As a result, new Korean brands usually test Australian demand in Sydney first.
Victoria gains from Melbourne malls and fast delivery
Victoria held a 23.0% share of 2025 value and grows at 8.3% a year, supported by a population of 7,074,500 that rose 1.8% in the year to June 2025. The state counted 15,429 Korea-born residents in the 2021 Census, fewer than Queensland despite its larger population. However, Amazon Australia offers free next-day Prime delivery in Melbourne for its K-beauty storefront, which widens choice for Melbourne shoppers beyond mall stores.
Queensland builds on the second-largest Korean community
Queensland held a 20.0% share of 2025 value and grows at 8.6% a year, ahead of the national pace. The state counted 19,658 Korea-born residents in the 2021 Census, the second-largest Korean community after New South Wales. Its population reached 5,669,800 at June 30, 2025, after 1.8% growth over the year. Because Brisbane also receives next-day Prime delivery from Amazon Australia, Queensland buyers gain access to a broad Korean range online.
Western Australia grows fastest on population gains
Western Australia held a 10.0% share of 2025 value and is the fastest-growing region at 8.9% a year. Its population rose 2.2% to 3,043,700 in the year to June 2025, the fastest rate of any state, according to the ABS. The state counted 6,429 Korea-born residents at the 2021 Census, according to the ABS. Amazon Australia's same-day Prime delivery in Perth also brings Korean brands within a day of order for Perth buyers.
Rest of Australia depends on national supermarket reach
Rest of Australia, covering South Australia, Tasmania, the ACT and the Northern Territory, had a 2025 value share of 11.0% and grows at 7.8% a year. South Australia had 1,902,300 residents at June 30, 2025, and counted 3,837 Korea-born residents in 2021. Because specialty stores are fewer outside the large capitals, the Coles rollout of Beauty of Joseon puts a Korean range in every Coles store these shoppers visit.
Coles, Sephora and Amazon launches since 2025
| Development | Status and market relevance |
|---|---|
| In April 2025, The Founders launched Anua on Amazon in Australia, with its heartleaf cleansing oil and toner as lead products. | Online channel entry |
| In August 2025, Amorepacific launched AESTURA exclusively in Sephora Australia and New Zealand stores and online. | Specialty channel entry |
| In December 2025, Priceline Pharmacy began selling TONYMOLY nationally with an introductory discount. | Pharmacy channel entry |
| In April 2026, Amazon Australia opened a dedicated K-beauty storefront with brands sourced directly from Korea. | Marketplace expansion |
| In August 2026, Goodai Global placed Beauty of Joseon serums and cleansers in Coles supermarkets nationwide. | Supermarket channel entry |
Barrier creams, serums and PA-rated sunscreens set the pace
- Ceramide capsule creams such as ATOBARRIER365 release barrier lipids slowly over the day, which suits dry indoor air, heated offices and sensitive skin.
- Snail mucin essences from the COSRX Advanced Snail line give hydration in light layers that suit humid Queensland and Sydney summers, where heavy creams feel greasy.
- Heartleaf and propolis serums from Anua and Beauty of Joseon target redness and dullness at lower prices than many Western serums, which helps them sell in pharmacies and supermarkets.
- PA-rated sunscreens show UVA protection with plus signs next to SPF, but Australian sale still needs ARTG entry and SPF testing to Australian standards before any retailer can list them.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Amorepacific brands and indie labels compete for shelves
Competition in Australia is split between Korean groups with several brands and fast-growing independent labels that win through hero products. Amorepacific leads the group tier with AESTURA at Sephora, Laneige and Innisfree, and it controls COSRX after raising its stake in 2023. Independent labels such as Beauty of Joseon, Anua, Torriden and TONYMOLY compete for listings at Coles, Amazon Australia, Priceline Pharmacy and specialty chains. W Cosmetics acts as the main specialist retailer, with 38 stores that carry Korean and Japanese ranges, including APR's Medicube line. Brands compete on clinical claims, ingredient stories such as heartleaf, propolis and snail mucin, and entry prices for skin care basics. In turn, retailers favor brands that arrive with global sales proof, local stock and compliant labels, which raises the bar for small importers. Amorepacific's AESTURA reached about 680 Sephora stores in 17 European countries in 2026, showing the scale Korean groups can bring to the Australian market.
Who sells Korean beauty brands in Australia today?
| Company | Type | Role in the market |
|---|---|---|
| Amorepacific Corporation | Brand owner | AESTURA at Sephora Australia since August 2025, plus Laneige, Innisfree and COSRX |
| Goodai Global (Beauty of Joseon) | Brand owner | First Korean brand ranged in all Coles stores, August 2026 |
| The Founders Inc. (Anua) | Brand owner | Heartleaf cleansing oil and serums sold on Amazon Australia since April 2025 |
| APR Corporation (Medicube) | Brand owner | Medicube skin care sold through Sydney beauty stores such as W Cosmetics |
| TONYMOLY Co. Ltd. | Brand owner | National Priceline Pharmacy launch in December 2025 |
| Torriden | Brand owner | Hyaluronic acid masks and serums sold through specialty retailers |
Why mass retail entry favors proven Korean hero products
Credence Research's view is that Korean beauty in Australia has passed the niche stage, and the next gains will go to brands that can supply mass retail at scale. The Coles rollout and the Amazon storefront show that buyers now look for Korean hero products in weekly shopping, not only in specialty stores. Serums and essences, the fastest-growing type at 9.1% a year, show where that demand is heading in the market. Brands with global sales proof, local stock and registered sunscreens are best placed, while small importers face rising compliance and price pressure. Retailers that curate ranges, as Olive Young plans for Sephora, should capture the fastest growth.
Korean export data and ABS statistics anchor the model
The report uses 2025 as the base year and forecasts values for 2026 to 2035. Market values come from the Credence Research model, which starts from Korean cosmetics export data for Australia and World Bank WITS import records, then removes contract-made goods and applies distribution and retail margins. Segment and regional splits are Credence Research estimates based on ABS population and Census data, retailer listings and company releases. Regulatory notices from the TGA and AICIS and published consumer testing were also reviewed. No interviews or surveys were used to build these estimates.
Supermarket reach and curated zones carry growth to 2035
The Australia K beauty product market is set to grow from USD 258.0 million in 2026 to USD 524.0 million by 2035 as Korean brands move deeper into supermarkets, pharmacies and curated beauty zones. Serums and essences should keep gaining share as hero products reach grocery shelves, while Western Australia, the fastest-growing region, Queensland and Victoria all grow faster than New South Wales. Sunscreen stays open only to brands that complete ARTG entry and Australian SPF testing, after CHOICE found in June 2025 that 16 of 20 tested SPF 50 or 50+ products missed their label claims. Price pressure from direct importers will continue, so local distributors will compete on authenticity, stock and service.
Frequently Asked Questions
How big is the Australia K beauty product market?
How popular is K-beauty in Australia?
Which K-beauty product type leads in Australia?
Where do Australians buy Korean skincare?
Which state buys the most K-beauty products in Australia?
Where does Australia import skin care and makeup from?
What are the main K-beauty trends in Australia?
What rules apply to importing Korean cosmetics and sunscreens into Australia?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Moisturizers
- 1.2.2 Serums & Essences
- 1.2.3 Cleansers
- 1.2.4 Sheet Masks
- 1.2.5 Sunscreens
- 1.2.6 Others
- 1.3 By End User
- 1.3.1 Female
- 1.3.2 Male
- 1.3.3 Children and Teenage
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 238.5 million → 2035: USD 524.0 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Australia K Beauty Product Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Australia K Beauty Product Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Australia K Beauty Product Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Australia K Beauty Product Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Australia K Beauty Product Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Australia K Beauty Product Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Australia K Beauty Product Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Australia K Beauty Product Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 238.5 million → 2035: USD 524.0 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Australia K Beauty Product Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Moisturizers
- 12.3.7.2 Serums & Essences
- 12.3.7.3 Cleansers
- 12.3.7.4 Sheet Masks
- 12.3.7.5 Sunscreens
- 12.3.7.6 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Female
- 12.4.7.2 Male
- 12.4.7.3 Children and Teenage
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Australia K Beauty Product End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Australia K Beauty Product Geographic Market Outlook, 2025-2035
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2025-2035
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Australia K Beauty Product Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Australia K Beauty Product Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Amorepacific Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Goodai Global (Beauty of Joseon)
- 18.4 The Founders Inc. (Anua)
- 18.5 APR Corporation (Medicube)
- 18.6 TONYMOLY Co. Ltd.
- 18.7 Torriden
- 18.8 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

