
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Automotive Carbon Fiber Composites Market Size 2024 | USD 9850 million |
| Automotive Carbon Fiber Composites Market, CAGR | 3.8% |
| Automotive Carbon Fiber Composites Market Size 2032 | USD 13274 million |
Market Overview:
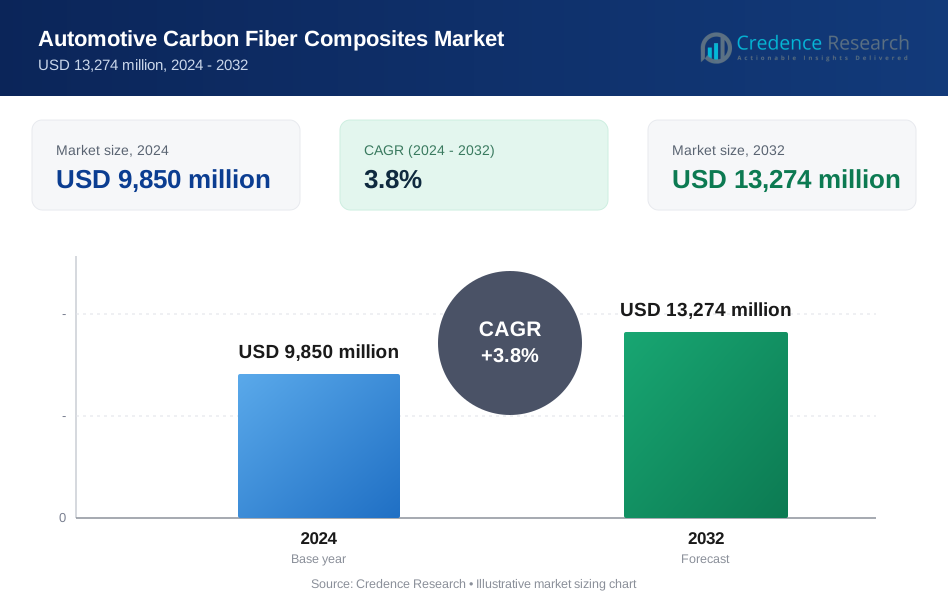
The Automotive Carbon Fiber Composites Market is projected to grow from USD 9850 million in 2024 to an estimated USD 13274 million by 2032, with a compound annual growth rate (CAGR) of 3.8% from 2024 to 2032.
The primary drivers fueling the expansion of the automotive carbon fiber composites market include growing environmental concerns and stringent regulatory mandates focused on reducing carbon emissions. As global fuel economy standards become more rigorous, automakers are under pressure to incorporate lightweight materials that can enhance energy efficiency. Carbon fiber composites are increasingly adopted as a solution for this requirement, replacing traditional metals such as steel and aluminum in structural and non-structural vehicle components. The rapid acceleration of electric vehicle (EV) production further amplifies this trend. Lightweighting is critical in EVs, where reducing mass can extend battery range and improve overall energy efficiency. Additionally, technological advancements in manufacturing processes such as resin transfer molding (RTM), automated fiber placement (AFP), and compression molding have significantly lowered production costs and cycle times, making carbon fiber composites more economically viable for mass production.
Regionally, Asia-Pacific dominates the automotive carbon fiber composites market, with countries such as China, Japan, and South Korea leading in both vehicle production and material adoption. The region benefits from a robust automotive manufacturing base, strong government initiatives promoting electric vehicles, and an increasing focus on environmentally sustainable transportation solutions. China, in particular, is emerging as a key market, given its large-scale investments in EV infrastructure and its growing emphasis on lightweight vehicle design to meet emission norms. Meanwhile, Europe is expected to register the fastest growth during the forecast period, supported by stringent CO₂ emission standards set by the European Union and the region’s early adoption of high-performance composites in automotive design. Countries such as Germany, the UK, and France are leveraging carbon fiber in both conventional and electric vehicles to meet aggressive climate targets. In North America, the United States holds a significant share, driven by the demand for high-end performance vehicles and luxury cars that incorporate advanced composite materials.
Market Insights:
- The Automotive Carbon Fiber Composites Market is projected to grow from USD 9,850 million in 2024 to USD 13,274 million by 2032, at a CAGR of 3.8%.
- Stringent emission regulations and the push for fuel efficiency are prompting automakers to replace traditional metals with carbon fiber composites across vehicle structures.
- The accelerating shift to electric vehicles is increasing demand for lightweight components, especially in battery enclosures, underbodies, and aerodynamic parts.
- Manufacturing innovations such as RTM, AFP, and compression molding are lowering production costs and making carbon fiber more viable for high-volume automotive applications.
- Growing consumer demand for high-performance and luxury vehicles is supporting the use of carbon fiber for both functional and aesthetic advantages.
- High production costs and limited recycling infrastructure remain key barriers, restricting widespread adoption in lower-cost vehicle segments.
- Asia-Pacific leads the market with over 40% share, driven by China, Japan, and South Korea, while Europe is expected to grow fastest due to stringent CO₂ standards and strong EV policies.
Market Drivers:
Stringent Emission Regulations Driving Lightweight Material Adoption
Governments across the globe have implemented strict emission regulations aimed at reducing greenhouse gas emissions from automobiles. These policies are pushing automakers to adopt lightweight materials that can improve fuel economy and reduce the overall carbon footprint. The Automotive Carbon Fiber Composites Market benefits from this trend due to the material’s superior strength-to-weight ratio. Carbon fiber composites reduce vehicle mass without compromising structural integrity or safety. It helps automakers meet fuel efficiency standards and extend the range of electric vehicles. Regulatory mandates from the European Union, the U.S. Environmental Protection Agency, and similar bodies in Asia-Pacific are accelerating this shift. Automakers are prioritizing carbon fiber over traditional metals in response to growing legislative pressures.
- For instance, the European Union has established ambitious environmental targets, including a ban on new combustion engine vehicles by 2035, which is driving the adoption of carbon fiber-reinforced composites (CFRPs) capable of reducing vehicle weight.
Rising Electric Vehicle Production Increasing Demand for Lightweight Components
The global transition toward electric mobility continues to influence material choices in vehicle manufacturing. Electric vehicles require lightweight construction to offset battery weight and maximize energy efficiency. The Automotive Carbon Fiber Composites Market is expanding as EV manufacturers integrate carbon fiber into battery enclosures, frames, and aerodynamic components. It contributes to better acceleration, longer driving range, and improved overall performance. Manufacturers are leveraging carbon fiber to overcome design challenges unique to electric platforms. Companies such as Tesla and BMW are already incorporating advanced composites in next-generation electric models. This shift is creating new revenue streams for carbon fiber suppliers worldwide.
- Tesla’s Model S, for example, uses carbon fiber components to reduce weight, resulting in enhanced driving range and superior acceleration.
Technological Advancements in Manufacturing Processes Enhancing Market Accessibility
Developments in processing technologies are reducing the cost and complexity of manufacturing carbon fiber composites. Automated processes such as resin transfer molding (RTM), compression molding, and 3D printing have increased production efficiency. These technologies allow faster cycle times and consistent product quality at scale. The Automotive Carbon Fiber Composites Market is experiencing wider adoption due to the improved affordability of components. It enables mass-market vehicle manufacturers to integrate composites into mainstream models, not just luxury or performance segments. Investments in R&D by automotive OEMs and material suppliers are further refining fabrication techniques. This is expanding the scope of applications across different vehicle classes.
Growing Consumer Preference for High-Performance and Luxury Vehicles
Consumer demand for high-performance and premium vehicles has surged in recent years. These vehicles often require advanced materials that offer both functionality and aesthetics. The Automotive Carbon Fiber Composites Market supports this demand by offering sleek designs, reduced weight, and enhanced driving dynamics. It provides an upscale look that appeals to design-conscious buyers while contributing to superior handling and speed. Brands in the sports and luxury segment frequently use carbon fiber in hoods, spoilers, and body panels. Manufacturers continue to promote the material as a hallmark of quality and innovation. This consumer-driven trend is reinforcing the market's long-term growth.
Market Trends:
Integration of Carbon Fiber Composites into Structural Vehicle Components
Automakers are shifting from using carbon fiber composites solely in aesthetic or non-load-bearing parts to integrating them into core structural components. This includes applications in chassis elements, roof panels, side beams, and crumple zones. The Automotive Carbon Fiber Composites Market is evolving to support structural integration by offering higher modulus grades and improved bonding techniques. It enables significant weight savings without compromising crash safety or stiffness. Major manufacturers are designing vehicle platforms with carbon fiber as a foundational material rather than a supplementary feature. This trend reflects growing confidence in composite reliability and manufacturability. Automakers are aligning their design philosophies with long-term sustainability and regulatory compliance goals.
- For instance, BMW uses carbon fiber extensively in the passenger cell of the BMW i3, where the entire car body is made from carbon fiber, and in the roofs of BMW M models to achieve significant weight reduction while maintaining crash safety and stiffness.
Growth in Hybrid Material Systems Combining Composites with Metals
The industry is witnessing a growing adoption of hybrid material systems that combine carbon fiber composites with aluminum or high-strength steel. These hybrid structures provide an optimal balance of weight, cost, and performance. The Automotive Carbon Fiber Composites Market is benefiting from collaborative research focused on bonding techniques and material interfaces. It allows manufacturers to tailor structural elements to specific performance needs while controlling costs. Hybrid approaches are particularly common in electric and high-performance vehicles, where packaging efficiency and structural rigidity are critical. Automakers are using simulation tools to fine-tune composite-metal integration at the design stage. This trend supports broader adoption of composites across diverse vehicle categories.
Expansion of Recyclable and Sustainable Carbon Fiber Solutions
Sustainability goals are driving innovation in recyclable and bio-based carbon fiber composites. Companies are developing thermoplastic matrices that allow easy recycling without degrading performance. The Automotive Carbon Fiber Composites Market is aligning with circular economy principles by promoting closed-loop production systems. It enhances material efficiency and reduces lifecycle emissions associated with automotive manufacturing. Emerging technologies now support reuse of composite scrap and recovery of carbon fibers through pyrolysis or solvolysis. OEMs are partnering with material suppliers to embed sustainability into the supply chain. This trend reflects growing environmental accountability across the automotive sector.
- Mitsubishi Chemical Group, for example, has introduced the BiOpreg #400 series, a carbon fiber prepreg material made from plant-derived resin, targeting automotive applications for both interiors and exteriors.
Rising Adoption of Carbon Fiber in Mid-Segment and Mass-Market Vehicles
What was once a premium material reserved for supercars is now finding applications in mid-segment vehicles. Automakers are introducing carbon fiber-reinforced parts in compact SUVs, sedans, and even hatchbacks. The Automotive Carbon Fiber Composites Market is expanding as cost reductions and manufacturing advances make composites viable beyond luxury segments. It allows broader customer segments to access improved fuel efficiency and dynamic performance. Automakers are marketing carbon fiber as both a functional and aesthetic enhancement in mainstream vehicles. This democratization of composite technology is reshaping its role in automotive design strategies.
Market Challenges Analysis:
High Production Costs and Limited Economies of Scale Restrict Widespread Adoption
The high cost of raw carbon fibers and complex manufacturing processes continue to limit the adoption of composites in mainstream vehicle segments. While premium and performance vehicles can absorb these costs, mass-market manufacturers often find carbon fiber economically unviable for large-scale use. The Automotive Carbon Fiber Composites Market faces pressure to reduce production expenses without compromising material quality. It depends heavily on automation and high-throughput methods to improve cost-efficiency, but current solutions remain expensive compared to traditional metals. Manufacturers also face challenges in achieving consistent fiber alignment and defect-free laminates during mass production. These issues affect material strength and increase the rate of waste, which further elevates production costs. The lack of large-scale supply chains for advanced composites constrains economies of scale and slows market expansion.
- For instance, according to Toray Industries, the average cost of carbon fiber is approximately $10–$12 per pound, compared to less than $1 per pound for steel.
Repair Complexity and Lack of Standardized Recycling Processes Pose Operational Risks
Vehicles built with carbon fiber composites require specialized repair procedures, making post-accident service more expensive and less accessible. Traditional body shops lack the tools and expertise to restore damaged composite parts, leading to longer downtimes and higher replacement costs. The Automotive Carbon Fiber Composites Market must address these service limitations to gain traction in non-luxury segments. It also faces concerns over recyclability, with limited infrastructure and standard practices for composite recovery. Thermoset-based composites, in particular, are difficult to recycle due to their cross-linked structure. OEMs and suppliers must invest in developing recyclable thermoplastics and scalable recovery methods. Without solutions to these end-of-life challenges, long-term adoption in sustainability-focused regions may face regulatory resistance.
Market Opportunities:
Advances in thermoplastic resin technology are creating new avenues for cost-effective and recyclable carbon fiber composites. These materials offer shorter production cycles, easier processing, and improved compatibility with mass-production techniques. The Automotive Carbon Fiber Composites Market stands to benefit from this shift, enabling OEMs to integrate composites into compact and mid-range vehicles. It supports scalable manufacturing while aligning with sustainability goals. Thermoplastic solutions also simplify repair and recycling, making them more attractive for long-term use. Suppliers that can deliver high-performance thermoplastics at competitive prices will gain a strategic edge in this evolving market.
The global push toward electric mobility presents a major opportunity for carbon fiber integration in next-generation vehicle platforms. OEMs are seeking lightweight materials to extend EV range and improve energy efficiency. The Automotive Carbon Fiber Composites Market is well-positioned to address this demand by offering strength, thermal resistance, and design flexibility. It allows battery enclosures, crash structures, and underbody panels to meet performance targets without added weight. As EV production scales globally, composite suppliers can expand their presence across core structural and functional applications. Strategic partnerships with EV manufacturers will accelerate this momentum and open new growth channels.
Market Segmentation Analysis:
The Automotive Carbon Fiber Composites Market is segmented by component, application, vehicle type, and region, each playing a distinct role in shaping market demand.
By component, structural components hold the largest share due to their critical role in reducing vehicle weight and enhancing performance. Exterior components such as hoods and bumpers follow closely, driven by consumer demand for aesthetics and aerodynamics. Interior components are gaining traction, particularly in luxury and EV models prioritizing comfort and lightweighting.
By application, the body and exterior segment dominates due to high usage of carbon fiber in panels, spoilers, and roof structures. The powertrain and chassis segment is expanding, with carbon fiber used in engine covers, drive shafts, and suspension elements to boost efficiency. Interior and electronics applications are growing, supported by trends in premium vehicle design and weight-sensitive electric systems.
By vehicle type, sports and racing cars lead adoption due to performance needs, while electric vehicles and hybrids represent the fastest-growing segment. The market is also expanding in passenger cars as manufacturers integrate composites to meet emissions standards. Commercial vehicles show steady interest in structural applications for fuel-saving benefits.
Segmentation:
By Component:
- Exterior Components
- Interior Components
- Structural Components
By Application:
- Body and Exterior
- Interior
- Powertrain and Chassis
- Electrical and Electronics
By Vehicle Type:
- Passenger Cars
- Commercial Vehicles
- Sports and Racing Cars
- Electric Vehicles (EVs) and Hybrid Vehicles
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
Asia-Pacific holds the largest share of the Automotive Carbon Fiber Composites Market, accounting for nearly 41% of global revenue in 2025. China, Japan, and South Korea dominate the region’s automotive production and are rapidly integrating carbon fiber into vehicle platforms to meet evolving emission standards. Government incentives for electric vehicles, combined with strong domestic manufacturing capabilities, support the widespread use of lightweight materials. It enables OEMs to respond quickly to both domestic and export demands for fuel-efficient and high-performance vehicles. Investment in research and localized carbon fiber production further strengthens the region’s leadership position. The expanding EV segment in China and Japan continues to drive demand for advanced composites in structural and battery-related components.
Europe represents the second-largest regional market, holding around 30% share in 2025, supported by stringent carbon emission regulations and a strong luxury and performance vehicle segment. Germany, the UK, France, and Italy lead in composite adoption, with OEMs such as BMW and Audi integrating carbon fiber into high-end models and electric vehicle platforms. The Automotive Carbon Fiber Composites Market in Europe benefits from robust R&D ecosystems and close collaboration between automotive manufacturers and material suppliers. It supports early-stage development of recyclable and bio-based composites aligned with EU sustainability goals. Public policies favoring lightweight vehicle design continue to accelerate the shift from traditional materials to carbon-based alternatives. European manufacturers also prioritize material circularity, which drives innovation in recyclable thermoplastics.
North America accounts for approximately 22% of the market share, led by the United States, where consumer preference for high-performance and premium vehicles supports composite use. Automakers in the region integrate carbon fiber into sports cars, pickup trucks, and electric vehicles to enhance performance and meet fuel efficiency regulations. The Automotive Carbon Fiber Composites Market in North America benefits from the presence of leading composite suppliers and investments in automation technologies for composite fabrication. It also gains momentum from defense and aerospace crossover technologies that support automotive-grade composite innovation. Industry collaboration through advanced material research centers accelerates deployment in high-volume vehicle production. The U.S. market remains a hub for high-strength carbon composite development, targeting both weight reduction and safety enhancement.
Key Player Analysis:
- SGL Carbon SE
- Toray Industries, Inc.
- ACP Composites, Inc.
- Clearwater Composites, LLC
- Owens Corning
- HITCO Carbon Composites Inc.
- Mitsubishi Rayon Carbon Fiber and Composites, Inc.
- Rock West Composites
Competitive Analysis:
The Automotive Carbon Fiber Composites Market features a competitive landscape marked by technological innovation and strategic collaborations. Key players include Toray Industries, SGL Carbon, Hexcel Corporation, Mitsubishi Chemical Group, and Teijin Limited. These companies focus on product development, cost reduction, and scaling manufacturing capabilities to meet growing automotive demand. It encourages partnerships with OEMs to co-develop application-specific composite solutions, particularly for electric vehicles and structural parts. Mergers, acquisitions, and regional expansions strengthen supply chain integration and global presence. Smaller niche players also contribute by offering specialized resins, thermoplastics, and customized carbon fiber solutions. Competitive differentiation hinges on process efficiency, mechanical performance, and recyclability. The market rewards innovation in automated production techniques and hybrid material systems that balance strength, weight, and cost.
Recent Developments:
- In March 2025, McLaren introduced a groundbreaking carbon fiber manufacturing technique known as Automated Rapid Tape (ART) carbon. This innovation, adapted from aerospace manufacturing, automates the application of dry composite tape for precise fiber placement, significantly enhancing the strength-to-weight ratio of automotive components.
- In April 2024, Toray Industries entered into a strategic partnership with Hyundai Motor Group to advance material innovation for next-generation mobility. This collaboration focuses on joint research and development of advanced carbon fiber composites to support electrification and sustainability in the automotive industry. The partnership is positioned to accelerate the adoption of lightweight, high-strength materials in vehicles, enhancing both performance and environmental outcomes.
- In February 2023, SGL Carbon SE announced the sale of its Composite Solutions Business Unit in Gardena, California (formerly HITCO Carbon Composites) to Tex Tech Industries, a move aimed at strategic alignment and focusing on core business areas. The Gardena site is a key supplier of high-temperature composite materials for automotive and aerospace applications. This transaction included all plant assets and customer contracts, ensuring continuity for clients in the automotive sector.
Market Concentration & Characteristics:
The Automotive Carbon Fiber Composites Market remains moderately concentrated, with a few global players controlling a significant share of the value chain, from raw fiber production to composite part manufacturing. It exhibits high entry barriers due to the capital-intensive nature of carbon fiber processing, technical complexity, and the need for strong OEM relationships. The market is characterized by long-term supply contracts, tight integration with vehicle design processes, and a strong focus on quality assurance. Innovation cycles are driven by collaboration between material suppliers and automakers, particularly in electric and high-performance vehicles. It also reflects growing interest in sustainable alternatives, such as recyclable thermoplastics and bio-based matrices. While major players dominate global supply, regional manufacturers contribute by addressing localized demand and customization needs.
Report Coverage:
The research report offers an in-depth analysis based on component, application and vehicle type, It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand will rise as automakers prioritize lightweight materials to meet stricter global emission regulations.
- Electric vehicle production will accelerate carbon fiber integration in structural and battery components.
- Advances in thermoplastic composites will improve recyclability and reduce manufacturing costs.
- Mass-market vehicle adoption will increase with scalable, cost-effective composite production technologies.
- OEM-supplier partnerships will drive customized solutions for performance and efficiency gains.
- Asia-Pacific will maintain market leadership due to strong EV policies and manufacturing capacity.
- Europe will lead in sustainable composite innovation aligned with environmental regulations.
- North America will expand applications in high-performance and commercial vehicle segments.
- Hybrid material systems combining carbon fiber with metals will offer optimized strength-to-weight benefits.
- Automation in production processes will enhance output consistency and market scalability.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Automotive Carbon Fiber Composites Market?
What factors are driving the growth of the Automotive Carbon Fiber Composites Market?
What are some challenges faced by the Automotive Carbon Fiber Composites Market?
Who are the major players in the Automotive Carbon Fiber Composites Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Automotive Carbon Fiber Composites Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Automotive Carbon Fiber Composites Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 9,850 million → 2032: USD 13,274 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Automotive Carbon Fiber Composites Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Automotive Carbon Fiber Composites Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Automotive Carbon Fiber Composites Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Automotive Carbon Fiber Composites Market Drivers
- 3.3 Automotive Carbon Fiber Composites Market Restraints & Challenges
- 3.4 Automotive Carbon Fiber Composites Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Automotive Carbon Fiber Composites Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Automotive Carbon Fiber Composites Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Automotive Carbon Fiber Composites category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Automotive Carbon Fiber Composites Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Automotive Carbon Fiber Composites Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Automotive Carbon Fiber Composites market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Automotive Carbon Fiber Composites Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Automotive Carbon Fiber Composites Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Automotive Carbon Fiber Composites Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Automotive Carbon Fiber Composites (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Automotive Carbon Fiber Composites Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Automotive Carbon Fiber Composites Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Automotive Carbon Fiber Composites Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Automotive Carbon Fiber Composites Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Automotive Carbon Fiber Composites Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Automotive Carbon Fiber Composites Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Automotive Carbon Fiber Composites Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Automotive Carbon Fiber Composites Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Automotive Carbon Fiber Composites Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
