
Market Overview
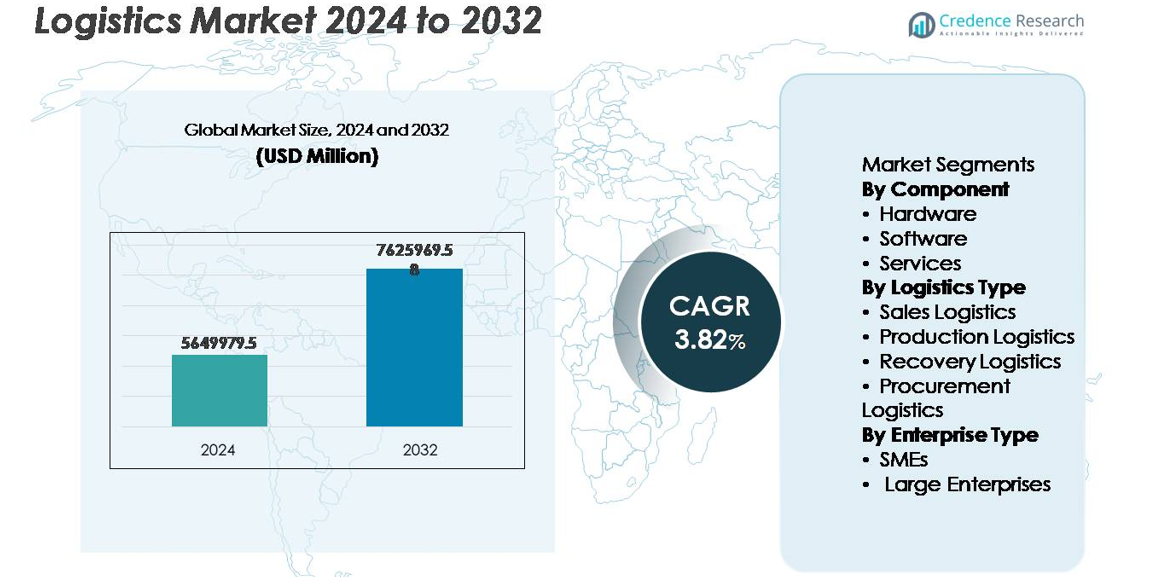
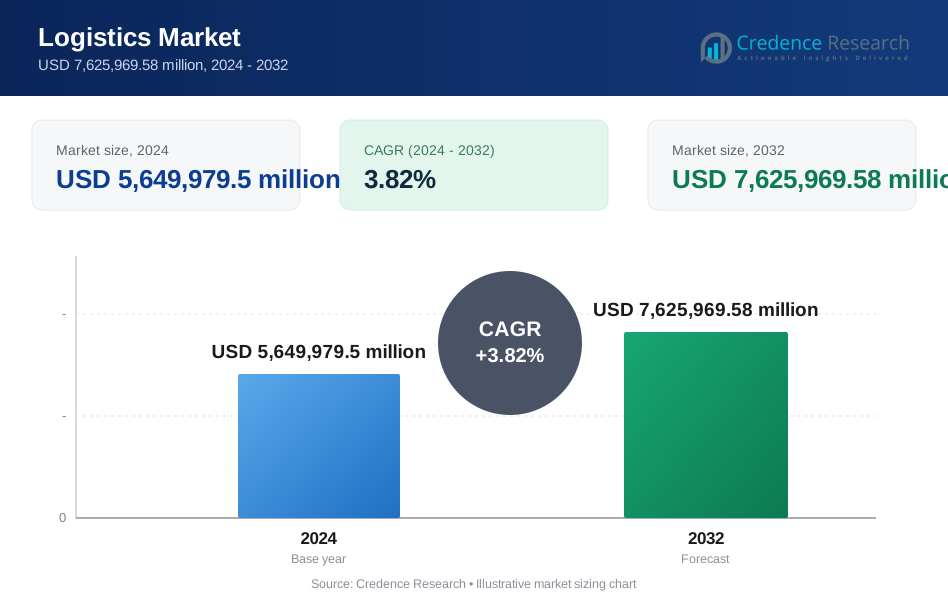
The global logistics market was valued at USD 5,649,979.5 million in 2024 and is projected to reach USD 7,625,969.58 million by 2032, expanding at a CAGR of 3.82% over the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Logistics Market Size 2024 | USD 5,649,979.5 million |
| Logistics Market, CAGR | 3.82% |
| Logistics Market Size 2032 | USD 7,625,969.58 million |
The logistics market is shaped by a mix of global automation leaders and specialized system integrators, including Knapp, Murata Machinery, SSI SCHAEFER Group, Daifuku Co., Ltd., Jungheinrich AG, Honeywell International Inc., KION Group AG, Toyota Industries Corporation, TGW Logistics Group, and KUKA AG. These companies compete through warehouse robotics, autonomous material handling, data-driven fleet optimization, and integrated storage and retrieval systems. Asia-Pacific leads the logistics market with approximately 38% share, driven by large-scale manufacturing, port expansions, e-commerce penetration, and multimodal infrastructure growth. North America and Europe continue to invest heavily in automation and sustainability as part of supply chain transformation.
Market Insights
- The global logistics market was valued at USD 5,649,979.5 million in 2024 and is projected to reach USD 7,625,969.58 million by 2032, reflecting a CAGR of 3.82% during the forecast period.
- Market growth is driven by rising automation adoption, digitally optimized fulfillment networks, and increasing demand for e-commerce based last-mile delivery services across developed and emerging economies.
- Key trends include AI-enabled route optimization, sustainable fleet transition, multimodal digital freight platforms, and the expansion of smart warehousing powered by robotics and IoT tracking.
- Competitive dynamics are shaped by global logistics integrators and technology players focusing on resilient supply chains, though infrastructure disparity and cybersecurity risks remain significant restraints.
- Asia-Pacific dominates with around 38% share, followed by North America at 32% and Europe at 27%, while the hardware segment leads by component, supported by warehouse automation and advanced handling systems.
Market Segmentation Analysis:
By Component
The logistics market is segmented into hardware, software, and services, with the hardware segment holding the dominant market share, driven by the increasing adoption of advanced automation systems, barcode and RFID systems, autonomous mobile robots, and sensor-enabled tracking infrastructure. Investments in warehouse modernization and fulfillment center robotics continue to accelerate hardware demand as enterprises prioritize labor optimization, faster order processing, and accuracy improvements. Meanwhile, software platforms supporting real-time visibility, predictive analytics, and transportation management are rapidly scaling in adoption, complemented by expanding service offerings related to integration, maintenance, and managed operations.
- For instance, Zebra Technologies reported that its FX9600 fixed RFID reader is capable of processing up to 1,200 tag reads per second, supporting high-density inventory environments such as large fulfillment hubs.
By Logistics Type
Based on logistics type, the market is categorized into sales logistics, production logistics, recovery logistics, and procurement logistics. Production logistics represents the leading sub-segment, owing to the rising need for synchronized material movement, just-in-time supply processes, and factory floor integration within manufacturing ecosystems. Increased reliance on digital twins, automated production flows, and demand-driven planning models supports segment growth. Sales logistics is expanding with the surge in e-commerce fulfillment and last-mile delivery solutions, while procurement and recovery logistics benefit from circularity initiatives, reusable asset management, and reverse logistics frameworks supporting returns and recycling.
- "For instance, UPS’ automated Worldporthub in Louisville features a throughput capacity of 416,000 packages per hour across 155 miles of conveyors, demonstrating the scale of automated sales logistics fulfillment systems."
By Enterprise Type
The market by enterprise type is divided into SMEs and large enterprises, with large enterprises dominating the segment due to higher technology spending capacity, global distribution networks, and strategic adoption of warehouse automation and robotic process workflows. Large enterprises leverage integrated logistics automation to reduce operational risk, improve real-time visibility, and enhance resilience across multi-country supply chains. However, SMEs are emerging as a high-growth adopter segment, supported by cloud-based logistics platforms, subscription-based automation tools, and scalable inventory and transport management systems that reduce upfront capital expenditure and deployment complexity.
Key Growth Drivers:
Rising Adoption of Automation and Digital Supply Chain Technologies
Automation has become a foundational driver for logistics transformation as enterprises seek greater throughput efficiency, reduced human error, and faster fulfillment cycles. Robotics, autonomous mobile vehicles, AI-enabled route optimization, and digital twin–based warehouse simulations are accelerating process modernization. Cloud-integrated transport management systems and real-time freight visibility platforms enhance decision-making, supporting cost predictability and fleet utilization. The growth of e-commerce and the need for same-day delivery models reinforce demand for scalable automation. As organizations adopt predictive asset management, advanced scanning, and contactless documentation, digital ecosystems are redefining operational reliability and customer experience. This widespread shift positions automation as a long-term enabler of competitive differentiation.
- For instance, FedEx deployed SenseAware IoT sensor technology in more than 90 countries, tracking shipment temperature, light exposure, and location data with transmission intervals as frequent as every 5 minutes, supporting pharmaceutical and high-value asset logistics.
Expansion of Global Trade Flows and Cross-Border Distribution Networks
Trade liberalization, nearshoring strategies, and regional economic integration stimulate logistics market expansion by intensifying cross-border transportation requirements. The proliferation of digital marketplaces has widened the trade participation of SMEs, leading to a surge in multi-country shipping volumes and complex customs compliance workflows. Infrastructure investments-including smart ports, warehousing clusters, multimodal hubs, and cross-border corridors-support higher throughput capacity. Vendor diversification strategies implemented in response to supply chain interruptions have increased reliance on regional inventory centers, bonded warehouses, and flexible distribution models. As emerging markets strengthen their export manufacturing capabilities, logistics providers continue scaling intelligent freight management, customs automation, and multimodal connectivity.
- For instance, Panasonic Logistics utilizes an integrated, global logistics network (including owned facilities, 3PL partners, and various sales bases across Asia and other regions) to support diversified vendor sourcing and rapid replenishment requirements for electronics components.
Growth in E-commerce, Omni-channel Retail, and Last-mile Delivery Systems
E-commerce remains a critical catalyst reshaping logistics, driven by rapid order turnaround expectations, micro-fulfillment centers, and delivery personalization. Omni-channel models require unified inventory visibility, dynamic routing, and real-time communication between fulfillment partners and consumers. The expansion of grocery delivery, subscription-based models, and urban delivery formats has boosted adoption of electrified fleets, delivery lockers, and route-optimized dispatch platforms. Retailers are forming strategic partnerships with logistics technology providers to manage cost per delivery and enhance reverse logistics operations. As product returns and recycling initiatives grow, logistics providers integrate reverse flow capabilities into forward networks, strengthening circular supply chains.
Key Trends and Opportunities:
Shift Toward Sustainable, Green, and Circular Logistics Models
Sustainability-driven regulations, carbon transparency mandates, and resource efficiency targets are accelerating investment in low-emission fleets, route optimization software, and green warehousing infrastructure. Electric vehicles, hydrogen-powered trucks, and alternative marine fuels are transitioning from pilots to scale deployments. Packaging minimization, reusable containers, and recycling-enabled logistics models support circular manufacturing ecosystems. Carbon accounting platforms and blockchain-based traceability tools create verifiable environmental reporting. As enterprises prioritize ESG compliance and emission reduction goals, logistics stakeholders gain opportunities in carbon-neutral delivery, eco-optimized multimodal transport, and green last-mile solutions.
- For instance, DHL has deployed more than 32,000 electric vehicles across its logistics operations, supporting emission-reduction initiatives through electrified last-mile delivery networks in over 500 global cities.
Integration of AI-enabled Predictive, Autonomous, and Intelligent Operations
AI adoption is creating opportunities for predictive planning, demand sensing, autonomous navigation, and cognitive decision support across logistics workflows. Intelligent transport systems predict weather disruptions, congestion, and asset downtime, enabling proactive risk mitigation. Autonomous drones, robotic picking, and self-driving freight vehicles are progressing from test environments into commercial logistics corridors. AI-powered simulation improves warehouse layout efficiency and throughput planning. The fusion of computer vision, machine learning, and IoT sensors continues enhancing freight condition monitoring, safety compliance, and inventory accuracy. These advancements present significant opportunities for efficiency-driven logistics transformation.
- "For instance,Amazon has deployed more than 1,000 AI-enabledRobin robotic arms across its network to sort packages, and has introduced the Sparrow picking system, its first robot capable of identifying and handling millions of diverse, individual product SKUs (approximately 65% of the total catalog), supporting high-volume fulfillment operations"
Key Challenges:
Infrastructure Gaps, Fragmentation, and Uneven Digital Readiness
Infrastructure disparities across transport networks and warehousing ecosystems hinder logistics scalability. Fragmentation persists, particularly among small carriers and regional operators with limited access to automation capital. Congested ports, inadequate cold chain facilities, and limited multimodal connectivity delay shipment cycles and raise operational costs. Digital readiness remains uneven, with interoperability issues between legacy systems and modern platforms restricting real-time coordination. Variable regulatory policies and customs frameworks further contribute to delay and complexity, challenging seamless cross-border integration.
Rising Cybersecurity Risks and Data Privacy Vulnerabilities
As logistics networks grow more digitally connected, the exposure to cyber threats, ransomware, and data breaches intensifies. Supply chain management platforms store sensitive partner and customer information, making them attractive targets for malicious attacks. IoT devices, autonomous vehicles, and connected warehouse systems increase entry points for cyber exploitation. Lack of standardized cybersecurity frameworks and insufficient monitoring across distributed networks elevate compliance and risk mitigation costs. Data privacy regulations demand robust encryption, governance, and incident response structures, challenging logistics operators managing diverse global systems.
Regional Analysis
North America
North America holds approximately 32% of the logistics market share, driven by advanced warehouse automation, strong cold-chain networks, and mature third-party logistics ecosystems supporting retail, healthcare, and industrial distribution. The U.S. remains the core hub due to its expansive e-commerce activity and nationwide freight networks integrating road, air, and intermodal operations. Investment in autonomous freight vehicles, AI-enabled route optimization, and sustainable fleet transition strengthens the region’s innovation advantage. Cross-border trade with Mexico and Canada further supports multimodal expansion, particularly under nearshoring and manufacturing relocation strategies that favor local supply resiliency and reduced lead times.
Europe
Europe accounts for around 27% of the global logistics market, supported by established international trade corridors, port connectivity, and advanced regulatory frameworks governing freight safety and sustainability. The region benefits from dense urban logistics networks and investments in green transportation, electric fleets, and carbon compliance infrastructure. Germany and the Netherlands remain central logistics hubs, supported by high-volume warehouse capacity and digitally coordinated freight routes. EU circular economy policies accelerate demand for reusable packaging logistics and reverse supply flows. Ongoing challenges include rising cross-border documentation requirements and labor shortages across transport and warehousing operations.
Asia-Pacific
Asia-Pacific dominates the global logistics landscape with approximately 38% market share, driven by strong manufacturing output, rapid e-commerce penetration, and significant port and logistics infrastructure expansion. China, India, Japan, and Southeast Asian economies fuel demand through export manufacturing, industrial clusters, and resource flows supporting global supply chains. Government-backed investments in smart ports, digital customs, and multimodal freight corridors accelerate modernization. The region’s expanding middle-class consumption base propels last-mile delivery and fulfillment volume growth. However, infrastructure imbalances between urban and inland networks remain a challenge, creating opportunities for logistics automation and advanced capacity planning solutions.
Latin America
Latin America holds close to 2% market share, influenced by emerging e-commerce logistics, agrifood export channels, and regional trade alliances that support cross-border freight integration. Brazil and Mexico act as primary logistics centers with expanding warehousing and bonded distribution zones. Investments in rail connectivity, smart port development, and airport cargo handling are improving throughput capacity. Political volatility, customs delays, and inconsistent infrastructure quality across rural corridors continue to affect operational predictability and cost structures. Growth opportunities emerge in cold-chain networks, digital freight platforms, and sustainable fleet expansion targeting reduced fuel dependency.
Middle East & Africa
The Middle East & Africa region represents about 1% of the logistics market share, driven by energy exports, free trade zones, and rising investment in air cargo connectivity. Gulf nations are developing multimodal logistics hubs powered by bonded warehousing and customs digitization. Infrastructure corridors across Sub-Saharan Africa support agricultural and mining freight flows despite operational challenges from road quality, customs fragmentation, and technology maturity gaps. Logistics providers increasingly adopt fleet telematics, GPS tracking, and cloud platforms to enhance visibility. Strategic diversification initiatives in the Gulf region support logistics-based economic transformation and global distribution re-export models.
Market Segmentations:
By Component
- Hardware
- Software
- Services
By Logistics Type
- Sales Logistics
- Production Logistics
- Recovery Logistics
- Procurement Logistics
By Enterprise Type
- SMEs
- Large Enterprises
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The logistics market features a highly competitive landscape characterized by global integrators, regional third-party logistics providers, freight forwarders, and technology-driven entrants reshaping service models. Established players compete through diversified multimodal networks, scalable warehousing infrastructure, and end-to-end supply chain management offerings. Strategic focus areas include automation-enabled fulfillment, AI-driven fleet optimization, carbon-efficient operations, and cross-border regulatory compliance services. Technology providers increasingly collaborate with logistics operators to deploy real-time tracking platforms, predictive analytics, digital documentation, and autonomous delivery systems. Mergers, acquisitions, and strategic alliances remain prevalent as companies expand geographic footprints and service portfolios. Rising customer expectations for transparency, faster delivery, and sustainable logistics intensify innovation, compelling organizations to adopt next-generation supply chain solutions for resilient, cost-efficient, and digitally integrated operations.
Key Player Analysis
- Knapp (Austria)
- Murata Machinery, Ltd (Japan)
- SSI SCHAEFER Group (Germany)
- Daifuku Co., Ltd. (Japan)
- Jungheinrich AG (Germany)
- Honeywell International Inc. (U.S.)
- KION Group AG (Germany)
- Toyota Industries Corporation (Japan)
- TGW Logistics Group (Austria)
- KUKA AG (Germany)
Recent Developments
- In May 2025, KION opened a new highly automated spare-parts distribution center (Regional Distribution Center Central Europe) in Kahl am Main.
- In February 2024, Dematic entered into a partnership with Groupe Robert, a Canadian Logistics company. The partnership aimed to open an automated cold storage facility. The facility has a high-capacity Automated Storage and Retrieval System with 130-foot tall cranes for managing frozen and fresh foods.
- In November 2023: Knapp, an automation solution provider, partnered with Biogena, an Austrian Health Product company, to automate the processing of international shipping.
Report Coverage
The research report offers an in-depth analysis based on Component, Logistic type, Enterprise type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Automation and robotics will continue to transform warehousing, fulfillment speed, and workforce allocation.
- AI-driven predictive analytics will optimize demand forecasting, fleet utilization, and risk mitigation.
- Electrification and hydrogen-powered fleets will accelerate sustainable logistics and emissions reduction.
- Digital freight platforms will enhance transparency and real-time shipment collaboration.
- Autonomous vehicles and drones will expand pilot-stage operations into commercial logistics corridors.
- Blockchain-enabled traceability will support compliance, authenticity checks, and cross-border documentation.
- Smart port infrastructure will improve cargo flow, congestion management, and data connectivity.
- Circular logistics will grow through reusable packaging, reverse flows, and resource recovery.
- Edge computing and IoT sensors will strengthen asset monitoring and cold-chain reliability.
- Nearshoring and regional manufacturing shifts will reshape global distribution strategies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Adoption of Automation and Digital Supply Chain Technologies
Enterprises are increasingly investing in robotics, autonomous vehicles, and AI-driven platforms to improve throughput, reduce errors, and accelerate fulfillment cycles. This shift enables faster, more reliable logistics operations and supports the scalability required by modern supply chains.
Expansion of Global Trade Flows and Cross-Border Distribution Networks
Trade liberalization, nearshoring, and regional integration are driving demand for complex, cross-border logistics solutions. Investments in smart ports, multimodal hubs, and customs automation are enabling higher throughput and more flexible distribution models.
Growth in E-commerce, Omni-channel Retail, and Last-mile Delivery Systems
The surge in e-commerce and omni-channel retail is fueling demand for rapid, personalized delivery and unified inventory management. Logistics providers are expanding last-mile capabilities, micro-fulfillment centers, and reverse logistics to meet evolving consumer expectations.
Shift Toward Sustainable, Green, and Circular Logistics Models
Sustainability regulations and corporate ESG goals are accelerating the adoption of electric vehicles, green warehousing, and circular logistics practices. Investments in carbon-efficient operations and traceability tools are creating new opportunities for eco-optimized logistics services.
Integration of AI-enabled Predictive, Autonomous, and Intelligent Operations
AI and machine learning are transforming logistics by enabling predictive planning, autonomous navigation, and real-time risk mitigation. These technologies improve efficiency, safety, and responsiveness across transport and warehousing workflows.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Logistics market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Logistics market projected to grow between 2025 and 2032?
What are the primary factors fueling the growth of the Logistics market?
Who are the leading companies in the Logistics market?
Who are the leading companies in the logistics market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Component
- 1.2.1 Hardware
- 1.2.2 Software
- 1.2.3 Services
- 1.3 By Logistics Type
- 1.3.1 Sales Logistics
- 1.3.2 Production Logistics
- 1.3.3 Recovery Logistics
- 1.3.4 Procurement Logistics
- 1.4 By Enterprise Type
- 1.4.1 SMEs
- 1.4.2 Large Enterprises
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5,649,979.5 million → 2032: USD 7,625,969.58 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Logistics Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Logistics Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Logistics Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Logistics Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Logistics Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Logistics Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Logistics Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Logistics Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5,649,979.5 million → 2032: USD 7,625,969.58 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Logistics Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Component - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hardware
- 12.3.7.2 Software
- 12.3.7.3 Services
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Logistics Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Sales Logistics
- 12.4.7.2 Production Logistics
- 12.4.7.3 Recovery Logistics
- 12.4.7.4 Procurement Logistics
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Enterprise Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 SMEs
- 12.5.7.2 Large Enterprises
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Logistics Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Logistics Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Logistics Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Knapp
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Murata Machinery, Ltd
- 17.4 SSI SCHAEFER Group
- 17.5 Daifuku Co., Ltd.
- 17.6 Jungheinrich AG
- 17.7 Honeywell International Inc.
- 17.8 KION Group AG
- 17.9 Toyota Industries Corporation
- 17.10 TGW Logistics Group
- 17.11 KUKA AG
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

