
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Automotive Relays Market Size 2024 | USD 14,225 million |
| Automotive Relays Market, CAGR | 6% |
| Automotive Relays Market Size 2032 | USD 22,672.48 million |
Market Overview
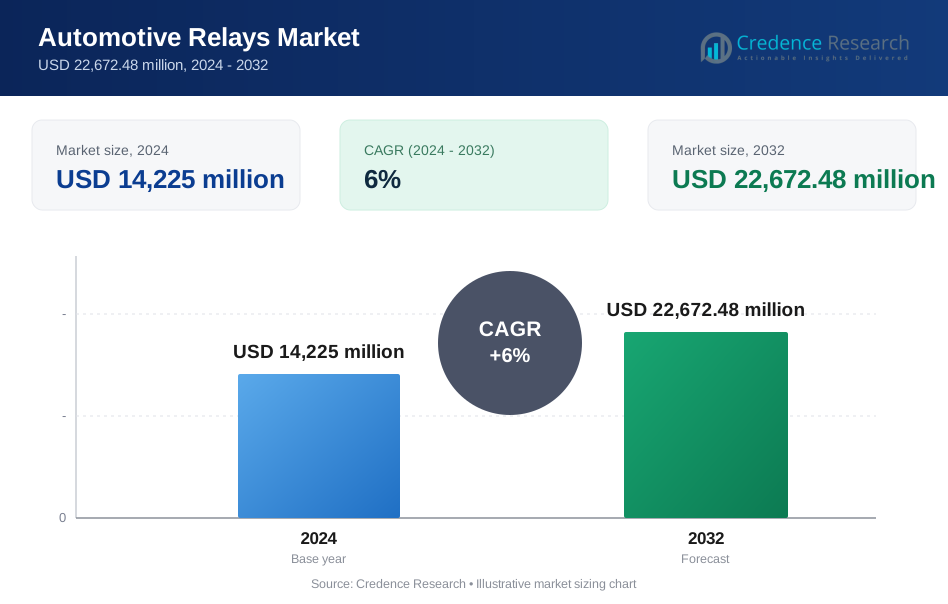
The automotive relays market is projected to grow significantly from USD 14,225 million in 2024 to USD 22,672.48 million by 2032, reflecting a compound annual growth rate (CAGR) of 6%.
The automotive relays market is driven by the increasing demand for advanced safety and convenience features in vehicles, leading to greater reliance on electronic components. The rise of electric and hybrid vehicles further fuels this growth, as these vehicles require more relays to manage various electrical systems. Additionally, the integration of smart technologies and the push for vehicle automation enhance the need for reliable automotive relays. Trends such as the adoption of lightweight materials and enhanced energy efficiency also contribute to market expansion, ensuring that automotive relays continue to play a critical role in modern vehicle design and functionality.
The geographical analysis of the automotive relays market highlights significant growth in regions such as North America and Asia-Pacific, driven by increasing vehicle production and technological advancements. North America accounts for approximately 30% of the market, propelled by strong automotive manufacturing and a focus on safety features. In contrast, the Asia-Pacific region leads with about 35% market share, fueled by rapid industrialization and rising demand for electric vehicles. Key players in this market include ABB, DENSO CORPORATION, Eaton, Sensata Technologies, and Hella KGaA Hueck & Co., which are actively innovating to meet evolving automotive needs.
Market Drivers
Rising Connectivity and Vehicle Digitalization
The trend towards connected vehicles and vehicle digitalization is another critical driver of the automotive relays market. Features such as remote diagnostics and over-the-air updates necessitate the incorporation of additional electrical components, including relays. For instance, it is projected that by 2025, there will be over 400 million connected cars in operation. Furthermore, as autonomous vehicles gain traction, their increasingly complex electrical systems will require a robust network of relays to ensure reliable operation. This escalating demand for connectivity and automation will continue to shape the automotive relays market in the coming years.
Rising Adoption of Advanced Driver Assistance Systems (ADAS)
The increasing adoption of Advanced Driver Assistance Systems (ADAS) is significantly driving the demand for automotive relays. Features such as lane departure warning, adaptive cruise control, and automatic emergency braking require intricate electrical systems that depend heavily on relays for effective control. For instance, approximately 33% of new vehicles sold in major markets like the United States, Europe, Japan, and China are equipped with ADAS. Moreover, the growing emphasis on vehicle safety has led to a surge in ADAS implementations, further boosting the need for reliable automotive relays. As manufacturers enhance their focus on safety, the reliance on these components will continue to rise, shaping the automotive landscape.
Growth in Electric and Hybrid Vehicles
The shift towards electric and hybrid vehicles is reshaping the automotive relays market by introducing more complex electrical systems compared to traditional internal combustion engine (ICE) vehicles. These advancements necessitate a higher number of relays for managing power distribution and control effectively. For instance, nearly one in five cars sold in 2023 was electric, highlighting the rapid growth in this sector. Additionally, relays play a crucial role in battery management systems, ensuring the safe and efficient operation of electric vehicles. As the adoption of electric and hybrid models increases, the demand for specialized relays tailored to these complex power management needs will grow.
Increasing Demand for Comfort and Convenience Features
Modern vehicles are increasingly equipped with advanced comfort and convenience features, such as sophisticated infotainment systems, power windows, seats, and mirrors. These systems rely on automotive relays for the seamless operation of various electrical components. As consumer expectations for in-car technology and comfort continue to rise, manufacturers will be compelled to integrate more relays to support these functionalities, driving overall market growth.
Market Trends
Miniaturization, Lightweighting, and Enhanced Functionality
The automotive industry is experiencing a significant trend toward miniaturization and lightweighting, driven by the demand for smaller, more efficient vehicles. For instance, advancements in materials such as high-strength steel and aluminum alloys are enabling manufacturers to develop smaller and lighter relays. As space constraints become increasingly critical, manufacturers are developing smaller and lighter relays to optimize vehicle design without compromising performance. This trend is coupled with advancements in materials and design techniques, allowing for the creation of relays that maintain high functionality while reducing weight. Additionally, there is a growing emphasis on integrating multiple functions into a single relay, a process known as multiplexing. This integration not only minimizes the number of relays required but also enhances the overall efficiency of electrical systems in vehicles. Smart relays equipped with built-in diagnostics and monitoring capabilities are becoming more common, offering improved reliability and reduced maintenance costs. This focus on multifunctionality reflects the industry's shift towards more compact and integrated solutions, aligning with modern vehicle requirements.
Increasing Demand for Performance and Sustainability
The rising complexity of electrical systems in Advanced Driver Assistance Systems (ADAS) and electric vehicles has created a demand for relays with higher switching speeds and frequencies. These advancements are essential for handling the sophisticated requirements of contemporary automotive applications, and improvements in semiconductor technology are facilitating the development of relays with faster switching times. Furthermore, the automotive sector is increasingly focusing on reliability and durability, given that relays operate in harsh environments characterized by extreme temperatures, vibrations, and moisture. Manufacturers are implementing rigorous testing and certification processes to ensure that relays meet stringent quality standards and can withstand these challenging conditions.
Simultaneously, the growing demand for Solid-State Relays (SSRs) is notable, as they offer several advantages over traditional electromechanical relays, including faster switching speeds, longer operational life, and reduced noise. SSRs are particularly favored in applications where high reliability and longevity are critical, such as battery management systems and powertrain control.
Market Challenges Analysis
Rising Costs of Raw Materials and Supply Chain Risks
The automotive relay market faces significant challenges stemming from the rising costs of raw materials and supply chain disruptions. Fluctuations in the prices of essential materials, such as copper, silver, and plastics, can adversely affect production costs for relay manufacturers. For instance, the cost of raw materials in an average U.S. vehicle has increased significantly, with the price of steel rising by 106% year over year. As material costs continue to increase, manufacturers find themselves grappling with higher component prices, which directly impacts their profitability. Additionally, supply chain risks pose a substantial threat, as disruptions-whether caused by natural disasters, geopolitical tensions, or transportation issues-can hinder the availability of crucial raw materials and components. This reliance on a limited number of suppliers further amplifies the risk; if any of these suppliers encounter difficulties, it can lead to production delays and increased operational costs, further straining manufacturers in an already competitive landscape.
Intense Competition and Stringent Compliance Standards
Intense competition within the automotive relay market presents another formidable challenge. With numerous global players striving for market share, manufacturers face relentless pressure to lower prices, which can compromise their profitability. The rapid pace of technological advancements also contributes to this competitive environment, leading to product obsolescence and necessitating ongoing investments in research and development. Short product life cycles further complicate matters, as manufacturers may struggle to recoup their investments before new technologies render their offerings outdated. Additionally, the need to comply with stringent quality and safety standards imposes further challenges. Automotive relays must meet rigorous requirements to ensure the reliability and performance of vehicles, which can involve costly and time-consuming testing and certification processes. Top of Form
Market Segmentation Analysis:
By Product:
The automotive relays market can be segmented by product types, including PCB relays, plug-in relays, high voltage relays, and others. PCB relays are widely used in various automotive applications due to their compact size and reliability, making them ideal for space-constrained environments. Plug-in relays offer versatility and ease of replacement, appealing to manufacturers and service providers seeking efficient solutions. High voltage relays, essential for electric and hybrid vehicles, handle increased electrical demands, contributing to their growing adoption in these segments. Additionally, the "Others" category encompasses specialized relays designed for specific applications, further expanding the market landscape. As the automotive industry increasingly embraces advanced technologies and electrification, the demand for these diverse relay types will continue to rise, driving innovation and competition among manufacturers.
By Vehicle Type:
The automotive relays market can also be segmented based on vehicle type, comprising passenger vehicles, commercial vehicles, and electric vehicles. Passenger vehicles dominate the market, driven by the rising adoption of advanced safety and comfort features that necessitate a higher number of relays. Commercial vehicles, including trucks and buses, are experiencing increased relay demand due to the integration of advanced telematics and fleet management systems. Electric vehicles are a rapidly growing segment, requiring specialized relays for battery management systems and high voltage applications. As consumer preferences shift towards eco-friendly transportation, the demand for relays tailored to electric vehicles will surge. Each vehicle type presents unique challenges and opportunities, prompting manufacturers to develop innovative relay solutions that meet the evolving requirements of the automotive sector, ensuring long-term growth and sustainability in the market.
Segments:
Based on Product:
- PCB Relay
- Plug-in Relay
- High Voltage Relay
- Others
Based on Vehicle Type
- Passenger Vehicles
- Commercial Vehicles
- Electric Vehicles
Based on Application:
- Resistive Loads
-
-
- HVAC
-
- Capacitive Loads
-
-
- Engine Management Module
-
-
-
- Fog Lights
-
-
-
- ABS Module
-
-
-
- Front and Rear Beam
-
- Inductive Loads
-
-
- Power Window
-
-
-
- Central Lock
-
-
-
- Cooling Fan
-
-
-
- Clutches
-
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a significant share of the automotive relays market, accounting for approximately 30% of the global market. This dominance can be attributed to the region's strong automotive manufacturing base, particularly in the United States, where major automobile manufacturers and suppliers are concentrated. The increasing focus on advanced driver assistance systems (ADAS) and electric vehicle adoption is driving the demand for automotive relays in North America. Moreover, the presence of key players investing in research and development to create innovative relay solutions is further enhancing market growth. The rising emphasis on vehicle safety and comfort features, coupled with stringent regulatory standards, is also propelling the demand for reliable and efficient automotive relays in the region.
Asia-Pacific
The Asia-Pacific region is expected to witness the highest growth in the automotive relays market, with a projected market share of around 35% over the next few years. This growth is primarily driven by the rapid expansion of the automotive industry in countries like China, India, and Japan, where both electric and traditional vehicles are gaining popularity. The region's increasing urbanization and rising disposable incomes are fostering a demand for advanced automotive technologies, including ADAS and enhanced comfort features. Additionally, the government initiatives aimed at promoting electric vehicle adoption are further boosting the demand for automotive relays, especially high voltage relays. The Asia-Pacific market is characterized by intense competition among manufacturers, leading to continuous innovations and advancements in relay technologies to meet the diverse needs of the automotive sector, ensuring robust market expansion in the coming years.
Key Player Analysis
- ABB
- Deltrol Controls (Deltrol Corporation)
- Eaton
- COTO TECHNOLOGY
- DENSO CORPORATION
- Littelfuse Inc.
- American Zettler, Inc. (Zettler Components, Inc.)
- GOOD SKY ELECTRIC CO., LTD.
- Hella KGaA Hueck & Co. (HELLA)
- BETA ELECTRIC INDUSTRY CO., LTD
- IDEC Corporation
- Megatone Electronics Corp.
- LS Automotive Technologies
- Sensata Technologies Holdings N.V
Competitive Analysis
The competitive landscape of the automotive relays market is characterized by several leading players striving for innovation and market share. ABB, DENSO CORPORATION, Eaton, Sensata Technologies, Hella KGaA Hueck & Co., Littelfuse Inc., and LS Automotive Technologies are at the forefront of this industry, each leveraging advanced technology to enhance product reliability and efficiency. Companies are increasingly investing in research and development to create innovative relay designs that meet the demands of modern vehicles, including advanced driver assistance systems (ADAS) and electric vehicle applications. Strategic partnerships and acquisitions are common as firms seek to strengthen their market positions and expand their product portfolios. Furthermore, the emphasis on sustainability and energy efficiency is driving competition, with manufacturers developing eco-friendly products and implementing sustainable practices in their operations. This dynamic environment is shaping the automotive relays market, pushing companies to continuously improve their offerings to cater to evolving consumer and regulatory demands.
Recent Developments
- In March 2023, Panasonic Industry Europe GmbH launched its latest relay, the HE-R, which has undergone extensive testing for enhanced short-circuit performance. This relay is designed to provide a reliable and safe solution for electric vehicle (EV) charging industry customers. The HE-R relay has successfully passed the rigorous IEC62955 test, which involves a demanding 10kA short circuit assessment. Furthermore, the smaller HE-S relay complies with the IEC62955 standard for 3kA short circuits.
- In February 2023, ABB launched the Relay Retrofit Program, which aims to replace specific SPACOM protection relays with advanced REX610 protection and control technology. The all-in-one REX610 relay is specifically designed to accommodate the changing requirements of modern power grids, making it a versatile, environmentally friendly, and future-ready option. The Retrofit Program enables customers to schedule and implement their retrofit projects in stages, ensuring prompt replacement while minimizing disruptions to production or power distribution operations
- In May 2022, Texas Instruments launched a new range of solid-state relays to enhance the safety of electric vehicles (EVs). This portfolio includes isolated drivers and switches that meet automotive standards, ensuring exceptional reliability. Furthermore, these isolated solid-state relays offer the smallest solution size available in the market, effectively reducing the cost of bill-of-materials (BOM) and powertrain expenses for 800-V battery-management systems.
- In January 2022, Toshiba Electronics Europe GmbH (TOSHIBA ELECTRONIC DEVICES & STORAGE CORPORATION) launched a novel photo relay designed for various applications in battery-powered and hybrid-electric vehicles. TLX9160T is a normally open (NO) 1-Form-A relay specifically developed for battery management systems (BMS), ground fault detection, and identification of faults with mechanical relays. The TLX9160T can also operate from a supply voltage (VDD) of up to 1000V, making it compatible with most traction batteries commonly used in the industry.
Market Concentration & Characteristics
The automotive relays market exhibits moderate to high concentration, driven by the presence of a few dominant players alongside numerous smaller firms. This competitive environment fosters innovation as major manufacturers invest heavily in research and development to create advanced relay technologies that meet the evolving demands of the automotive industry, particularly in safety and electrification. Key characteristics of the market include a strong emphasis on reliability and durability, as automotive relays must perform effectively under harsh operating conditions. Additionally, the increasing integration of advanced driver assistance systems (ADAS) and electric vehicles necessitates more sophisticated relay designs, further influencing market dynamics. The market is also characterized by a growing focus on sustainability, with manufacturers exploring eco-friendly materials and production processes to align with global environmental regulations. Overall, the interplay of competition, technological advancement, and regulatory compliance shapes the landscape of the automotive relays market, driving continuous growth and innovation.Top of Form
Report Coverage
The research report offers an in-depth analysis based on Product, Vehicle Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The automotive relays market is expected to experience steady growth, driven by increasing vehicle production and technological advancements.
- The rise in electric and hybrid vehicle adoption will significantly boost demand for high voltage and specialized relays.
- Advanced driver assistance systems (ADAS) will continue to influence the market, leading to more sophisticated relay designs.
- Manufacturers will increasingly focus on developing energy-efficient and sustainable relay solutions to meet environmental regulations.
- The integration of smart relays with diagnostic capabilities will enhance reliability and reduce maintenance costs.
- Competitive pressures will drive innovation, prompting companies to invest in research and development for advanced relay technologies.
- Geographic expansion into emerging markets will present new opportunities for growth and market penetration.
- The trend toward vehicle electrification will necessitate the development of relays that can handle higher switching speeds and frequencies.
- Strategic partnerships and collaborations among key players will facilitate the sharing of technology and resources, enhancing market competitiveness.
- The ongoing evolution of automotive technologies will require continuous adaptation from relay manufacturers to stay relevant in the market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Connectivity and Vehicle Digitalization
The increasing integration of connected technologies and digital systems in vehicles, such as remote diagnostics and over-the-air updates, is driving demand for more relays to manage complex electrical architectures. As vehicles become more connected and automated, the need for reliable relay networks grows.
Growth in Electric and Hybrid Vehicles
The shift toward electric and hybrid vehicles introduces more complex and high-voltage electrical systems, requiring a greater number and variety of relays for power management and safety. The rapid adoption of EVs and hybrids is significantly boosting demand for specialized automotive relays.
Adoption of Advanced Driver Assistance Systems (ADAS)
The proliferation of ADAS features like lane departure warning, adaptive cruise control, and emergency braking necessitates intricate electrical control, heavily reliant on relays. As safety and automation features become standard, the market for automotive relays expands.
Increasing Demand for Comfort and Convenience Features
Modern vehicles are equipped with advanced infotainment, power windows, seats, and mirrors, all of which depend on relays for seamless operation. Rising consumer expectations for in-car technology and comfort are compelling manufacturers to integrate more relays.
Miniaturization and Enhanced Functionality
Automotive manufacturers are demanding smaller, lighter, and multifunctional relays to optimize space and efficiency in vehicle design. Innovations in relay technology, including smart relays with diagnostics, are supporting the trend toward compact, integrated automotive systems.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the size of Automotive Relays Market?
What factors are driving the growth of the Automotive Relays market?
What are the key segments within the Automotive Relays market?
Who are the major players in this market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 PCB Relay
- 1.2.2 Plug-in Relay
- 1.2.3 High Voltage Relay
- 1.2.4 Others
- 1.3 By Application
- 1.3.1 Resistive Loads (HVAC, Engine Management Module, Fog Lights, ABS Module, Front and Rear Beam)
- 1.3.2 Inductive Loads (Power Window, Central Lock, Cooling Fan, Clutches)
- 1.3.3 Capacitive Loads
- 1.4 By Vehicle Type
- 1.4.1 Passenger Vehicles
- 1.4.2 Commercial Vehicles
- 1.4.3 Electric Vehicles
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 14,225 million → 2032: USD 22,672.48 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Automotive Relays Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Automotive Relays Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Automotive Relays Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Automotive Relays Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Automotive Relays Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Automotive Relays Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Automotive Relays Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Automotive Relays Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 14,225 million → 2032: USD 22,672.48 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Automotive Relays Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 PCB Relay
- 12.3.7.2 Plug-in Relay
- 12.3.7.3 High Voltage Relay
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Resistive Loads (HVAC, Engine Management Module, Fog Lights, ABS Module, Front and Rear Beam)
- 12.4.7.2 Inductive Loads (Power Window, Central Lock, Cooling Fan, Clutches)
- 12.4.7.3 Capacitive Loads
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Vehicle Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Passenger Vehicles
- 12.5.7.2 Commercial Vehicles
- 12.5.7.3 Electric Vehicles
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Automotive Relays End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Automotive Relays Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Automotive Relays Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Automotive Relays Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 ABB
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 DENSO CORPORATION
- 18.4 Eaton
- 18.5 Sensata Technologies
- 18.6 Hella KGaA Hueck & Co.
- 18.7 Littelfuse Inc.
- 18.8 LS Automotive Technologies
- 18.9 Panasonic Industry
- 18.10 Texas Instruments
- 18.11 Toshiba Electronics
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

