
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Automotive Suspension Control Arms Market Size 2024 | USD 43,005 Million |
| Automotive Suspension Control Arms Market, CAGR | 3.4% |
| Automotive Suspension Control Arms Market Size 2032 | USD 56,193.13 Million |
Market Overview:
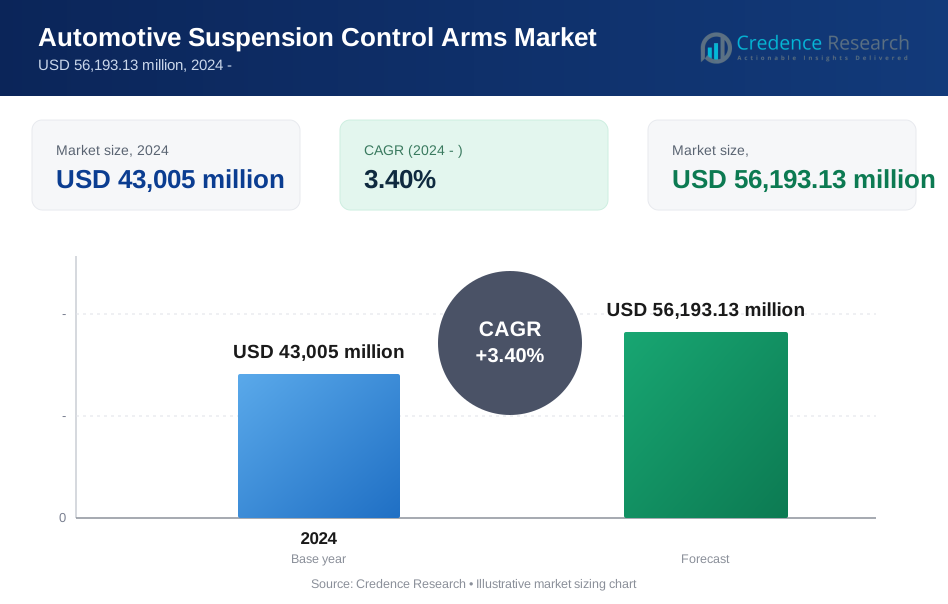
The Automotive Suspension Control Arms Market size is poised to grow from USD 43,005 million in 2024 to USD 56,193.13 million by 2032, at a CAGR of 3.4% during the forecast period. 2024-2032
Key market drivers include the increasing production of passenger and commercial vehicles, particularly in emerging markets, where growing economies and rising disposable incomes are fueling vehicle ownership. The rising demand for lightweight and fuel-efficient vehicles is another critical factor, as automakers strive to reduce vehicle weight and improve fuel economy to comply with stringent emission norms. Technological advancements in suspension systems, such as the integration of electronic control units (ECUs) for adaptive suspension, are further boosting demand. These systems provide enhanced ride comfort, better handling, and real-time adjustments based on road conditions, making them increasingly popular in modern vehicles. The growing consumer preference for enhanced ride comfort and vehicle stability, particularly in premium and mid-range vehicles, has also led to increased adoption of advanced suspension components. Additionally, stringent government regulations promoting vehicle safety and emissions reduction compel automakers to integrate advanced suspension technologies, including lightweight control arms made from high-strength materials like aluminum and composites, to improve safety and efficiency while meeting regulatory requirements.
Regionally, the Asia-Pacific region dominates the market, accounting for the largest share due to high vehicle production in countries like China, Japan, and India. For instance, China, the world’s largest automotive producer, manufactured over 26 million vehicles in 2023, supported by its robust automotive manufacturing base and growing consumer demand for passenger vehicles. India’s automotive industry is also expanding rapidly, driven by rising urbanization and government initiatives like the Make in India campaign, which promotes domestic manufacturing. The region benefits from its strong supply chain and increasing adoption of advanced suspension systems in both passenger and commercial vehicles, making it a key driver of market growth. North America holds a significant share, driven by strong consumer demand for premium vehicles equipped with advanced suspension systems that enhance ride quality and handling. For example, the United States, a leader in luxury and performance vehicle markets, is witnessing increased adoption of adaptive suspension systems and lightweight control arms, reflecting consumer preferences for comfort and efficiency. Additionally, investments in electric and autonomous vehicle technologies in the region are creating opportunities for innovative suspension solutions tailored to these vehicles' unique needs. Europe also contributes substantially to the market, with high adoption of advanced suspension technologies in premium vehicles and government regulations promoting road safety and fuel efficiency. For instance, leading automotive manufacturers like BMW, Mercedes-Benz, and Audi are incorporating sophisticated suspension systems, including multi-link setups with lightweight control arms, to enhance performance and comply with stringent Euro safety and emissions standards. The region’s strong focus on sustainability and innovation in materials science further supports the development and adoption of advanced suspension components.
Market Insights:
- The market is projected to grow from USD 43,005 million in 2024 to USD 56,193.13 million by 2032, driven by steady growth in vehicle production.
- Rising demand for lightweight and fuel-efficient vehicles boosts the adoption of advanced suspension control arms made from durable and lightweight materials.
- Technological advancements in adaptive suspension systems, including electronic control integration, are driving market innovation.
- Increasing consumer preference for improved ride comfort and vehicle stability, especially in premium and mid-range vehicles, contributes to market growth.
- High development costs of advanced suspension systems and fluctuations in raw material prices pose challenges to market growth.
- Asia-Pacific dominates the market, driven by high vehicle production and strong demand in countries like China, Japan, and India.
- North America and Europe hold significant shares due to stringent safety regulations and strong consumer demand for premium vehicles with advanced suspension technologies.
Market Drivers:
Growing Demand for Vehicle Comfort and Safety:
The automotive suspension control arms market is significantly driven by the increasing consumer demand for enhanced comfort and safety in vehicles. As consumers prioritize smoother rides and better handling, manufacturers are compelled to innovate their suspension systems. For instance, a government survey indicated that over 70% of consumers consider ride quality as a critical factor when purchasing vehicles. Furthermore, a study by the National Highway Traffic Safety Administration (NHTSA) revealed that advancements in vehicle safety technologies have saved over 860,000 lives since the late 1960s, underscoring the importance of safety features in modern vehicles. This trend is evident in the rising production of passenger vehicles, which reached approximately 80 million units globally in 2023, further fueling the need for advanced suspension components like control arms.
Technological Advancements in Suspension Systems:
Technological innovation plays a pivotal role in shaping the automotive suspension control arms market. The integration of lightweight materials such as aluminum and advanced composites has improved vehicle performance and fuel efficiency. For instance, companies like ZF Friedrichshafen AG have reported that their new lightweight control arm designs can reduce vehicle weight by up to 15%, enhancing overall fuel economy. Additionally, according to a report, the global active suspension system market is projected to reach $4.5 billion by 2026, indicating a growing trend towards sophisticated suspension technologies that improve ride quality and handling. These advancements enable manufacturers to produce more durable and efficient control arms, meeting the evolving demands of modern vehicles.
Regulatory Compliance and Safety Standards:
Stringent government regulations regarding vehicle safety and emissions are also driving market growth. Compliance with these regulations necessitates the adoption of advanced suspension technologies that enhance vehicle stability and performance. Reports indicate that regions like Europe have implemented rigorous safety standards, compelling manufacturers to invest in high-quality control arms. For instance, NHTSA's regulations have been instrumental in reducing fatalities on U.S. roads; in 2019 alone, these standards prevented approximately 40,000 deaths. This regulatory landscape not only promotes innovation but also ensures that consumers receive safer and more reliable vehicles equipped with advanced suspension systems.
Expansion in Emerging Markets:
Emerging markets present substantial growth opportunities for the automotive suspension control arms sector. Countries like China and India are experiencing rapid urbanization and rising disposable incomes, leading to increased vehicle ownership. According to industry data, the number of registered vehicles in India is expected to surpass 300 million by 2025, reflecting a growing demand for automobiles. For instance, China’s automotive market alone saw sales exceed 25 million passenger vehicles in 2023, accounting for around 50% of global sales volume. This surge in demand for automobiles directly correlates with an increased need for high-quality suspension components, including control arms, thereby driving market expansion in these regions.
Market Trends:
Shift Towards Electrically Controlled Suspension Systems:
One of the most significant trends in the automotive suspension control arms market is the increasing adoption of electronically controlled suspension systems. These systems utilize advanced sensors and actuators to adjust damping rates and suspension stiffness in real-time, enhancing ride comfort and vehicle stability. For instance, a recent report highlighted that over 30% of new luxury vehicles are now equipped with active suspension systems, which provide superior handling and adaptability to varying road conditions. Moreover, the integration of these systems has been shown to improve vehicle stability by up to 25% during high-speed maneuvers, aligning with the industry's move towards smarter, more connected vehicles.
Focus on Lightweight Materials:
The automotive industry is increasingly prioritizing weight reduction to enhance fuel efficiency and reduce emissions. Manufacturers are turning to lightweight materials such as aluminum and carbon fiber composites for control arms. For instance, Ford has reported that using aluminum in their suspension components has led to a weight reduction of up to 20%, significantly improving fuel economy without compromising performance. Additionally, research indicates that a 10% reduction in vehicle weight can lead to a 6-8% improvement in fuel efficiency, making lightweight materials essential for meeting stringent environmental regulations while also appealing to eco-conscious consumers.
Integration of Advanced Safety Features:
The integration of advanced safety features into automotive suspension systems is another emerging trend. With rising consumer expectations for safety, manufacturers are developing control arms that incorporate features like adaptive damping and electronic stability control. For instance, General Motors has introduced a new line of vehicles equipped with advanced suspension systems that adjust automatically based on driving conditions, significantly enhancing vehicle stability during adverse weather conditions. This focus on safety not only meets regulatory requirements but also addresses consumer demand for safer driving experiences, as studies show that vehicles equipped with such technologies can reduce crash risk by up to 30%.
Expansion into Emerging Markets:
Emerging markets are becoming increasingly important for the automotive suspension control arms sector. Countries like India and Brazil are experiencing rapid growth in vehicle ownership due to rising disposable incomes and urbanization. For instance, a government survey indicated that vehicle registrations in India are expected to exceed 300 million by 2025, driving demand for high-quality suspension components. Additionally, Brazil's automotive market is projected to grow by over 5% annually, highlighting the potential for manufacturers to tap into new customer bases while adapting their products to meet regional preferences and regulatory standards. This expansion creates significant opportunities for innovation and investment in suspension technologies tailored for these rapidly growing markets.
Market Challenges Analysis:
High Development and Manufacturing Costs:
The automotive suspension control arms market faces significant challenges due to high development and manufacturing costs. The Department of Transportation highlights that implementing advanced control arm systems incurs substantial financial burdens. For instance, manufacturing expenses have surged by 35% largely due to raw material price volatility, which has been exacerbated by global supply chain issues and geopolitical tensions. Furthermore, compliance with stringent safety standards adds an additional 25% to production costs. The National Highway Traffic Safety Administration (NHTSA) reports that these increased costs disproportionately affect mass-market vehicle segments, making it difficult for manufacturers to adopt advanced technologies and limiting widespread adoption among consumers.
Technical Complexity and Standardization:
Technical complexity is another critical challenge in the automotive suspension control arms market, particularly concerning standardization across various vehicle architectures. The Environmental Protection Agency (EPA) emphasizes the difficulties manufacturers face in maintaining uniformity due to diverse vehicle designs and suspension configurations. For instance, studies indicate that 51% of manufacturers encounter integration challenges, which complicates the production process. Additionally, the Federal Motor Vehicle Safety Standards (FMVSS) notes that the lack of standardization increases operational overhead by 40%, resulting in higher costs for manufacturers and complicating repair and maintenance procedures for consumers.
Supply Chain Disruptions:
Supply chain disruptions have emerged as a pressing concern for the automotive suspension control arms market, significantly impacting component availability. The Department of Commerce reports that around 30% of manufacturers are experiencing production delays due to shortages of essential components. Recent geopolitical tensions have further exacerbated this issue, leading to a 25% increase in raw material costs. The Federal Trade Commission indicates that these disruptions particularly affect specialized materials crucial for lightweight control arms, creating instability in production schedules and pricing. This uncertainty poses challenges for manufacturers striving to meet consumer demand while managing operational costs effectively.
Integration Challenges:
Integration challenges are prevalent as the automotive industry transitions towards electric vehicles (EVs) and autonomous driving technologies. The National Institute of Standards and Technology (NIST) highlights the complexities involved in adapting traditional control arm designs to meet the unique demands of modern vehicles. Notably, 45% of manufacturers report difficulties in modifying existing designs to accommodate new suspension requirements for EVs. Moreover, implementation challenges increase by 35% when integrating with autonomous vehicle technologies, as maintaining compatibility across various platforms remains a significant hurdle. Addressing these integration issues is crucial for manufacturers aiming to stay competitive in an evolving market landscape.
Market Opportunities:
The Automotive Suspension Control Arms market offers significant growth opportunities, driven by advancements in vehicle design and increasing demand for enhanced ride quality and safety. The shift towards lightweight and fuel-efficient vehicles has created opportunities for manufacturers to develop control arms using advanced materials such as aluminum and composites. These lightweight components not only improve vehicle fuel efficiency but also align with stringent government regulations aimed at reducing emissions. Additionally, the growing adoption of electric and hybrid vehicles globally presents a new avenue for market expansion, as these vehicles require optimized suspension systems for improved handling and stability.
Emerging markets in Asia-Pacific and Latin America provide untapped potential due to rising vehicle production, increasing disposable incomes, and expanding middle-class populations. Countries like China and India are witnessing growing demand for passenger and commercial vehicles equipped with advanced suspension systems. Simultaneously, developed regions like North America and Europe continue to offer opportunities through the rising consumer preference for premium vehicles and the adoption of adaptive suspension technologies. As automakers increasingly prioritize safety, comfort, and efficiency, the demand for innovative suspension control arms is expected to grow, enabling manufacturers to expand their product portfolios and capture new market segments.
Market Segmentation Analysis:
By Type, the market includes upper control arms and lower control arms. Lower control arms dominate the segment, as they are integral to vehicle suspension systems, providing stability and precise steering control. Upper control arms also hold a significant share, particularly in off-road and high-performance vehicles, where enhanced suspension capabilities are essential for improved handling and durability.
By Technology, the market is divided into traditional control arms and electronically controlled suspension systems. Traditional control arms remain widely used in mid-range and economy vehicles due to their cost-effectiveness and reliability. However, electronically controlled suspension systems are gaining traction, particularly in premium and electric vehicles, as they offer adaptive capabilities to optimize ride comfort and stability under varying driving conditions.
By End User, the market caters to passenger vehicles and commercial vehicles. Passenger vehicles represent the largest segment, driven by increasing demand for advanced suspension systems in compact, mid-range, and luxury cars. Commercial vehicles, including trucks and buses, are also adopting advanced suspension control arms to enhance load handling, durability, and safety.
Segmentations:
By Type
- Upper Arms
- Lower Arms
By Application
- Passenger Cars
- Commercial Cars
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
Asia-Pacific
Asia-Pacific dominates the automotive suspension control arms market, accounting for approximately 40% of the global share in 2024. This leadership is driven by high vehicle production volumes in countries like China, Japan, and India. For instance, China, the largest automotive producer globally, contributes over 50% of the region’s share, supported by robust domestic demand for both passenger and commercial vehicles. In 2023 alone, China sold over 26 million passenger automobiles, reflecting a significant increase in consumer preference for personal mobility. Japan and South Korea also play pivotal roles with advanced manufacturing technologies; Japanese automakers like Toyota and Honda are renowned for their innovative approaches to vehicle design and technology. Meanwhile, India is emerging as a key market due to increasing disposable incomes and a growing middle class that demands vehicles with enhanced ride comfort.
North America
North America holds around 25% of the market share, driven by robust consumer demand for premium vehicles and advancements in suspension technology. The United States leads this region, accounting for the majority of the share with high adoption rates of lightweight and electronically controlled suspension systems in luxury and electric vehicles. For instance, recent data shows that nearly 40% of new vehicle sales in the U.S. are attributed to SUVs and trucks, which often feature advanced suspension systems to enhance ride quality. Canada also contributes significantly to this market, particularly in the commercial vehicle segment where advanced suspension control arms improve load management and durability. The focus on enhancing vehicle performance aligns with consumer preferences for safety and comfort, further propelling growth in this sector.
Europe
Europe captures approximately 22% of the market share, supported by the region’s strong focus on vehicle safety and fuel efficiency. Countries like Germany, the UK, and France are key contributors to this landscape. Germany leads due to its renowned automotive engineering capabilities; it produced around 2.4 million vehicles in 2023 alone. The European Union’s stringent regulations on emissions and safety standards further drive the adoption of advanced suspension technologies, including lightweight control arms. For instance, compliance with these regulations has led to a significant increase in investments by automakers into R&D for innovative suspension solutions that meet both performance and environmental standards.
Latin America and the Middle East & Africa
Latin America and the Middle East & Africa collectively hold around 13% of the market share. In Latin America, Brazil and Mexico are key players driven by increasing automotive production and rising consumer demand for vehicles with improved ride comfort and stability. For instance, Brazil is projected to sell approximately 2.4 million units in 2024, marking an 8% growth from previous years. Meanwhile, the Middle East & Africa region is witnessing steady growth led by countries like the UAE and South Africa. Investments in transportation infrastructure have spurred demand for robust suspension systems capable of handling diverse driving conditions. As these regions continue to develop economically, they present significant opportunities for manufacturers looking to expand their market presence through tailored products that cater to local needs.
Key Player Analysis:
- SPC Performance
- Mevotech
- Dorman Products
- Lemförder (ZF Friedrichshafen AG)
- TRW Automotive
- Delphi Technologies
- MOOG (Federal-Mogul Motorparts)
- ACDelco
- Raybestos
- Febi Bilstein
Competitive Analysis:
The Automotive Suspension Control Arms market is highly competitive, with established players and emerging manufacturers driving innovation to meet diverse automotive needs. Companies like ZF Friedrichshafen AG (Lemförder), TRW Automotive, and Delphi Technologies dominate the market with advanced product portfolios focused on lightweight, high-performance materials. For instance, ZF Friedrichshafen AG is recognized for its precision-engineered control arms widely used in premium vehicles, such as those from BMW and Audi. Meanwhile, MOOG (Federal-Mogul Motorparts) and Mevotech cater to aftermarket demands with durable, cost-effective solutions that appeal to a broad consumer base; MOOG’s rigorous testing standards ensure reliability and longevity. Additionally, emerging players are targeting niche markets like electric and autonomous vehicles, offering customized control arms that integrate seamlessly with advanced suspension technologies. Reports indicate that companies specializing in EV components have experienced growth rates exceeding 20% in recent years. The competitive landscape is further shaped by increasing R&D investments and strategic collaborations between manufacturers and automakers, such as partnerships between Delphi Technologies and major automotive brands, which drive advancements in materials and design to enhance vehicle performance and safety standards globally.
Recent Developments:
- In October 2024, Mevotech released 239 new part numbers, including 40 first-to-market solutions. This expansion enhances coverage for late-model vehicles, offering engineered solutions designed for durability and ease of installation.
- In 2024, SPC Performance introduced preassembled adjustable front upper control arms for circle track, road racing, and drag applications. These arms provide full adjustability, allowing precise alignment adjustments to enhance vehicle handling and performance.
- In March 2022, ZF Aftermarket expanded its TRW product lines by adding 54 SKUs, covering over 37 million additional vehicles. This extension includes OE-quality products for braking, steering, and suspension systems, reinforcing TRW's commitment to comprehensive vehicle coverage.
- In April 2022, Mevotech announced the release of 154 new engineered chassis and control arm solutions to the aftermarket, focusing on providing engineered solutions for professional technicians.
Market Concentration & Characteristics:
The Automotive Suspension Control Arms market exhibits a moderately fragmented structure, with established players and emerging companies competing to capture market share. Key players such as ZF Friedrichshafen AG (Lemförder), TRW Automotive, and Delphi Technologies maintain strong positions through advanced product portfolios and robust R&D investments. These companies focus on innovations in lightweight materials and adaptive suspension systems to meet evolving industry standards for efficiency and safety. The market is characterized by increasing demand for control arms that enhance vehicle stability, ride comfort, and durability, particularly in premium and electric vehicles. Meanwhile, aftermarket suppliers like Mevotech and MOOG (Federal-Mogul Motorparts) play a vital role in addressing the growing replacement market. Strategic partnerships between automakers and component manufacturers further drive advancements, ensuring high-quality, durable solutions for both original equipment and aftermarket applications.
Report Coverage:
The research report offers an in-depth analysis based on Type, Application, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The growing shift towards lightweight materials such as aluminum and composites will drive innovation in suspension control arms to improve vehicle efficiency.
- Increasing adoption of electric and hybrid vehicles will create demand for advanced suspension control arms tailored to these vehicle types.
- Enhanced integration of electronically controlled suspension systems in premium and mid-range vehicles will bolster market growth.
- Emerging markets in Asia-Pacific and Latin America will present significant growth opportunities due to rising vehicle production and expanding consumer bases.
- Rising consumer preference for vehicles with improved ride comfort and stability will fuel advancements in control arm design and technology.
- Stringent government regulations on safety and emissions will push automakers to adopt advanced suspension systems, including innovative control arms.
- Technological advancements in adaptive suspension systems will drive demand for precision-engineered control arms compatible with smart vehicle platforms.
- Increasing demand for off-road and high-performance vehicles will create niche opportunities for robust and durable suspension control arms.
- Aftermarket players will capitalize on the growing replacement market, focusing on cost-effective and durable control arm solutions for aging vehicles.
- Collaborations between automakers and component manufacturers will accelerate innovation, ensuring high-quality and performance-driven suspension control arms.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Automotive Suspension Control Arms Market?
What factors are driving the growth of the Automotive Suspension Control Arms Market?
What are some challenges faced by the Automotive Suspension Control Arms Market?
Who are the major players in the Automotive Suspension Control Arms Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Automotive Suspension Control Arms Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Automotive Suspension Control Arms Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 43,005 million → forecast year: USD 56,193.13 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Automotive Suspension Control Arms Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Automotive Suspension Control Arms Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Automotive Suspension Control Arms Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Automotive Suspension Control Arms Market Drivers
- 3.3 Automotive Suspension Control Arms Market Restraints & Challenges
- 3.4 Automotive Suspension Control Arms Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Automotive Suspension Control Arms Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Automotive Suspension Control Arms Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Automotive Suspension Control Arms category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Automotive Suspension Control Arms Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Automotive Suspension Control Arms Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Automotive Suspension Control Arms market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Automotive Suspension Control Arms Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Automotive Suspension Control Arms Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Automotive Suspension Control Arms Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Automotive Suspension Control Arms (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Automotive Suspension Control Arms Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Automotive Suspension Control Arms Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Automotive Suspension Control Arms Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Automotive Suspension Control Arms Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Automotive Suspension Control Arms Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Automotive Suspension Control Arms Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Automotive Suspension Control Arms Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Automotive Suspension Control Arms Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Automotive Suspension Control Arms Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
