
Market Overview
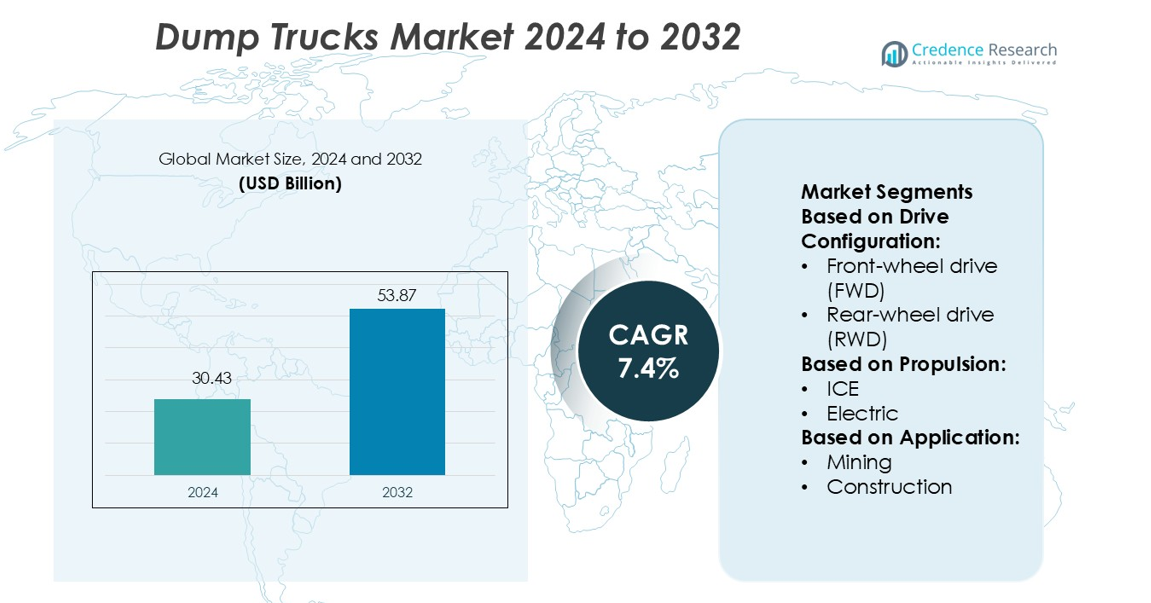
Dump Trucks Market size was valued USD 30.43 billion in 2024 and is anticipated to reach USD 53.87 billion by 2032, at a CAGR of 7.4% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Dump Trucks Market Size 2024 | USD 30.43 billion |
| Dump Trucks Market, CAGR | 7.4% |
| Dump Trucks Market Size 2032 | USD 53.87 billion |
The dump trucks market is shaped by major players such as Caterpillar Inc., Komatsu Ltd., Volvo Construction Equipment, Hitachi Construction Machinery Co., Ltd., Liebherr Group, Terex Corporation, Bell Equipment, Doosan Infracore, Deere & Company, and Sany Heavy Industry Co., Ltd. These companies focus on advanced engine technology, payload optimization, and autonomous operation systems to strengthen their global presence. They invest in R&D, expand product portfolios, and form strategic partnerships to enhance operational efficiency and fleet productivity. Asia Pacific leads the global market with a 42% share, driven by rapid infrastructure development, mining activities, and large-scale construction projects across China, India, and Southeast Asia.
Market Insights
- The Dump Trucks Market was valued at USD 30.43 billion in 2024 and is projected to reach USD 53.87 billion by 2032, growing at a CAGR of 7.4%.
- Rapid infrastructure development and increased mining activities are driving strong demand, supported by government investments in transportation and construction projects.
- Manufacturers such as Caterpillar Inc., Komatsu Ltd., and Volvo Construction Equipment are advancing autonomous driving, payload optimization, and fuel-efficient engines to gain market advantage.
- High initial investment costs and maintenance expenses remain key restraints, particularly in emerging economies with limited fleet modernization budgets.
- Asia Pacific dominates with a 42% market share, led by China and India, while the construction segment holds the largest share by application due to large-scale urbanization and industrial expansion.
Market Segmentation Analysis:
By Drive Configuration
Rear-wheel drive (RWD) dominates the dump trucks market with the largest share. RWD dump trucks offer better traction and weight distribution, which improves performance on rough terrains. Their ability to handle heavy loads makes them the preferred option for construction and mining operations. The strong torque delivery at the rear wheels supports reliable hauling over long distances. Demand for RWD models continues to rise as manufacturers enhance payload capacity and durability, driving widespread adoption in key industrial sectors.
- For instance, Hitachi’s rigid-frame RWD model EH4000AC‑3 features a nominal payload of 221 tonnes (221 000 kg) and a travel speed of 56 km/h. Its strong torque delivery at the rear wheels supports reliable hauling over long distances.
By Propulsion
Internal combustion engine (ICE) dump trucks lead the market with a dominant share. ICE vehicles provide strong torque output and extended operational range, making them ideal for heavy-duty applications. The well-established refueling infrastructure also supports continuous fleet operations without significant downtime. Fleet operators prefer ICE models due to their proven reliability and lower upfront cost compared to electric or hybrid variants. While electrification is growing, ICE remains the primary propulsion choice for large-scale mining and construction activities.
- For instance, Caterpillar’s rigid-frame haul truck model 797F is powered by the Cat C175-20 20-cylinder diesel engine rated at 4,000 hp (2,983 kW) under SAE J1995, with a net output of 3,793 hp (2,828 kW) under SAE J1349.
By Application
The construction segment holds the largest share in the dump trucks market. Dump trucks play a crucial role in transporting aggregates, sand, gravel, and debris across infrastructure projects. Rapid urbanization and rising investments in road and building construction drive strong demand. Their high load capacity and operational efficiency make them essential equipment on job sites. Manufacturers are introducing advanced features like automated controls and telematics to improve fleet performance, further reinforcing construction’s leadership in overall market share.
Key Growth Drivers
Rising Infrastructure and Construction Projects
Expanding infrastructure development is a major driver of the dump trucks market. Large-scale projects such as highways, bridges, and urban housing require efficient material transportation, boosting demand for high-capacity trucks. Governments are investing heavily in road expansion and smart city initiatives, increasing the need for reliable hauling equipment. Construction companies prefer dump trucks for their strong payload capacity and adaptability to rough terrain. The continuous rise in infrastructure spending is expected to sustain steady demand for both heavy-duty and medium-duty dump trucks across key markets.
- For instance, Parker lists hydraulic pumps for direct PTO mounting rated at 400 bar (≈ 5,800 psi) and variable-flow systems for implement control within construction-grade machines.
Growing Mining Activities and Resource Extraction
The global rise in mineral exploration and extraction significantly drives dump truck demand. Mining operations depend on high-performance trucks to move overburden, ore, and other materials efficiently. Leading mining nations are expanding production capacity, increasing fleet sizes to support output targets. Rigid and articulated dump trucks are favored for their load-bearing strength and off-road mobility. The integration of advanced engine technology also enhances fuel efficiency and uptime. This surge in mining investments strengthens the market position of dump trucks in heavy-duty applications.
- For instance, SANY’s electric-off-highway model SKT90E features a 422 kWh battery capacity, supports driving time of 9–10 hours on flat work roads, and can haul a load weight of 60 t.
Technological Advancements in Fleet Efficiency
Advancements in telematics, automation, and electric powertrains are boosting operational efficiency. Modern dump trucks feature GPS tracking, route optimization, and real-time diagnostics that reduce downtime and operating costs. Automated controls enhance driver safety and improve load handling accuracy in construction and mining sites. Electric and hybrid models are gaining interest as companies aim to reduce emissions and meet regulatory standards. These innovations support cost-effective fleet management and increase the appeal of technologically advanced dump trucks to large-scale operators.
Key Trends & Opportunities
Shift Toward Electrification and Sustainable Fleets
The dump truck industry is witnessing a shift toward electric and hybrid powertrains. Manufacturers are investing in battery technology to reduce emissions and fuel costs while maintaining performance. Governments are offering incentives for adopting cleaner vehicles, accelerating the transition. Electric dump trucks provide lower operating costs, reduced noise, and improved energy efficiency. Fleet operators are exploring green fleet strategies to align with environmental goals. This trend creates opportunities for companies offering advanced propulsion solutions and sustainable vehicle designs.
- For instance, Liebherr’s T 264 Battery Electric truck offers a payload class of 240 t and a gross vehicle weight (GVW) of 416 t, using its Litronic Plus AC drive system with IGBT technology.
Integration of Automation and Smart Features
Automation and smart control systems are becoming a key trend in dump truck operations. Features like collision avoidance, driver assistance, load monitoring, and predictive maintenance are improving productivity and safety. Telematics allows real-time performance monitoring and efficient route planning, reducing fuel consumption. These technologies help operators minimize downtime and increase fleet utilization rates. As automation adoption grows, manufacturers offering integrated digital solutions are likely to capture significant market share.
- For instance, Scania’s Autonomous Mining Solutions include a 40-tonne autonomous heavy tipper now available for order. These trucks use GPS, lidar and sensor arrays for obstacle detection and route optimisation.
Expansion in Emerging Economies
Emerging markets in Asia, Africa, and Latin America present major opportunities for growth. These regions are investing heavily in mining, construction, and infrastructure development. Low-cost labor and abundant resources attract global companies to expand operations. The rising demand for affordable yet durable dump trucks in these areas offers manufacturers a strong revenue stream. Localization strategies and regional assembly units further boost competitiveness in these high-growth markets.
Key Challenges
High Initial and Maintenance Costs
The high purchase and maintenance costs of dump trucks pose a significant challenge. Heavy-duty models require substantial upfront investment, which can strain smaller contractors and fleet operators. Maintenance of engines, tires, and hydraulic systems adds recurring expenses, increasing total cost of ownership. These costs limit the ability of smaller firms to scale their fleets quickly. Addressing this challenge requires cost-efficient leasing models and improved component durability to reduce lifecycle expenses.
Environmental and Regulatory Pressures
Strict emissions regulations are creating operational challenges for traditional diesel-powered dump trucks. Many countries are enforcing carbon reduction targets, pushing companies to upgrade or replace older fleets. This transition involves high capital investment and compliance costs. Additionally, the lack of charging infrastructure for electric dump trucks in developing regions slows adoption. Manufacturers and operators must balance regulatory compliance with cost-effectiveness, which may impact market growth in the short term.
Regional Analysis
North America
North America holds a significant share of the dump trucks market, accounting for 28% of the global share. Strong infrastructure modernization programs and extensive mining operations drive regional growth. The U.S. and Canada lead due to large-scale construction and energy projects. High adoption of advanced telematics and automation in fleets enhances operational efficiency. Stringent emission standards are accelerating the shift toward hybrid and electric dump trucks. Established manufacturers and rental fleet operators strengthen market competition, while steady investments in urban development projects further boost demand for heavy-duty and articulated dump trucks across the region.
Europe
Europe accounts for 22% of the dump trucks market, driven by investments in sustainable infrastructure and strict environmental regulations. Countries like Germany, France, and the U.K. are leading in electrification efforts, promoting electric and hybrid dump trucks. Smart construction technologies and green fleet initiatives support regional market growth. The demand for mid-capacity and articulated models is rising in urban redevelopment and renewable energy projects. Fleet modernization programs and telematics integration are improving productivity. Government incentives and zero-emission goals continue to shape the competitive landscape, encouraging manufacturers to focus on energy-efficient and low-emission solutions.
Asia Pacific
Asia Pacific dominates the global dump trucks market with a 36% share. Rapid urbanization, large-scale infrastructure expansion, and mining projects in China, India, and Southeast Asia fuel strong demand. Government-led investments in highways, bridges, and housing increase the deployment of heavy-duty trucks. Mining activities in Australia and Indonesia also drive fleet expansion. Manufacturers are expanding local production to meet rising demand for cost-effective models. The region is witnessing gradual adoption of telematics and electric vehicles, supported by industrialization and favorable trade policies. This combination of infrastructure growth and fleet modernization positions Asia Pacific as the leading regional market.
Latin America
Latin America represents 8% of the global dump trucks market share. Mining and construction sectors in Brazil, Chile, and Peru play a central role in driving demand. Expansion of copper, iron ore, and lithium projects boosts the use of rigid and articulated dump trucks. Infrastructure investment programs aimed at improving transportation networks further support market growth. However, high import costs and limited local manufacturing capacity pose operational challenges. Despite these factors, growing foreign investments and fleet modernization initiatives are creating opportunities for global manufacturers to strengthen their presence in the region.
Middle East & Africa
The Middle East & Africa region holds 6% of the dump trucks market share. Infrastructure development in the Gulf Cooperation Council (GCC) countries and mining activities in South Africa drive regional demand. Mega projects, such as smart cities and transportation corridors, increase the use of heavy-duty trucks. Governments are investing in resource extraction and construction sectors, creating steady demand. However, reliance on diesel fleets and slower electrification adoption remain challenges. Manufacturers are focusing on durable and high-capacity models suited for harsh environments, ensuring steady growth opportunities across both the construction and mining industries in the region.
Market Segmentations:
By Drive Configuration:
- Front-wheel drive (FWD)
- Rear-wheel drive (RWD)
By Propulsion:
- ICE
- Electric
By Application:
- Mining
- Construction
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The dump trucks market is shaped by key players such as Hitachi, Caterpillar, Parker Hannifin, SANY, Liebherr, Scania, Komatsu, BelAZ, Cummins, and Volvo. The dump trucks market is defined by rapid innovation, technology integration, and strategic expansion. Manufacturers focus on improving payload capacity, fuel efficiency, and operational safety to meet diverse industry demands. Companies are actively investing in electrification and automation to align with sustainability goals and regulatory requirements. Strategic collaborations and acquisitions enhance their ability to offer advanced solutions and strengthen service networks. Regional manufacturing facilities are also expanding to reduce production costs and improve delivery timelines. With growing demand from construction and mining, competition is intensifying, pushing companies to innovate and differentiate through performance, durability, and smart fleet solutions.
Key Player Analysis
- Hitachi
- Caterpillar
- Parker Hannifin
- SANY
- Liebherr
- Scania
- Komatsu
- BelAZ
- Cummins
- Volvo
Recent Developments
- In April 2025, SANY India launched India’s first locally manufactured hybrid mining dump truck, SKT130S, a 100-ton hybrid truck, at its Chakan, Pune facility in Maharashtra.
- In July 2024, Vale, a prominent mining company, special technologies developer Komatsu, and Cummins Inc., a key participant in the power solutions market, announced a collaboration aimed at developing large trucks with payload capacity of 230 to 290 tons, empowered by ethanol and diesel. The Dual Fuel project emphasizes Vale’s strategy to reduce scope 1 and 2 carbon emissions significantly.
- In June 2024, XCMG Machinery, one of the top companies in the construction machinery market, introduced a new hydrogen fuel cell dump truck, EHSL552F. The new truck has a high-power battery system and a 120kW hydrogen fuel cell. This addition to its portfolio is expected to assist mining industry users in significantly reducing daily carbon emissions.
- In January 2024, Hitachi Construction Machinery and the Traction Division of ABB made major progress on their collaboration for a fully electric dump truck designed for heavy-duty mining applications. The first prototype of the truck completed initial in-factory testing and was shipped to the Kansanshi copper-gold mine in Zambia for final testing and demonstration planned for mid-2024
Report Coverage
The research report offers an in-depth analysis based on Drive Configuration, Propulsion, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for dump trucks will grow with large-scale infrastructure and mining projects.
- Electric and hybrid dump trucks will gain more market adoption.
- Telematics and automation will enhance operational efficiency and fleet control.
- Manufacturers will focus on improving payload capacity and fuel efficiency.
- Regulatory pressure will drive faster shifts toward low-emission technologies.
- Emerging economies will become major growth hubs for new fleet deployments.
- Smart connectivity features will become standard in high-performance dump trucks.
- Rental and leasing services will expand to meet flexible demand needs.
- Collaboration between OEMs and tech firms will accelerate innovation.
- Upgraded safety systems and real-time monitoring will strengthen fleet reliability.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Dump Trucks Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Dump Trucks Market projected to grow between 2025 and 2032?
Which Dump Trucks Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Dump Trucks Market?
Who are the leading companies in the Dump Trucks Market?
Which region commanded the largest share of the Dump Trucks Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 30.43 billion → 2032: USD 53.87 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Dump Trucks Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Dump Trucks Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Dump Trucks Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Dump Trucks Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Dump Trucks Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Dump Trucks Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Dump Trucks Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Dump Trucks Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 30.43 billion → 2032: USD 53.87 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Dump Trucks Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Dump Trucks Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Dump Trucks Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Dump Trucks Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

