
Market Overview
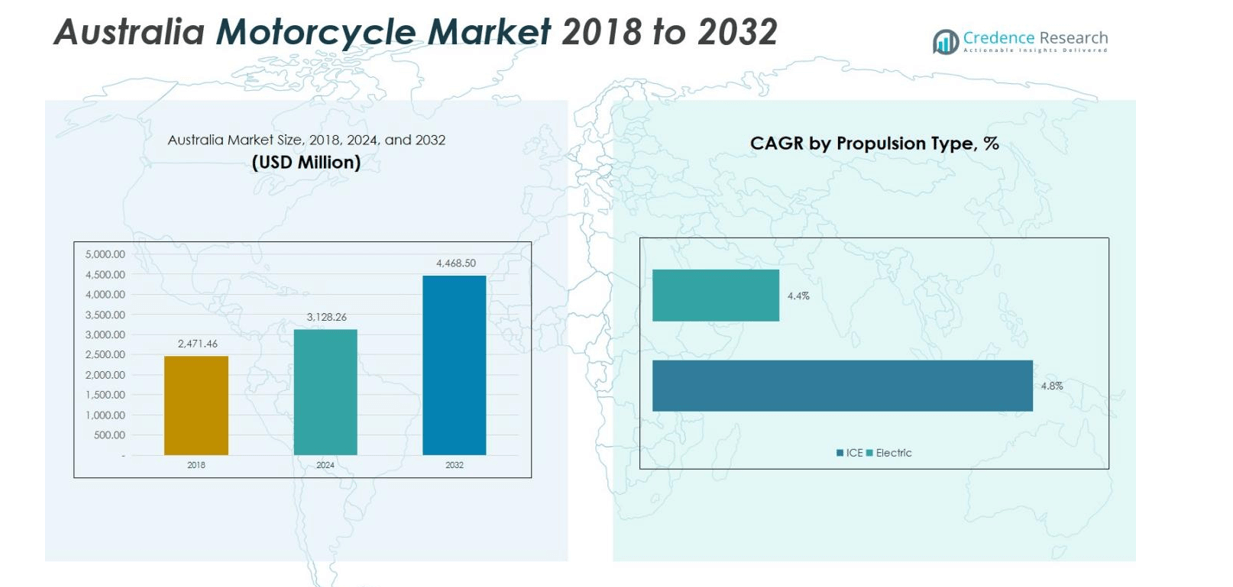
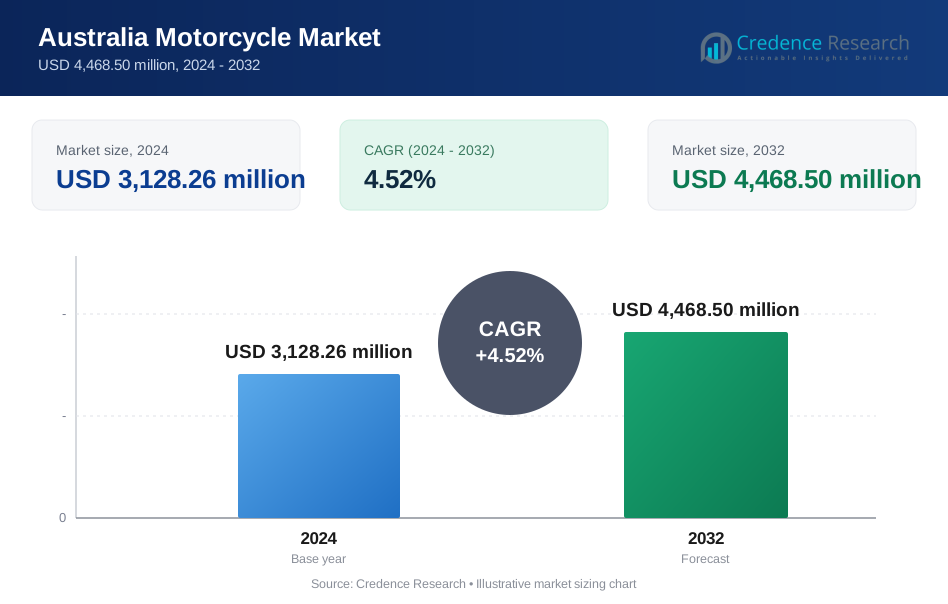
The Australia Motorcycle Market size was valued at USD 2,471.46 million in 2018, increasing to USD 3,128.26 million in 2024, and is anticipated to reach USD 4,468.50 million by 2032, growing at a CAGR of 4.52% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Australia Motorcycle Market Size 2024 | USD 3,128.26 million |
| Australia Motorcycle Market, CAGR | 4.52% |
| Australia Motorcycle Market Size 2032 | USD 4,468.50 million |
The Australia Motorcycle Market is characterized by strong competition among key players such as Bennett & Barkell, TVS Motor Company Ltd., Bajaj Auto Ltd., Thumpstar, Suzuki Motor Corporation, Zero Motorcycles Inc., BMW AG, Harley-Davidson Inc., Piaggio Group, and Kawasaki Motors Corp. These companies focus on product innovation, electric mobility, and expanding dealership networks to strengthen their market presence. While premium brands like Harley-Davidson and BMW dominate the high-end segment, Bajaj, Suzuki, and TVS lead in affordable commuter categories. New South Wales emerges as the leading region, capturing 28% of the national market share, supported by strong commuter demand, advanced infrastructure, and a growing culture of recreational motorcycling.
Market Insights
- The Australia Motorcycle Market was valued at USD 3,128.26 million in 2024 and is projected to reach USD 4,468.50 million by 2032, growing at a CAGR of 4.52% during the forecast period.
- Market growth is driven by rising urban mobility needs, increasing adoption of commuter and leisure motorcycles, and expanding financing and after-sales service networks across the country.
- Emerging trends include the growing popularity of electric and connected motorcycles, along with a surge in demand for adventure and touring models among recreational riders.
- The competitive landscape features major players such as Bennett & Barkell, TVS Motor Company, Bajaj Auto, Suzuki, BMW, and Harley-Davidson, focusing on innovation, affordability, and premium product development.
- Regionally, New South Wales leads with a 28% share, while standard motorcycles dominate the market with a 40% segment share, supported by affordability and versatility for both commuting and leisure use.
Market Segmentation Analysis:
By Motorcycle Type
The standard motorcycle segment leads the Australian market with a 40% share, driven by its versatile design, affordability, and suitability for daily commuting and weekend leisure rides. Sports motorcycles follow with a 20% share, supported by growing enthusiasm for high-performance models among younger riders. Cruisers and touring bikes collectively account for around 25%, catering to comfort and long-distance travel preferences, while the remaining 15% is held by niche types such as adventure and off-road bikes. Rising lifestyle motorcycling trends and urban mobility needs continue to fuel diversity across type segments.
- For instance, Honda’s CB500X remains a popular choice among commuters for its fuel efficiency and balanced engine performance, supporting daily urban travel needs.
By Propulsion Type
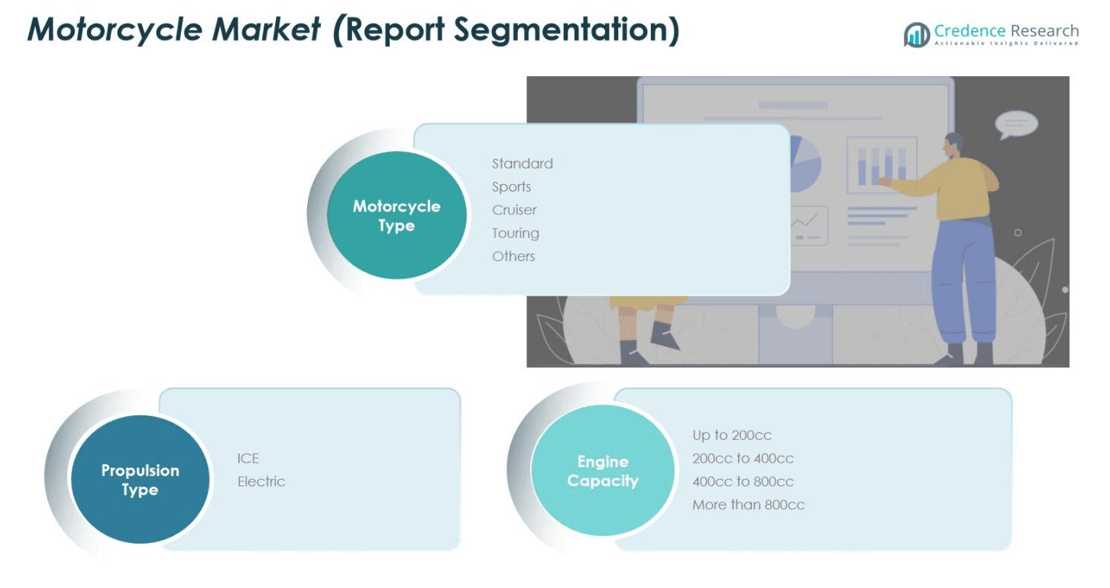
The Internal Combustion Engine (ICE) segment dominates with over 90% market share, supported by well-established fuel infrastructure, brand familiarity, and affordability. Despite this dominance, electric motorcycles are rapidly emerging, holding nearly 10% share and recording the fastest growth rate. The shift is propelled by sustainability goals, rising fuel prices, and government incentives promoting electric mobility. Technological improvements in battery capacity and charging networks are enhancing the feasibility of electric two-wheelers for urban commuting, positioning them as a strong growth driver for the coming decade.
- For instance, Ather Energy unveiled its latest Gen 3 electric scooter, which offers a higher-range lithium-ion battery and rapid charging times, making it popular for city commuting and reflecting ongoing battery technology advancements.
By Engine Capacity
Motorcycles with up to 200cc engines hold the largest share at 45%, owing to their affordability, fuel efficiency, and suitability for city travel. The 200cc–400cc range follows with 25%, balancing power and cost for mid-level riders. Models in the 400cc–800cc category account for about 20%, appealing to experienced users seeking greater performance, while above 800cc motorcycles capture 10%, reflecting demand for premium touring and cruiser bikes. This segmentation highlights Australia’s broad rider base—from cost-conscious commuters to performance enthusiasts—driving steady demand across all engine classes.
Key Growth Drivers
Rising Demand for Commuter and Leisure Motorcycles
Australia’s growing urban population and increasing preference for cost-effective commuting solutions are driving motorcycle adoption. Standard and commuter bikes are particularly favored for their fuel efficiency, ease of parking, and lower ownership costs compared to cars. Additionally, leisure motorcycling for touring and recreational use has gained popularity among middle-aged riders, supported by scenic routes and motorcycle clubs. This dual-purpose demand from daily commuting to lifestyle riding continues to expand the overall motorcycle market across both urban and regional Australia.
- For instance, Honda also introduced its CB125F, specifically targeting urban commuters with a focus on low fuel consumption and ease of maneuvering in city environments.
Technological Advancements and Electric Transition
Continuous innovation in motorcycle design, safety systems, and electric mobility is accelerating market growth. Manufacturers are integrating smart features such as ABS, traction control, and connectivity for enhanced rider safety and convenience. The growing introduction of electric motorcycles with improved battery range, lower maintenance needs, and government-backed incentives is further reshaping consumer preferences. These advancements are encouraging adoption across both traditional and new rider segments, positioning the Australian motorcycle market on a technologically progressive trajectory.
- For instance, Triumph Motorcycles confirmed a record schedule to launch 29 new and updated bikes, including electric and cross-country models, with global unveil events and new reservation technology now rolling out in Australia in late 2025.
Expansion of Motorcycle Financing and After-Sales Networks
Easier access to financing, leasing options, and insurance services has boosted motorcycle affordability in Australia. Financial institutions and manufacturers are offering flexible repayment plans, attracting young and first-time buyers. Simultaneously, the expansion of after-sales service networks, availability of spare parts, and brand-backed maintenance programs are enhancing consumer confidence. This improved service ecosystem not only increases customer retention but also strengthens brand loyalty, contributing significantly to sustained market expansion.
Key Trends & Opportunities
Growing Popularity of Adventure and Touring Motorcycles
Adventure and touring motorcycles are witnessing rapid uptake in Australia, driven by consumer interest in long-distance travel and off-road exploration. Brands are launching models tailored to the country’s diverse terrain, combining durability with advanced navigation and comfort features. The trend reflects a lifestyle shift, with riders seeking outdoor adventure experiences and domestic travel alternatives. This niche yet fast-growing category presents strong opportunities for premium manufacturers and accessory providers catering to touring enthusiasts.
- For instance, BMW Motorrad rolled out the R 1300 GS with adaptive cruise control and connectivity features to meet the increasing demand for technologically advanced touring bikes among Australian riders.
Emergence of Connected and Smart Motorcycles
The adoption of connected motorcycles equipped with IoT-based systems is transforming rider experience and safety standards. Features like GPS tracking, smartphone integration, and predictive maintenance alerts are gaining traction among tech-savvy consumers. Manufacturers are leveraging these technologies to offer real-time data, performance insights, and security functions. The shift toward digital integration presents new revenue streams for software developers, telematics providers, and OEMs, opening lucrative opportunities within Australia’s evolving mobility ecosystem.
- For instance, RGNT Electric Motorcycles a Swedish company partnered with Telenor IoT to integrate real-time GPS tracking, software updates, and security features into their connected electric motorcycles.
Key Challenges
High Ownership Costs and Maintenance Expenses
Despite rising demand, high upfront purchase prices and maintenance costs remain major deterrents for many potential buyers. Premium motorcycle models, particularly those above 800cc, require specialized servicing and costly spare parts, which elevate long-term ownership expenses. Additionally, rising fuel prices and insurance premiums further constrain affordability. These financial barriers limit broader market penetration, especially among younger consumers and entry-level riders seeking economical transport solutions.
Infrastructure Limitations and Safety Concerns
Insufficient dedicated motorcycle lanes, limited charging infrastructure for electric models, and higher accident risks hinder market expansion. Safety remains a key issue, as Australia’s vast road network often exposes riders to unpredictable weather and road conditions. The lack of robust infrastructure and public awareness about motorcycle safety discourages adoption in some regions. Addressing these concerns through government initiatives, improved road design, and rider training programs is critical to ensuring sustainable market growth.
Regional Analysis
New South Wales
New South Wales holds the largest share of the Australia Motorcycle Market, accounting for 28% of total revenue. The region’s strong urban infrastructure, high commuter density, and thriving leisure motorcycling culture support sustained demand. Sydney and its surrounding metropolitan areas lead in registrations of standard and sports motorcycles, driven by daily commuting needs and growing recreational use. The presence of established dealerships, favorable road networks, and government emphasis on sustainable mobility further reinforce market growth across both internal combustion and emerging electric motorcycle segments.
Victoria
Victoria represents around 24% of the national motorcycle market, fueled by high urbanization, supportive riding infrastructure, and active participation in motorcycling events. Melbourne’s increasing commuter congestion has pushed consumers toward motorcycles as practical urban transport solutions. Demand for touring and adventure models is also rising due to scenic regional routes and weekend leisure rides. Ongoing investments in road safety, rider education, and the availability of financing options enhance accessibility. The region’s balanced mix of commuter and premium motorcycles positions Victoria as a major growth hub within Australia’s two-wheeler landscape.
Queensland
Queensland accounts for 20% of the motorcycle market, supported by its vast road network and strong recreational riding culture. The region’s warm climate and open-road terrain encourage higher ownership of cruisers, touring, and off-road models. Major urban centers like Brisbane and the Gold Coast are witnessing a steady shift toward electric motorcycles as part of sustainable transport initiatives. Increasing tourism, rural connectivity needs, and the popularity of motorcycle events further strengthen Queensland’s position as a significant contributor to market expansion across various motorcycle categories.
Western Australia
Western Australia contributes around 15% of the national motorcycle market, characterized by high demand for touring and adventure motorcycles suited for long-distance travel. The state’s expansive geography and mining-driven economy generate strong demand for durable and high-performance models. Perth remains the key urban hub for standard and commuter motorcycles, while rural areas favor heavy-duty bikes for longer routes. The region’s emerging adoption of electric motorcycles, supported by renewable energy policies, indicates growth potential despite challenges from limited charging infrastructure and service availability across remote areas.
South Australia and Others
South Australia, along with Tasmania and the Northern Territory, collectively represents 13% of the Australia Motorcycle Market. These regions demonstrate moderate but consistent growth, driven by increasing recreational use and gradual electrification efforts. Adelaide’s rising interest in sustainable mobility and rural connectivity needs across smaller states support steady demand. Though smaller in scale, these regions benefit from expanding dealership networks and tourism-driven motorcycle rentals. Continued improvements in infrastructure and regional road safety initiatives are expected to enhance motorcycle adoption, particularly among leisure riders and adventure enthusiasts.
Market Segmentations:
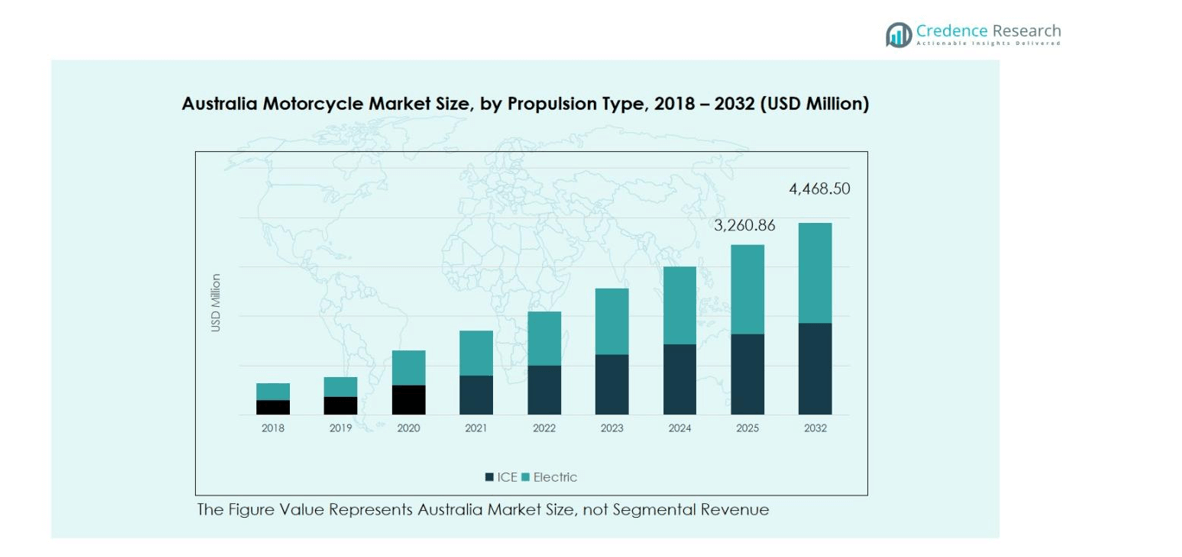
By Motorcycle Type
- Standard
- Sports
- Cruiser
- Touring
- Others
By Propulsion Type
- Internal Combustion Engine (ICE)
- Electric
By Engine Capacity
- Up to 200cc
- 200cc to 400cc
- 400cc to 800cc
- More than 800cc
By Region
- New South Wales
- Victoria
- Queensland
- Western Australia
- South Australia
- Others
Competitive Landscape
The competitive landscape of the Australia Motorcycle Market features prominent players such as Bennett & Barkell, TVS Motor Company Ltd., Bajaj Auto Ltd., Thumpstar, Suzuki Motor Corporation, Zero Motorcycles Inc., BMW AG, Harley-Davidson Inc., Piaggio Group, and Kawasaki Motors Corp. These companies compete across diverse segments including standard, sports, cruiser, and electric motorcycles, focusing on innovation, brand loyalty, and customer experience. Market leaders emphasize technological integration, fuel efficiency, and performance upgrades to attract both commuter and leisure riders. Strategic initiatives such as dealership expansion, after-sales service enhancement, and financing support strengthen their regional presence. The growing adoption of electric and connected motorcycles has also encouraged partnerships and R&D investments among manufacturers. Premium brands like Harley-Davidson and BMW dominate the high-end segment, while Bajaj, Suzuki, and TVS continue to lead in affordable commuter categories, reflecting a balanced competitive environment driven by innovation, accessibility, and evolving consumer preferences.
Key Player Analysis
- Bennett & Barkell
- TVS Motor Company Ltd.
- Bajaj Auto Ltd.
- Thumpstar
- Suzuki Motor Corporation
- Zero Motorcycles Inc.
- Bayerische Motoren Werke (BMW) AG
- Harley-Davidson, Inc.
- Piaggio Group
- Kawasaki Motors Corp.
- Other Key Players
Recent Developments
- In May 2025, Royal Enfield expanded its footprint in Australia by opening its first Premier Store in Queensland, in collaboration with GRID Motorcycles, enhancing accessibility for its growing customer base in the country.
- In July 2025, MV Agusta announced the establishment of a wholly-owned subsidiary in Australia, headquartered in Sydney, to manage sales, marketing and customer support in Australia and New Zealand.
- In February 2025, Kawasaki secured naming-rights sponsorship of the 2025 Australian Supersport Championship, reinforcing its racing credentials and brand positioning in the Australian market.
- In September 2025, Savic Motorcycles began ramping production of its electric C-Series motorcycle and announced plans for global expansion from its Melbourne base, strengthening its presence in the Australian electric-motorcycle segment
Report Coverage
The research report offers an in-depth analysis based on Motorcycle Type, Propulsion Type, Engine Capacity and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is expected to witness steady growth driven by rising urban mobility needs and lifestyle-oriented riding culture.
- Electric motorcycles will gain momentum as technology improves and charging infrastructure expands nationwide.
- Standard motorcycles will continue to dominate due to their affordability and versatility for daily commuting.
- Adventure and touring models will see increasing adoption, supported by Australia’s expanding recreational riding community.
- Manufacturers will focus on introducing connected and smart features to enhance rider safety and convenience.
- Premium motorcycle demand will rise among experienced riders seeking performance and comfort upgrades.
- Government initiatives promoting sustainable transportation will accelerate the transition toward electric two-wheelers.
- Financing and leasing options will expand motorcycle accessibility for younger and first-time buyers.
- Dealership and service network expansion will strengthen brand presence across regional and rural areas.
- Strategic collaborations and product diversification will remain key to maintaining competitiveness in the evolving market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Australia Motorcycle Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Australia Motorcycle Market projected to grow between 2025 and 2032?
Which Australia Motorcycle Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Australia Motorcycle Market?
Who are the leading companies in the Australia Motorcycle Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Australia Motorcycle Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Australia Motorcycle Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3,128.26 million → 2032: USD 4,468.50 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Australia Motorcycle Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Australia Motorcycle Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Australia Motorcycle Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Australia Motorcycle Market Drivers
- 3.3 Australia Motorcycle Market Restraints & Challenges
- 3.4 Australia Motorcycle Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Australia Motorcycle Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Australia Motorcycle Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Australia Motorcycle category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Australia Motorcycle Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Australia Motorcycle Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Australia Motorcycle market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Australia Motorcycle Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Australia Motorcycle Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Australia Motorcycle Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Australia Motorcycle (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Australia Motorcycle Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Australia Motorcycle Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Australia Motorcycle Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Australia Motorcycle Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Australia Motorcycle Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Australia Motorcycle Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Australia Motorcycle Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Australia Motorcycle Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Australia Motorcycle Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
