
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Automotive Wire and Cable Materials Market Size 2024 | USD 2,150 million |
| Automotive Wire and Cable Materials Market, CAGR | 4.78% |
| Automotive Wire and Cable Materials Market Size 2032 | USD 3,124 million |
Market Overview
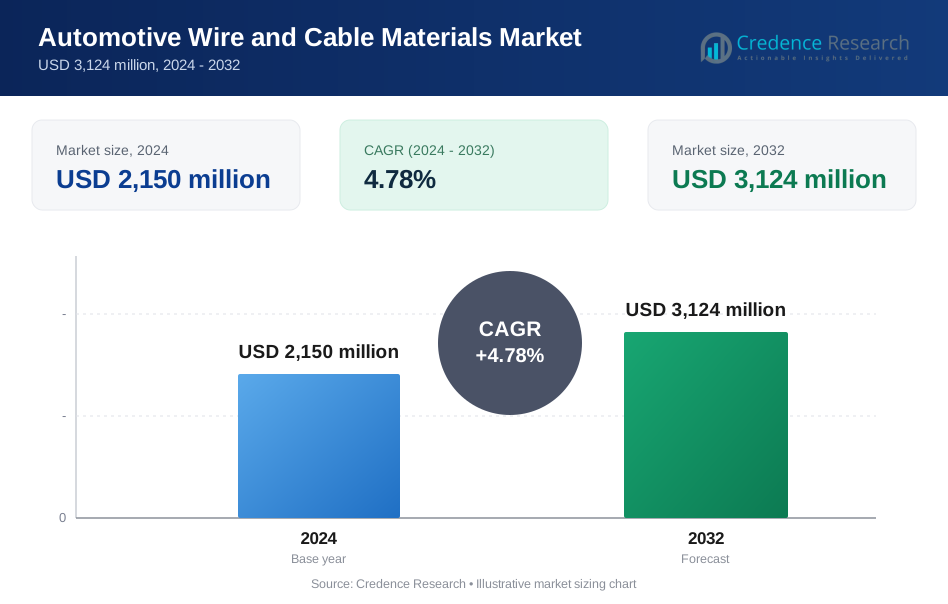
Automotive Wire and Cable Materials Market size was valued at USD 2,150 million in 2024 and is anticipated to reach USD 3,124 million by 2032, at a CAGR of 4.78% during the forecast period.
The Automotive Wire and Cable Materials Market is driven by the rising demand for advanced safety features, electrification, and connectivity in modern vehicles. The growth of electric vehicles (EVs) and hybrid vehicles is significantly increasing the need for high-performance, heat-resistant, and lightweight wire and cable materials that can support efficient power transmission and enhanced signal integrity. Additionally, stringent automotive regulations regarding emission standards and vehicle safety are compelling manufacturers to adopt innovative materials that offer durability, flexibility, and compliance with global standards. Trends such as the integration of smart electronics, autonomous driving technologies, and digital dashboards are further accelerating the demand for specialized wiring solutions. The market also benefits from ongoing advancements in material science, including the development of halogen-free, flame-retardant, and eco-friendly compounds, aligning with the industry’s focus on sustainability and environmental responsibility. Collectively, these factors are shaping a dynamic and competitive landscape for automotive wire and cable materials.
The geographical analysis of the Automotive Wire and Cable Materials Market reveals strong growth in Asia Pacific, led by countries such as China, Japan, and India, where robust automotive manufacturing and rising adoption of electric vehicles drive substantial demand for advanced materials. Europe demonstrates significant progress in the adoption of innovative, environmentally friendly wire and cable solutions, with a focus on meeting strict emission and safety standards. North America shows consistent advancements through technological innovation and the integration of sophisticated automotive electronics. Key players shaping the global landscape include Yazaki Corporation, renowned for its comprehensive automotive wiring systems; Leoni AG, which specializes in high-quality cable solutions for both traditional and electric vehicles; and Sumitomo Electric Industries, Ltd, known for its leadership in developing heat-resistant and durable wiring materials. These companies maintain a strong presence across major regions, continually investing in research and development to support evolving automotive requirements.
Market Insights
- The Automotive Wire and Cable Materials Market was valued at USD 2,150 million in 2024 and is projected to reach USD 3,124 million by 2032, with a CAGR of 4.78%.
- Expanding vehicle electrification, integration of advanced safety features, and the rising adoption of smart connectivity systems continue to drive steady demand for high-performance wire and cable materials.
- Trends include growing use of high-voltage, heat-resistant compounds and the emergence of eco-friendly, halogen-free, and recyclable materials to meet regulatory and consumer sustainability expectations.
- The market remains highly competitive, with leading players such as Yazaki Corporation, Leoni AG, and Sumitomo Electric Industries, Ltd focusing on research, product innovation, and strategic partnerships to strengthen their global presence.
- Stringent safety and emission regulations, volatility in raw material prices, and compliance requirements pose ongoing restraints, challenging manufacturers to balance cost, performance, and regulatory demands.
- Asia Pacific leads the market, benefiting from robust automotive production and electric vehicle adoption in China, Japan, and India, while Europe and North America also show strong innovation and integration of new technologies.
- The market is evolving rapidly, with suppliers prioritizing lightweight, durable, and flexible materials that support next-generation vehicle designs and meet global quality standards.
Market Drivers
Expanding Vehicle Electrification and Integration of Advanced Technologies Propel Material Demand
Automotive manufacturers worldwide are investing in electrification and sophisticated onboard systems, driving higher consumption of innovative wire and cable materials. The rise of electric and hybrid vehicles necessitates robust materials that support efficient energy transmission and advanced connectivity. Modern vehicles increasingly incorporate sensors, control units, and infotainment systems, all of which rely on reliable wiring solutions. Enhanced safety features and the proliferation of autonomous driving technologies further accelerate the need for durable, high-performance cable materials. The Automotive Wire and Cable Materials Market benefits from these developments by supplying products that meet elevated performance standards. It responds to industry requirements for greater conductivity, heat resistance, and reduced weight, supporting the evolution of next-generation vehicles.
- For instance, 70% of modern vehicles are now equipped with ADAS (Advanced Driver Assistance Systems), boosting the demand for high-speed data transmission cables.
Stringent Safety and Emission Regulations Influence Material Innovation
Global regulatory authorities enforce strict emission and safety standards, prompting automakers to seek wire and cable materials that comply with evolving rules. These regulations demand improved fire resistance, chemical stability, and reduced toxicity in automotive components. Manufacturers prioritize the adoption of halogen-free, flame-retardant materials that safeguard passengers and enhance vehicle safety profiles. It catalyzes ongoing research and development efforts, resulting in innovative compounds with superior protective properties. The Automotive Wire and Cable Materials Market remains responsive to these regulatory changes by introducing solutions that facilitate compliance without compromising on quality or durability. Strong focus on safety and environmental protection drives continuous product advancements.
- For instance, the rising popularity of electric vehicles in East Asia is driving demand for specialized high-voltage wires and cables in electric powertrains.
Growth of Connected and Autonomous Vehicles Spurs Demand for Specialized Wiring
The rapid adoption of connected vehicles and autonomous driving systems requires intricate wiring architectures capable of supporting complex data transmission and control functions. Reliable connectivity and uninterrupted signal transmission are crucial for navigation, communication, and safety applications in intelligent vehicles. The Automotive Wire and Cable Materials Market meets these challenges by offering materials engineered for electromagnetic compatibility, minimal signal loss, and mechanical strength. It supports the deployment of vehicle-to-everything (V2X) communications and advanced driver-assistance systems (ADAS), both of which depend on high-quality wiring infrastructure. Market players innovate to provide specialized materials tailored for digital vehicle platforms.
Industry Shift Toward Lightweight, Eco-Friendly, and Cost-Efficient Materials Shapes Product Development
Automotive manufacturers seek materials that contribute to overall vehicle weight reduction and energy efficiency, without sacrificing performance or reliability. Sustainable practices influence purchasing decisions, with an increasing emphasis on recyclable and environmentally responsible compounds. The Automotive Wire and Cable Materials Market responds by introducing lightweight polymers and eco-friendly alternatives that align with global sustainability goals. It addresses cost pressures by streamlining manufacturing processes and offering competitively priced solutions. This approach supports industry efforts to balance cost, quality, and environmental impact while maintaining the highest standards of performance and compliance.
Market Trends
Emergence of Smart Materials and Enhanced Functional Capabilities
Smart materials capable of self-healing, real-time monitoring, and adaptive insulation are gaining traction in the automotive sector. Demand for intelligent wire and cable materials reflects the push for advanced diagnostics and predictive maintenance in next-generation vehicles. The Automotive Wire and Cable Materials Market explores novel compounds embedded with sensors and conductive fillers, enabling enhanced performance monitoring and safety. It plays a crucial role in the integration of connected car technologies, facilitating seamless data exchange and fault detection. Manufacturers leverage these innovations to deliver safer and more reliable vehicles. Market adoption of smart materials continues to grow alongside digitalization trends.
- For instance, the automotive wire and cable material market is predicted to expand around 1.9X through 2033 due to growing demand for vehicles in both developed and developing countries.
Rising Adoption of High-Voltage and Heat-Resistant Materials for Electric Mobility
The growing focus on electric mobility encourages the use of high-voltage and heat-resistant wire and cable materials across automotive platforms. Electric vehicles and hybrids require components that withstand elevated temperatures and voltage demands without compromising safety or efficiency. The Automotive Wire and Cable Materials Market aligns with this trend by delivering advanced polymer and elastomer compounds, supporting long-term performance in demanding environments. It adapts to evolving automotive architectures by offering insulation and jacketing materials that reduce thermal degradation and electrical losses. Increased consumer acceptance of electric vehicles drives ongoing innovation in this space. Market participants invest in research to further improve temperature resistance and lifespan.
- For instance, electric vehicles require 60% more wiring than conventional vehicles, increasing demand for specialized automotive wires.
Shift Toward Miniaturization and Integration of Compact Wiring Solutions
Automotive manufacturers are pursuing compact and lightweight vehicle designs, necessitating the miniaturization of electrical components. Wiring systems must occupy less space without sacrificing capacity or reliability, driving interest in slim, flexible materials and tightly bundled cables. The Automotive Wire and Cable Materials Market responds with products that facilitate denser wiring layouts, supporting the integration of multiple electronic functions in limited spaces. It provides materials engineered for flexibility and mechanical resilience, enabling innovative vehicle interiors and advanced safety features. This trend supports broader industry objectives related to space efficiency and improved vehicle ergonomics. Suppliers continue to refine materials to maximize performance in confined environments.
Emphasis on Sustainability and the Development of Eco-Friendly Compounds
The automotive industry’s commitment to sustainability shapes the development of recyclable and environmentally friendly wire and cable materials. Market participants prioritize halogen-free, low-emission, and recyclable polymers that reduce the ecological footprint of vehicle manufacturing. The Automotive Wire and Cable Materials Market advances sustainability by introducing materials that align with global regulations and consumer preferences for green products. It encourages the use of renewable feedstocks and supports closed-loop recycling systems within the supply chain. Demand for sustainable solutions fosters innovation and collaboration across the industry. This trend ensures that new materials meet performance criteria while supporting environmental stewardship.
Market Challenges Analysis
Complex Regulatory Compliance and Escalating Material Performance Standards
Automotive manufacturers face increasing regulatory scrutiny concerning safety, environmental protection, and chemical use, which elevates the complexity of compliance for wire and cable materials. The Automotive Wire and Cable Materials Market must continually adjust to evolving international standards, including restrictions on hazardous substances and requirements for fire resistance. Meeting these rigorous regulations often requires substantial investment in research, testing, and certification, which can slow product development cycles and increase operational costs. It faces the challenge of designing materials that simultaneously deliver safety, durability, and environmental compatibility. The pace of regulatory change can outstrip industry adaptation, creating uncertainty in long-term material planning. Companies must maintain flexible strategies to keep products compliant in diverse global markets.
- For instance, East Asia leads the automotive wire and cable materials market due to stringent emission norms and growing demand for electric vehicles.
Volatility in Raw Material Prices and Pressure to Maintain Cost Efficiency
Price fluctuations for key raw materials, such as polymers, metals, and specialty additives, present persistent challenges for the Automotive Wire and Cable Materials Market. Market participants must balance the need for advanced performance with the imperative to control production costs and sustain profitability. Sudden increases in raw material costs can erode margins and complicate supply agreements, particularly for manufacturers operating on fixed contracts. It must also respond to competitive pricing pressures, as automakers seek affordable solutions without compromising quality. Supply chain disruptions and geopolitical factors can exacerbate these issues, leading to shortages or delays in material procurement. Effective risk management and supplier diversification are critical for mitigating the impact of these market dynamics.
Market Opportunities
Expansion of Electric and Autonomous Vehicle Segments Creates New Material Demands
The ongoing shift toward electric and autonomous vehicles presents significant opportunities for suppliers of advanced wire and cable materials. The Automotive Wire and Cable Materials Market can capitalize on the increasing requirements for high-voltage, heat-resistant, and lightweight solutions tailored for battery systems, power distribution, and sophisticated sensor arrays. It stands to benefit from the rapid deployment of connected and self-driving technologies that require robust wiring to support data transmission and safety-critical operations. Growth in vehicle electrification directly correlates to higher volumes and greater technical specifications for wire and cable materials. Companies that invest in specialized product lines designed for emerging vehicle architectures can secure a competitive edge. Early adoption and customization offer strong prospects for revenue growth and long-term partnerships with leading automakers.
Rising Demand for Sustainable and Smart Materials Drives Innovation Opportunities
Sustainability initiatives and evolving consumer preferences for eco-friendly vehicles generate substantial opportunities for innovation within the Automotive Wire and Cable Materials Market. Market players can introduce new formulations featuring recyclable, halogen-free, and bio-based materials that align with global environmental standards. It can expand its presence by developing smart wires capable of diagnostics, self-healing, and real-time performance monitoring, supporting the next generation of connected vehicles. Strategic collaboration with automotive OEMs and technology developers enables the creation of bespoke solutions for advanced vehicle platforms. Growing regulatory and market emphasis on environmental responsibility further accelerates demand for green and intelligent materials, encouraging continuous product development and market differentiation.
Market Segmentation Analysis:
By Material Type:
The Automotive Wire and Cable Materials Market features a diverse range of material types tailored to meet demanding automotive requirements. Polyvinyl Chloride (PVC) dominates the segment due to its excellent electrical insulation, flexibility, and cost-effectiveness, making it a preferred choice for standard automotive wiring. Polypropylene (PP) offers resistance to chemicals and heat, supporting applications in environments with frequent exposure to fluids and elevated temperatures. Cross-linked Polyethylene (XLPE) stands out for its superior thermal stability, mechanical strength, and long lifespan, enabling its use in high-voltage and engine compartment wiring. Thermoplastic Polyurethane (TPU) finds demand in applications requiring abrasion resistance, elasticity, and durability, including wiring harnesses exposed to dynamic movement. Polyphenylene Ether (PPE) provides outstanding flame retardance and electrical properties, which enhance safety in critical automotive systems. The "Others" category includes fluoropolymers, polyurethane, neoprene, ethylene propylene rubber, and co-polyester elastomer, each offering specialized performance such as chemical resistance, flexibility, and low-temperature capability. The market responds to evolving vehicle architectures and regulatory requirements by innovating material formulations that balance safety, cost, and environmental sustainability.
By Vehicle Type:
Segmentation by vehicle type in the Automotive Wire and Cable Materials Market highlights the varying needs of different automotive categories. Passenger vehicles, representing the largest segment, encompass compact cars, sub-compact cars, mid-size cars, sedans, luxury cars, and vans. Each sub-segment demands unique wiring solutions; for example, luxury cars and sedans often require advanced materials to support sophisticated infotainment and safety systems, while compact and sub-compact cars prioritize cost-efficient solutions. The market recognizes growing material requirements for wiring in Light Commercial Vehicles (LCV) and Heavy Commercial Vehicles (HCV), as these vehicles increasingly incorporate connectivity, safety, and emission control features. It supplies robust materials to meet the durability and reliability needs of commercial fleets, which typically operate under higher loads and harsher environments. Product development across these segments emphasizes lighter weight, improved heat and abrasion resistance, and compliance with evolving automotive standards. By catering to the distinct demands of each vehicle category, the market ensures comprehensive support for innovation and efficiency across the global automotive industry.
Segments:
Based on Material Type:
- Polyvinyl Chloride (PVC)
- Polypropylene (PP)
- Cross-linked Polyethylene (XLPE)
- Thermoplastic Polyurethane (TPU)
- Polyphenylene Ether (PPE)
- Others (Fluoropolymers, Polyurethane, Neoprene, Ethylene Propylene Rubber, Co-polyester Elastomer)
Based on Vehicle Type:
- Passenger Vehicle
- Compact Cars
- Sub-compact Cars
- Mid-size Cars
- Sedan
- Luxury Cars
- Vans
- Light Commercial Vehicle (LCV)
- Heavy Commercial Vehicle (HCV)
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
Asia Pacific
Asia Pacific dominates the Automotive Wire and Cable Materials Market, accounting for approximately 45% of the global market share in 2024. The region’s leadership stems from its robust automotive manufacturing ecosystem, led by countries such as China, Japan, South Korea, and India. China, in particular, represents the world’s largest automotive market, driving significant demand for advanced wiring and cable materials to support growing vehicle production, technological innovation, and electrification. Government initiatives to promote electric vehicles and local investments in research and development further strengthen the region’s market position. Japan and South Korea continue to play crucial roles by focusing on high-performance, environmentally friendly materials. India’s fast-growing automotive sector and increased foreign direct investment contribute to the expansion of material suppliers and manufacturing bases. The widespread adoption of passenger vehicles, light commercial vehicles, and heavy commercial vehicles in these countries propels continuous growth, with manufacturers prioritizing durable, lightweight, and heat-resistant materials for next-generation vehicles. The Asia Pacific region remains the focal point for global automotive supply chains, attracting both domestic and international material suppliers.
Europe
Europe holds the second-largest share of the Automotive Wire and Cable Materials Market, capturing nearly 28% of the global market in 2024. The region’s position is underpinned by its reputation for automotive engineering excellence, stringent safety and environmental regulations, and a strong presence of premium car manufacturers in Germany, France, the United Kingdom, and Italy. European automakers lead in the integration of innovative materials that comply with evolving emission standards and offer high thermal and mechanical performance. Demand for advanced wire and cable materials rises with the growing market for electric and hybrid vehicles, supported by favorable government policies and consumer awareness of sustainable mobility. The market in Europe also benefits from ongoing investments in connected car technologies and autonomous driving systems, which require robust, high-quality wiring solutions. Suppliers in the region focus on halogen-free, recyclable, and lightweight polymers that meet regulatory and sustainability targets. The established automotive supply chain network and a tradition of technical leadership help maintain Europe’s stronghold in material innovation and adoption.
North America
North America contributes approximately 18% of the global market share for Automotive Wire and Cable Materials. The United States, Canada, and Mexico collectively support a mature automotive market characterized by continuous innovation, particularly in connected and electric vehicles. Automakers in the region rapidly incorporate advanced driver-assistance systems, digital dashboards, and high-powered EV components, fueling the need for high-performance, heat-resistant, and environmentally friendly wire and cable materials. Stringent safety and emission standards at both federal and state levels drive the adoption of new material technologies. The presence of leading automotive OEMs and a strong focus on vehicle electrification position North America as a critical market for specialized wire and cable solutions. Suppliers adapt to the evolving regulatory landscape and invest in research and product development, targeting both passenger and commercial vehicle segments. Cross-border collaborations and trade agreements further strengthen the region’s role in the global market.
Rest of the World
The Rest of the World, encompassing regions such as Latin America, the Middle East, and Africa, holds a combined market share of roughly 9% in 2024. While these markets remain smaller in absolute terms, they exhibit promising growth potential driven by increasing vehicle production, urbanization, and the gradual adoption of electric mobility. Latin America, led by Brazil and Mexico, shows steady growth in automotive manufacturing and aftermarket demand for high-quality wire and cable materials. The Middle East and Africa see rising investments in infrastructure, coupled with growing consumer demand for safer and more reliable vehicles, which drives interest in advanced wiring solutions. Market participants focus on tailoring materials to meet local regulatory, climate, and operational requirements. The Rest of the World represents an emerging opportunity for global suppliers seeking to diversify their presence and tap into new automotive growth frontiers.
Key Player Analysis
- Yazaki Corporation
- Coficab Tunisie SA
- Draka Holdings B.V.
- Leoni AG
- Coroplast Fritz Muller GmbH & Co. KG
- ACOME
- Allied Wire & Cable Inc.
- Sumitomo Electric Industries, Ltd
- Delphi Automotive PLC
- Lear Corporation
Competitive Analysis
The competitive landscape of the Automotive Wire and Cable Materials Market features prominent players such as Yazaki Corporation, Leoni AG, Sumitomo Electric Industries, Ltd, ACOME, Allied Wire & Cable Inc., Coficab Tunisie SA, Coroplast Fritz Muller GmbH & Co. KG, Delphi Automotive PLC, Draka Holdings B.V., and Lear Corporation. These companies maintain a global footprint, leveraging advanced manufacturing capabilities, robust distribution networks, and extensive research and development initiatives to capture diverse customer needs in the automotive sector. They consistently invest in technological innovation to develop heat-resistant, lightweight, and eco-friendly materials that comply with stringent industry standards and support emerging trends such as vehicle electrification and connectivity. Strategic collaborations and long-term partnerships with leading automakers enable them to secure large-volume contracts and reinforce market presence. Continuous product innovation, responsiveness to regulatory requirements, and a focus on sustainable solutions position these players at the forefront of the industry. Intense competition encourages ongoing improvement in product performance, cost efficiency, and service delivery, allowing leading companies to adapt swiftly to market changes and maintain strong customer loyalty. Their commitment to quality and operational excellence drives both global expansion and industry leadership.
Recent Developments
- In May 2025, Leoni AGhas entered into an agreement with Stark Corporation Public Company Limited for the sale of the Automotive Cable Solutions business group, which is a part of the Automotive Wire Material and Wire & Cable Solutions (WCS) division. This strategic decision will enable the company to shift its focus towards the Wiring Systems division.
- In May 2022, Leoni AG signed an agreement with Stark Corporation Public Company Limited on sale of the Business Group Automotive Cable Solutions belonging to the automotive wire materials and Wire & Cable Solutions (WCS) Division. With this decision, the company is expected to strategically focus on wiring systems division.
- In February 23, 2022, TTTech Auto, a Vienna-based technology leader in automotive safety software, raised US$ 285 Mn (EUR 250 million) from Aptiv PLC (NYSE: APTV) and Audi in its latest funding round. The investment is expected to enable TTTech Auto to accelerate progress in three strategic areas: diversifying its product portfolio for automotive manufacturers and its technology partners, expanding internationally in key regions, and extending its capabilities through strategic M&A and product investments.
Market Concentration & Characteristics
The Automotive Wire and Cable Materials Market demonstrates a moderate to high level of market concentration, with a handful of established players dominating global supply. It features significant barriers to entry due to the technical expertise, regulatory compliance, and capital investment required to compete effectively. The market is characterized by strong emphasis on quality, safety, and continuous innovation, with manufacturers prioritizing advanced material formulations to address evolving industry standards. Long-term partnerships with leading automakers and tier-one suppliers enable top companies to secure consistent demand and maintain a competitive edge. It supports rapid adoption of new technologies, including high-voltage wiring for electric vehicles and environmentally responsible compounds. Intense competition drives companies to enhance manufacturing efficiency, invest in research and development, and provide customized solutions that meet diverse regional and segment-specific requirements. The market’s dynamic environment fosters ongoing advancements in product durability, flexibility, and sustainability
Report Coverage
The research report offers an in-depth analysis based on Material Type, Vehicle Type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is projected to experience substantial growth from 2025 to 2032, driven by increasing vehicle electrification and the adoption of advanced driver-assistance systems (ADAS).
- Asia-Pacific is expected to retain its dominance in the market, owing to the rising popularity of electric vehicles and the presence of major automotive manufacturers in the region.
- The demand for high-performance cabling solutions is anticipated to rise, fueled by the need for efficient power transmission and enhanced safety features in modern vehicles.
- The integration of advanced electronics and connectivity features in vehicles will necessitate the development of specialized wire and cable materials that can handle higher data transmission rates.
- Sustainability concerns are likely to drive innovation in the market, with a focus on developing recyclable and environmentally friendly materials to meet regulatory standards.
- The market is expected to witness increased investments in research and development activities aimed at enhancing the thermal and mechanical properties of wire and cable materials.
- The growing complexity of vehicle electrical systems will require materials that offer superior performance characteristics, including heat resistance and durability.
- Collaborations between automotive manufacturers and material suppliers are anticipated to play a crucial role in developing customized solutions that meet specific vehicle requirements.
- The market is likely to benefit from the expansion of the automotive industry in emerging economies, where increasing vehicle production will drive the demand for wire and cable materials.
- Technological advancements in material science are expected to lead to the development of next-generation wire and cable materials that offer improved performance and cost-effectiveness.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Vehicle Electrification and Advanced Technologies
The rapid growth of electric and hybrid vehicles is increasing the need for high-performance, heat-resistant, and lightweight wire and cable materials to support efficient power transmission and advanced connectivity in modern vehicles.
Stringent Safety and Emission Regulations
Global regulatory requirements for vehicle safety and emissions are compelling manufacturers to adopt innovative, halogen-free, and flame-retardant materials, driving ongoing R&D and material innovation in the market.
Growth of Connected and Autonomous Vehicles
The proliferation of ADAS, V2X, and digital dashboards in connected and autonomous vehicles is boosting demand for specialized wiring solutions that ensure reliable data transmission and electromagnetic compatibility.
Industry Shift Toward Lightweight and Eco-Friendly Materials
Automotive OEMs are prioritizing lightweight, recyclable, and environmentally responsible compounds to reduce vehicle weight and meet sustainability goals, spurring the development and adoption of advanced wire and cable materials.
Expansion of Automotive Production in Asia Pacific
Robust automotive manufacturing and rising EV adoption in Asia Pacific, especially in China, Japan, and India, are driving substantial demand for advanced wire and cable materials, reinforcing the region's dominance in the global market.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Automotive Wire and Cable Materials Market?
What factors are driving the growth of the Automotive Wire and Cable Materials Market?
What are some challenges faced by the Automotive Wire and Cable Materials Market?
Who are the major players in the Automotive Wire and Cable Materials Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Power Transmission
- 1.2.2 Data Transmission & Connectivity
- 1.2.3 Safety & Control Systems
- 1.2.4 Infotainment & Communication
- 1.3 By Vehicle Type
- 1.3.1 Passenger Vehicle (Compact Cars, Sub-compact Cars, Mid-size Cars, Sedan, Luxury Cars, Vans)
- 1.3.2 Light Commercial Vehicle (LCV)
- 1.3.3 Heavy Commercial Vehicle (HCV)
- 1.4 By Material Type
- 1.4.1 Polyvinyl Chloride (PVC)
- 1.4.2 Polypropylene (PP)
- 1.4.3 Cross-linked Polyethylene (XLPE)
- 1.4.4 Thermoplastic Polyurethane (TPU)
- 1.4.5 Polyphenylene Ether (PPE)
- 1.4.6 Others (Fluoropolymers, Polyurethane, Neoprene, Ethylene Propylene Rubber, Co-polyester Elastomer)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,150 million → 2032: USD 3,124 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Automotive Wire and Cable Materials Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Automotive Wire and Cable Materials Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Automotive Wire and Cable Materials Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Automotive Wire and Cable Materials Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Automotive Wire and Cable Materials Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Automotive Wire and Cable Materials Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Automotive Wire and Cable Materials Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Automotive Wire and Cable Materials Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,150 million → 2032: USD 3,124 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Automotive Wire and Cable Materials Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Power Transmission
- 12.3.7.2 Data Transmission & Connectivity
- 12.3.7.3 Safety & Control Systems
- 12.3.7.4 Infotainment & Communication
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Vehicle Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Passenger Vehicle (Compact Cars, Sub-compact Cars, Mid-size Cars, Sedan, Luxury Cars, Vans)
- 12.4.7.2 Light Commercial Vehicle (LCV)
- 12.4.7.3 Heavy Commercial Vehicle (HCV)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Material Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Polyvinyl Chloride (PVC)
- 12.5.7.2 Polypropylene (PP)
- 12.5.7.3 Cross-linked Polyethylene (XLPE)
- 12.5.7.4 Thermoplastic Polyurethane (TPU)
- 12.5.7.5 Polyphenylene Ether (PPE)
- 12.5.7.6 Others (Fluoropolymers, Polyurethane, Neoprene, Ethylene Propylene Rubber, Co-polyester Elastomer)
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Automotive Wire and Cable Materials End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Automotive Wire and Cable Materials Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Automotive Wire and Cable Materials Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Automotive Wire and Cable Materials Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Yazaki Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Leoni AG
- 18.4 Sumitomo Electric Industries, Ltd
- 18.5 Coficab Tunisie SA
- 18.6 Draka Holdings B.V.
- 18.7 Coroplast Fritz Muller GmbH & Co. KG
- 18.8 ACOME
- 18.9 Allied Wire & Cable Inc.
- 18.10 Delphi Automotive PLC
- 18.11 Lear Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

