
Market Overview
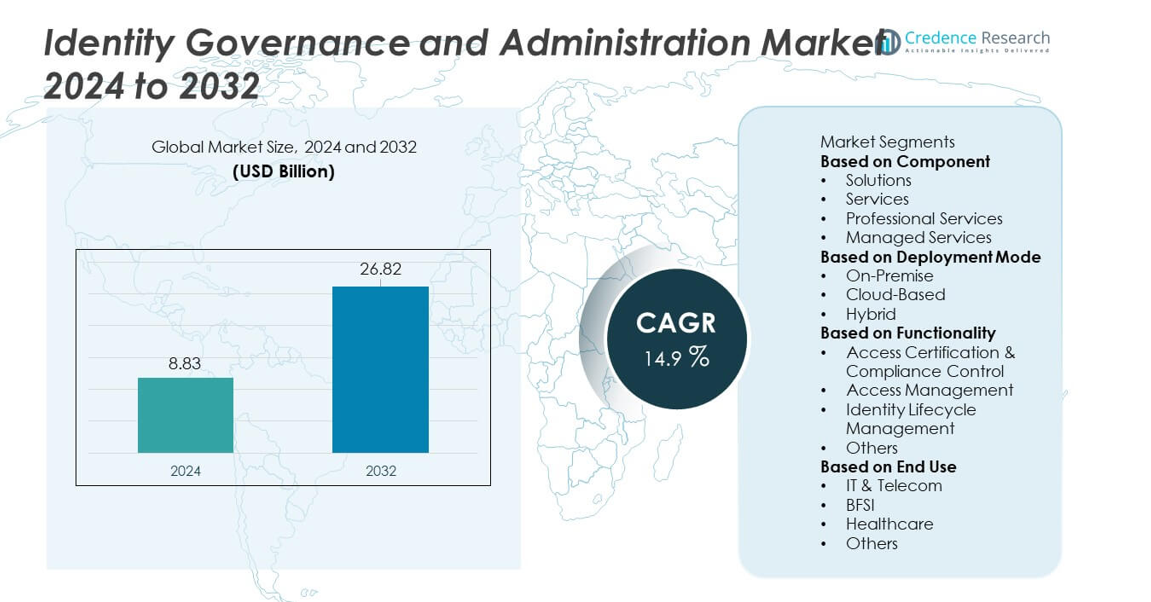
The Identity Governance and Administration (IGA) market reached USD 8.83 billion in 2024 and is projected to grow to USD 26.82 billion by 2032, registering a CAGR of 14.9% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Identity Governance and Administration Market Size 2024 | USD 8.83 billion |
| Identity Governance and Administration Market, CAGR | 14.9% |
| Identity Governance and Administration Market Size 2032 | USD 26.82 billion |
The Identity Governance and Administration market is shaped by leading players such as Microsoft Corporation, Okta, Inc., IBM Corporation, CyberArk Software Ltd., Imprivata, Inc., Oracle Corporation, Amazon Web Services, Inc., Micro Focus International plc, Evidian (Atos SE), and Broadcom Inc. (Symantec), all of which enhance market growth through advanced identity lifecycle tools, automated access governance, and AI-enabled risk analytics. These companies strengthen zero-trust adoption and expand cloud-native IGA capabilities to support hybrid and multi-cloud environments. North America leads the market with a 39% share, followed by Europe at 28%, driven by strict compliance requirements, while Asia Pacific holds a 23% share due to rapid digital transformation and rising cybersecurity investments.
Market Insights
- The Identity Governance and Administration market reached USD 8.83 billion in 2024 and will grow at a CAGR of 14.9% through 2032, supported by rising digitalization and identity security needs.
- Growing compliance pressure and stricter data protection laws drive strong demand for IGA solutions, with the solutions segment holding a 62% share due to high adoption of unified governance platforms.
- AI-enabled identity analytics, automated lifecycle workflows, and cloud-native governance tools shape major market trends as enterprises strengthen zero-trust and hybrid security models.
- Leading players, including Microsoft, IBM, Okta, CyberArk, and AWS, enhance competition through advanced integration capabilities, while high deployment complexity remains a key restraint for smaller organizations.
- Regionally, North America leads with a 39% share, Europe follows with 28%, and Asia Pacific holds 23%, driven by increasing cloud adoption and rising demand for identity risk management across regulated industries.
Market Segmentation Analysis:
By Component
Solutions lead the Identity Governance and Administration market with a 62% share, driven by growing enterprise demand for unified identity management, automated access provisioning, and real-time compliance monitoring. Organizations adopt advanced IGA solutions to manage rising identity volumes across cloud, mobile, and hybrid environments. Services, including both professional and managed services, continue to grow as enterprises seek support for deployment, integration, and policy optimization. Managed services gain attention for lowering operational burdens and delivering continuous monitoring. Increasing cybersecurity risks and stricter regulatory requirements further push organizations to adopt robust and scalable IGA platforms.
- For instance, Microsoft has introduced the Security Copilot Access Review Agent in Microsoft Entra ID (formerly Azure AD), which uses AI and machine learning to analyze user activity and provide data-driven recommendations to reviewers, thereby accelerating access reviews for large enterprises.
By Deployment Mode
Cloud-based deployment dominates with a 54% share, supported by rapid digital transformation and the shift toward SaaS-based identity management platforms. Enterprises choose cloud IGA for scalability, faster rollout, and lower infrastructure costs. Hybrid deployment gains traction among large organizations that balance on-premise security control with cloud flexibility. On-premise solutions remain relevant for highly regulated sectors needing strict data governance. Rising cloud workloads, remote work expansion, and demand for centralized identity oversight reinforce the dominance of cloud-based IGA deployments across global markets.
- For instance, Oracle Cloud Infrastructure (OCI) Identity and Access Management (IAM) provides enterprise-class identity and access management capabilities, including multifactor authentication (MFA) and single sign-on (SSO), for both Oracle and non-Oracle applications.
By Functionality
Identity lifecycle management leads the segment with a 47% share, driven by the need to automate onboarding, role assignments, privilege adjustments, and deprovisioning across diverse systems. Enterprises focus on reducing manual errors and improving security posture through continuous identity updates. Access management also records strong growth as organizations implement zero-trust models and multi-factor authentication. Access certification and compliance control expand due to tighter audit requirements and data governance mandates. Increasing identity complexity, multi-cloud adoption, and rising insider threats continue to support broad adoption across all IGA functionalities.
Key Growth Drivers
Rising Regulatory Compliance Requirements
Strict global regulations push enterprises to adopt strong Identity Governance and Administration solutions. Frameworks such as GDPR, HIPAA, SOX, and PCI-DSS require tight control over user access, audit readiness, and policy enforcement. Organizations deploy automated identity workflows to reduce compliance risks and maintain consistent privilege management across cloud and on-premise systems. Growing penalties for data misuse and unauthorized access increase adoption of centralized governance tools. As enterprises expand digital operations, regulatory pressure continues to act as a major catalyst for IGA deployment.
- For instance, the broader IBM X-Force threat intelligence team obtains its insights from monitoring over 150 billion security events per day across more than 130 countries.
Expansion of Cloud Adoption and Digital Transformation
Enterprises accelerate cloud migration and modernize IT systems, creating a surge in identity volumes across applications, devices, and hybrid environments. This expansion increases demand for identity lifecycle automation, role-based access models, and unified governance platforms. Cloud-based IGA solutions offer scalability and rapid deployment, supporting fast-growing digital operations. Organizations adopt zero-trust frameworks that require continuous identity validation and real-time access visibility. As multi-cloud ecosystems expand, IGA becomes essential for keeping identities secure, consistent, and compliant.
- For instance, Okta processes more than 19 billion monthly authentication requests across global clients, supporting high-growth cloud environments.
Increasing Cybersecurity Threats and Insider Risks
Rising cyberattacks and insider-driven breaches drive strong demand for automated access governance. Enterprises deploy IGA platforms to control privileged accounts, detect abnormal access behavior, and reduce manual provisioning errors. Identity misuse remains a major entry point for attackers, increasing the need for monitoring and policy-driven access decisions. Automated certification, role optimization, and continuous access reviews enhance security posture. As workforce mobility grows, organizations rely on IGA to ensure secure access across remote teams, third-party vendors, and distributed digital ecosystems.
Key Trends & Opportunities
Growing Integration of AI and Automation in Identity Governance
AI-driven analytics help organizations detect anomalies, optimize access roles, and automate certification workflows. Machine learning enhances identity risk scoring, enabling faster decisions and reducing manual oversight. Intelligent recommendations streamline privilege allocation and identify unnecessary access rights. Vendors invest in advanced automation that simplifies large-scale governance tasks and improves compliance reporting. This trend creates opportunities for predictive identity management and real-time threat response within IGA ecosystems.
- For instance, SailPoint Identity Security Cloud leverages AI and machine learning to provide access recommendations and automate governance processes, helping organizations make more accurate and informed access decisions.
Rising Demand for Unified Identity Platforms in Hybrid Environments
Organizations adopt unified IGA platforms to manage identities across on-premise systems, SaaS applications, and multi-cloud architectures. Centralized dashboards offer better visibility into user privileges and improve governance efficiency. Growing complexity in hybrid environments pushes enterprises to seek seamless integration across directories, HR systems, and security tools. Vendors offering flexible and interoperable platforms gain strong market momentum. Increasing hybrid workforce models further accelerate the need for unified identity governance.
- For instance, CyberArk helps secure over 10,000 global customers, including more than 55% of the Fortune 500 and over 35% of the Global 2000. These organizations leverage CyberArk's identity security platform to manage and secure access across a mix of environments.
Key Challenges
High Deployment and Integration Complexity
Large enterprises face challenges integrating IGA systems with legacy applications, on-premise architectures, and diverse cloud platforms. Complex identity structures require extensive customization, extending deployment time and cost. Many organizations lack skilled personnel to manage advanced IGA configurations, slowing system adoption. Ensuring smooth synchronization across multiple identity sources remains difficult for IT teams. These complexities often hinder organizations from achieving full automation and governance efficiency.
Rising Costs for Implementation and Long-Term Maintenance
Implementing a comprehensive IGA platform requires significant investment in software, consulting, integration, and ongoing support. Small and mid-sized enterprises often struggle with budget constraints, limiting adoption of advanced governance tools. Continuous updates, compliance audits, and license renewals increase operational expenses. Organizations must invest in skilled resources to maintain identity workflows, access policies, and governance rules. These financial and resource burdens remain key obstacles to widespread IGA adoption.
Regional Analysis
North America
North America leads the Identity Governance and Administration market with a 39% share, driven by strong regulatory frameworks, rapid cloud adoption, and high cybersecurity awareness among enterprises. U.S.-based organizations invest heavily in automated identity lifecycle tools to meet strict compliance standards like HIPAA, SOX, and FedRAMP. The region sees rising demand for cloud-based IGA platforms as businesses support large remote workforces and hybrid IT architectures. Advanced adoption of zero-trust security and growing insider threat concerns strengthen market growth. Major technology vendors and high digital maturity further reinforce North America’s dominant position.
Europe
Europe holds a 28% share, supported by strict enforcement of GDPR and sector-specific regulations that require consistent identity governance and secure access controls. Enterprises across Germany, the UK, and France invest in IGA platforms to manage complex identity structures across cloud and on-premise systems. The region’s strong focus on data privacy accelerates adoption of automated certification workflows and risk-based access policies. Growing digital transformation in financial services, manufacturing, and public sectors enhances demand. Increased awareness of identity-related breaches and rising hybrid environments strengthen Europe’s role in the global IGA market.
Asia Pacific
Asia Pacific commands a 23% share, driven by rapid enterprise digitization, large-scale cloud migration, and growing cybersecurity threats. Companies across China, India, Japan, and Southeast Asia adopt IGA platforms to manage expanding identity volumes and strengthen compliance with evolving data protection laws. The region’s increasing adoption of SaaS applications and hybrid IT models boosts demand for scalable governance solutions. Growth in banking, telecom, and IT services accelerates need for automated access controls and lifecycle management. Rising investments in digital infrastructure and expanding remote work contribute to strong regional momentum.
Latin America
Latin America holds a 6% share, supported by growing digital transformation and increasing adoption of identity security tools across financial services, retail, and public sectors. Brazil and Mexico lead demand as enterprises strengthen governance frameworks to address rising cyber threats and comply with new data protection laws. Cloud adoption continues to expand, driving interest in scalable IGA platforms. Limited identity expertise and budget constraints slow adoption in smaller organizations, but rising awareness of access risks supports steady growth. Investments in secure digital services and government modernization initiatives further drive regional expansion.
Middle East & Africa
The Middle East & Africa region accounts for a 4% share, driven by growing cybersecurity investments and rising adoption of identity governance solutions in banking, oil and gas, and government sectors. GCC countries lead with rapid deployment of cloud-based IGA platforms to support national digital transformation programs. Increasing cyberattacks and insider risks push enterprises to adopt automated access monitoring and certification tools. Regulatory modernization in data privacy strengthens market potential, though adoption remains slower in parts of Africa. Expanding cloud infrastructure and enterprise modernization efforts continue to support gradual growth in the region.
Market Segmentations:
By Component
- Solutions
- Services
- Professional Services
- Managed Services
By Deployment Mode
- On-Premise
- Cloud-Based
- Hybrid
By Functionality
- Access Certification & Compliance Control
- Access Management
- Identity Lifecycle Management
- Others
By End Use
- IT & Telecom
- BFSI
- Healthcare
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape features leading companies such as Microsoft Corporation, Okta, Inc., IBM Corporation, CyberArk Software Ltd., Imprivata, Inc., Oracle Corporation, Amazon Web Services, Inc., Micro Focus International plc, Evidian (Atos SE), and Broadcom Inc. (Symantec), all of which shape the Identity Governance and Administration market through advanced security capabilities and strong integration frameworks. These players focus on AI-driven identity analytics, automated access workflows, and unified governance platforms that support both cloud and hybrid environments. Vendors expand partnerships with enterprises to strengthen zero-trust adoption and improve compliance readiness. Continuous R&D enhances identity lifecycle automation, privileged access controls, and risk-based authentication. Many companies also invest in cloud-native IGA solutions that scale with growing identity volumes driven by digital transformation. As cyber threats rise, competition intensifies around real-time monitoring, anomaly detection, and interoperability with broader security ecosystems, reinforcing the market’s innovation-driven growth.
Key Player Analysis
- Microsoft Corporation
- Okta, Inc.
- IBM Corporation
- CyberArk Software Ltd.
- Imprivata, Inc.
- Oracle Corporation
- Amazon Web Services, Inc.
- Micro Focus International plc
- Evidian (Atos SE)
- Broadcom Inc. (Symantec)
Recent Developments
- In February 2025, CyberArk Software Ltd. acquired Zilla Security to integrate AI-powered IGA capabilities into its Identity Security Platform.
- In 2025, IBM Corporation ranks among the top three IAM/IGA providers according to a 2025 buyers’ guide.
- In December 2024, Imprivata, Inc. sold its IGA business to SailPoint and entered into a strategic go-to-market partnership focused on healthcare identity and access management
Report Coverage
The research report offers an in-depth analysis based on Component, Deployment Mode, Functionality, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for automated identity lifecycle management will rise as enterprises scale digital operations.
- Cloud-based IGA platforms will gain wider adoption due to flexibility and faster deployment.
- Zero-trust security models will increase reliance on continuous identity verification and access oversight.
- AI-driven identity risk scoring will strengthen real-time threat detection and policy decisions.
- Unified governance platforms will grow as organizations manage identities across hybrid and multi-cloud ecosystems.
- Privileged access governance will expand as insider threats and credential misuse increase.
- Regulatory pressure will drive more enterprises to adopt advanced compliance automation tools.
- Integration of IGA with broader security ecosystems will improve visibility and incident response.
- SMEs will adopt simplified and cost-effective IGA solutions as vendor offerings become more modular.
- Identity governance will shift toward predictive models that reduce manual intervention and enhance security outcomes.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Regulatory Compliance Requirements
Global regulations such as GDPR, HIPAA, SOX, and PCI-DSS require organizations to implement robust identity governance, driving adoption of IGA solutions to ensure audit readiness, policy enforcement, and reduced compliance risks.
Expansion of Cloud Adoption and Digital Transformation
As enterprises migrate to cloud and hybrid environments, the need for scalable, automated identity management grows, fueling demand for cloud-based IGA platforms that support rapid deployment and unified governance across diverse IT landscapes.
Increasing Cybersecurity Threats and Insider Risks
The surge in cyberattacks and insider-driven breaches compels organizations to deploy IGA platforms for automated access governance, privileged account control, and continuous monitoring, reducing the risk of identity misuse and unauthorized access.
Growing Integration of AI and Automation
AI-driven analytics and automation streamline identity workflows, enable real-time threat detection, and optimize access roles, making IGA solutions more efficient and attractive for organizations seeking to reduce manual intervention and improve security outcomes.
Demand for Unified Identity Platforms in Hybrid Environments
The complexity of managing identities across on-premise, SaaS, and multi-cloud systems is pushing organizations to adopt unified IGA platforms, which offer centralized visibility, seamless integration, and improved governance efficiency.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Identity Governance and Administration market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Identity Governance and Administration market projected to grow between 2025 and 2032?
Who are the major players in this market?
What are the primary factors fueling the growth of the Identity Governance and Administration market?
Who are the leading companies in the Identity Governance and Administration market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 IT & Telecom
- 1.2.2 BFSI
- 1.2.3 Healthcare
- 1.2.4 Others
- 1.3 By Component
- 1.3.1 Solutions
- 1.3.2 Services
- 1.3.3 Professional Services
- 1.3.4 Managed Services
- 1.4 By Functionality
- 1.4.1 Access Certification & Compliance Control
- 1.4.2 Access Management
- 1.4.3 Identity Lifecycle Management
- 1.4.4 Others
- 1.5 By Deployment Mode
- 1.5.1 On-Premise
- 1.5.2 Cloud-Based
- 1.5.3 Hybrid
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 8.83 billion → 2032: USD 26.82 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Identity Governance And Administration Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Identity Governance And Administration Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Identity Governance And Administration Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Identity Governance And Administration Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Identity Governance And Administration Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Identity Governance And Administration Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Identity Governance And Administration Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Identity Governance And Administration Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 8.83 billion → 2032: USD 26.82 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Identity Governance And Administration Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 IT & Telecom
- 12.3.7.2 BFSI
- 12.3.7.3 Healthcare
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Component - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Solutions
- 12.4.7.2 Services
- 12.4.7.3 Professional Services
- 12.4.7.4 Managed Services
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Functionality - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Access Certification & Compliance Control
- 12.5.7.2 Access Management
- 12.5.7.3 Identity Lifecycle Management
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Deployment Mode - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 On-Premise
- 12.6.7.2 Cloud-Based
- 12.6.7.3 Hybrid
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Identity Governance And Administration End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Identity Governance And Administration Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Identity Governance And Administration Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Identity Governance And Administration Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Microsoft Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Okta, Inc.
- 18.4 IBM Corporation
- 18.5 CyberArk Software Ltd.
- 18.6 Imprivata, Inc.
- 18.7 Oracle Corporation
- 18.8 Amazon Web Services, Inc.
- 18.9 Micro Focus International plc
- 18.10 Evidian (Atos SE)
- 18.11 Broadcom Inc. (Symantec)
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

