
Market Overview
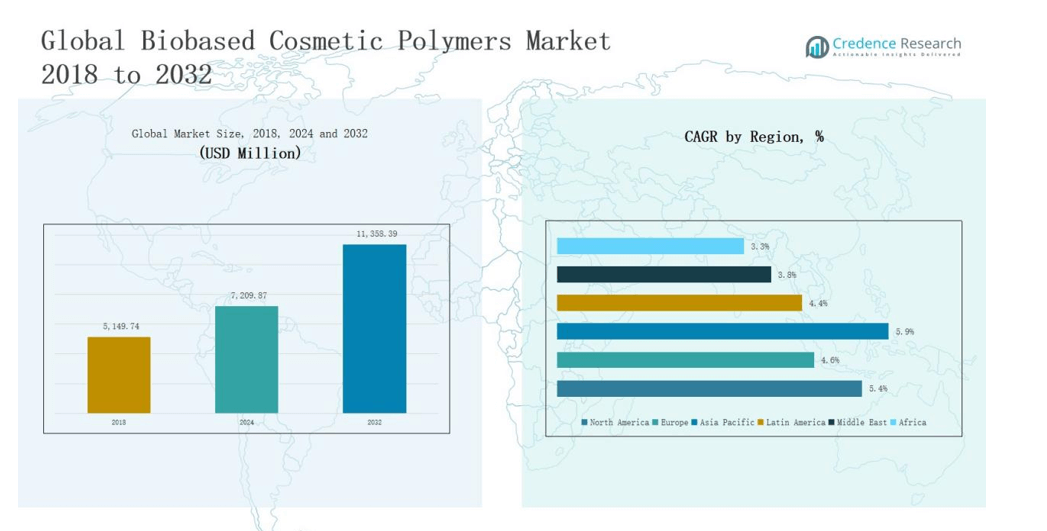
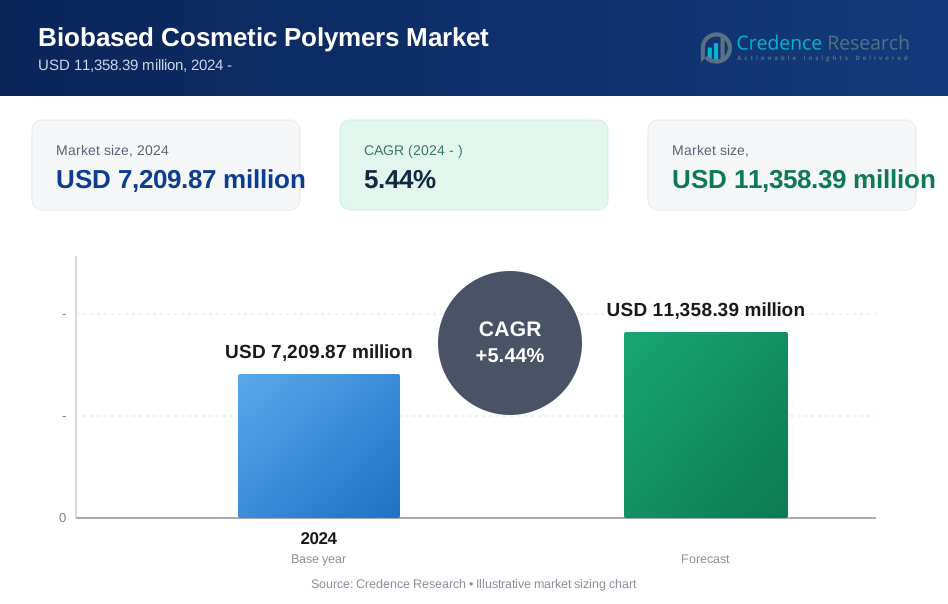
Global Biobased Cosmetic Polymers Market size was valued at USD 5,149.74 million in 2018 to USD 7,209.87 million in 2024 and is anticipated to reach USD 11,358.39 million by 2032, at a CAGR of 5.44% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Biobased Cosmetic Polymers Market Size 2024 | USD 7,209.87 million |
| Biobased Cosmetic Polymers Market, CAGR | 5.44% |
| Biobased Cosmetic Polymers Market Size 2032 | USD 11,358.39 million |
The Global Biobased Cosmetic Polymers Market is shaped by leading players such as BASF SE, Dow, Solvay, Ashland, Lubrizol, Evonik, dsm-firmenich, Givaudan Active Beauty, Croda, Clariant, CP Kelco, Gelymar, KitoZyme, EcoSynthetix, and Nouryon, all of which focus on innovation, sustainability, and expanding product portfolios. These companies leverage advanced biotechnology, fermentation processes, and eco-certifications to strengthen competitiveness and meet rising demand for clean beauty solutions. Regionally, Asia Pacific dominates the market with a 45% share in 2024, driven by strong consumption in China, Japan, South Korea, and India, supported by urbanization, higher disposable incomes, and rapid adoption of natural cosmetic formulations.
Market Insights
- The Global Biobased Cosmetic Polymers Market is projected to grow from USD 7,209.87 million in 2024 to USD 11,358.39 million by 2032 at a 5.44% CAGR.
- Styling/fixatives and film formers lead by function with a 34% share in 2024, driven by demand for long-lasting styling and clean-label formulations.
- Polysaccharides dominate by chemistry/origin with a 41% share in 2024, supported by wide availability, versatility, and strong adoption in eco-conscious cosmetic formulations.
- Hair care leads by application with a 39% share in 2024, boosted by rising demand for sulfate-free, vegan, and organic shampoos, conditioners, and styling products.
- Asia Pacific holds the largest 45% share in 2024, driven by China, Japan, South Korea, and India, while North America and Europe follow with 28% and 17% respectively.
Market Segment Insights
By Function
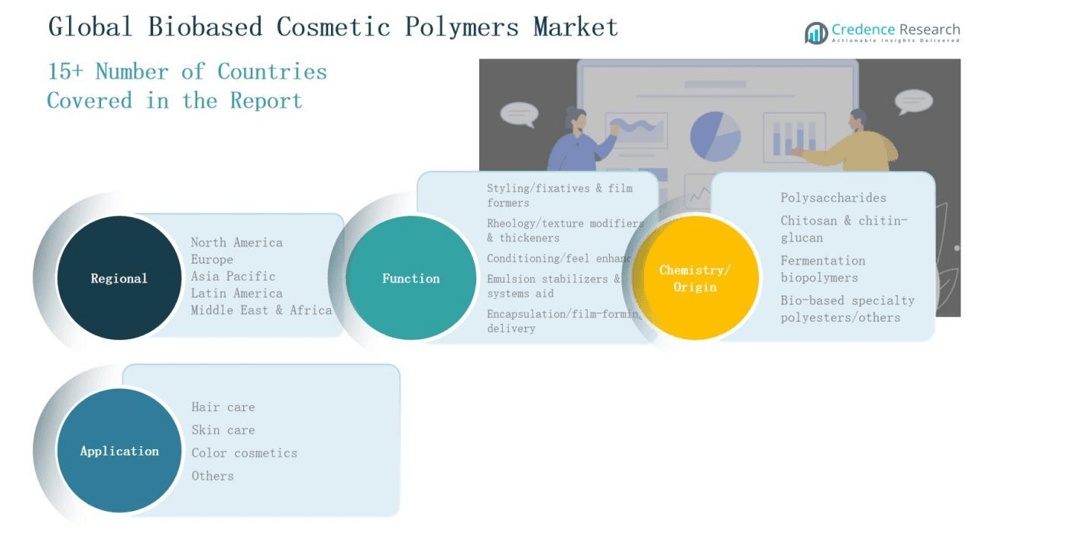
Styling/fixatives & film formers dominate the function segment with a 34% share in 2024. Their strong adoption stems from rising demand for long-lasting hair styling, hold, and color protection solutions. Consumers prefer natural, biodegradable film formers over synthetic variants, particularly in clean-label and premium cosmetics. Growth is further supported by innovation in plant-based polymers that deliver flexibility, humidity resistance, and improved product performance across hair gels, sprays, and setting formulations.
- For instance, Dow’s MaizeCare™ Style Polymer a corn-derived, biodegradable film former provides flexible hold, humidity resistance, and curl retention in products such as sprays and gels
By Chemistry/Origin
Polysaccharides lead the chemistry/origin segment with a 41% share in 2024. Their dominance comes from wide availability, biocompatibility, and versatile functionality in thickening, stabilizing, and conditioning roles. Natural sources such as cellulose, guar, and xanthan gum attract eco-conscious brands seeking sustainable alternatives to petrochemical-based polymers. Increasing demand for botanical and food-derived actives in cosmetics further strengthens polysaccharides’ role as the preferred biopolymer base across multiple formulations.
- For instance, BASF expanded its Verdessence portfolio by launching Verdessence Tara, a tara gum-based biopolymer designed to provide sustainable thickening and stability in skin and hair care formulations.
By Application
Hair care represents the largest application segment, accounting for a 39% share in 2024. The segment benefits from rising global spending on shampoos, conditioners, and styling products enriched with natural polymers. Consumer preference for products offering improved texture, frizz control, and scalp safety fuels adoption. Growing interest in sulfate-free, vegan, and organic hair formulations supports higher demand for biobased polymers as functional and label-friendly ingredients.
Market Overview
Rising Demand for Sustainable Ingredients
Growing consumer preference for eco-friendly personal care products drives demand for biobased cosmetic polymers. Brands are under pressure to reduce microplastic use and adopt biodegradable ingredients. Regulations in Europe and North America further restrict synthetic polymers, favoring natural substitutes. This shift accelerates innovation in plant-derived polymers that provide equivalent performance while meeting sustainability commitments. Companies leveraging biobased formulations gain market share by aligning with consumer values of clean beauty, safety, and environmental responsibility, making sustainability the central growth engine of this market.
- For instance, Biopolax introduced plant-based biopolymer additives like Glucover 01 SB/PS, a sulfate-free rheology modifier for personal care formulations, providing a biodegradable alternative to chemical surfactants in shampoos and shower gels.
Expanding Applications Across Cosmetic Categories
Biobased cosmetic polymers gain traction across hair care, skin care, and color cosmetics. Their roles as film formers, thickeners, stabilizers, and conditioning agents enable broad formulation versatility. Rising adoption in premium and mass-market cosmetics enhances scalability for manufacturers. Hair styling products, anti-aging creams, and sunscreens increasingly incorporate these polymers for performance and sensory benefits. This functional diversity boosts their commercial appeal and secures long-term demand. Expanding penetration across diverse formulations ensures steady growth opportunities for suppliers in global cosmetic value chains.
- For instance, Clariant expanded its Vita bio-based surfactants and polyethylene glycols portfolio, enabling formulators to create renewable-based creams and lotions with up to 100% renewable carbon content.
Technological Innovations in Biopolymer Development
Ongoing R&D in biotechnology, fermentation, and green chemistry fosters novel biopolymer solutions. Companies develop high-performance variants of chitosan, polysaccharides, and specialty polyesters with superior stability, bioavailability, and compatibility. Advanced encapsulation technologies using biobased polymers improve delivery of actives in creams and serums. Such innovations enhance consumer experience with better texture, spreadability, and product efficacy. Strategic collaborations between cosmetic firms and biotech companies further accelerate commercialization. Continuous advancements strengthen competitiveness of biobased polymers against synthetic options, positioning them as core ingredients in next-generation cosmetic formulations.
Key Trends & Opportunities
Growth in Clean Beauty and Premium Segments
The global clean beauty trend accelerates the shift toward biobased cosmetic polymers. Consumers pay higher premiums for products labeled vegan, natural, and safe for sensitive skin. Luxury cosmetic brands expand their natural product lines, creating significant opportunities for polymer suppliers. Transparency in sourcing and traceability adds further value. Partnerships with high-end brands ensure long-term adoption. This premiumization trend enhances margins and encourages greater investment in biobased polymer R&D. Rising awareness of health and wellness will continue fueling this opportunity.
- For instance, in 2024, Korean beauty brand "I'm From" launched a $23 rice cream with transparent sourcing, including GPS coordinates on packaging, emphasizing purity and traceability.
Rising Adoption in Emerging Markets
Emerging markets in Asia Pacific and Latin America provide untapped growth opportunities. Rising disposable incomes and beauty-conscious populations fuel demand for natural and sustainable cosmetic products. Local cosmetic firms adopt biobased polymers to differentiate offerings and comply with stricter safety regulations. Governments in these regions promote eco-friendly manufacturing and sustainable sourcing, further supporting adoption. Expanding distribution networks and e-commerce penetration allow wider consumer access. As awareness grows, these markets will represent key drivers of global volume growth for biobased cosmetic polymers.
- For instance, Shiseido's initiatives involving sustainable packaging in Asia in 2023 were more complex than a single launch. The "Sustainable Beauty Actions" program was launched globally in 2020.
Key Challenges
High Production Costs and Limited Economies of Scale
Biobased cosmetic polymers face higher production costs compared to conventional synthetic polymers. Dependence on natural feedstock and complex processing technologies limits cost competitiveness. Smaller manufacturers struggle with scaling operations, making price-sensitive consumers hesitant to switch. Limited availability of cost-effective supply chains further adds to challenges. Achieving economies of scale requires significant investment in production capacity and optimized sourcing. Until cost barriers are addressed, adoption in mass-market cosmetics may remain slower than expected, restraining broader market penetration.
Performance Limitations in Certain Applications
While biobased cosmetic polymers deliver eco-friendly benefits, they face performance gaps in some applications. Synthetic polymers often provide superior durability, water resistance, and consistency under extreme conditions. Meeting consumer expectations for high-performance cosmetics remains a challenge for natural polymers. Texture, stability, and sensory properties may vary depending on natural feedstock quality. Manufacturers must invest heavily in R&D to close performance gaps. Without equivalent or superior functional benefits, biobased alternatives risk losing ground to established synthetic ingredients in competitive product categories.
Regulatory and Supply Chain Complexities
The biobased cosmetic polymer market operates under evolving regulatory landscapes. Regional differences in cosmetic ingredient approvals and labeling standards create compliance hurdles for global players. Sourcing sustainable raw materials like algae, chitosan, or plant extracts poses challenges due to seasonal availability and agricultural risks. Supply chain disruptions affect reliability and cost stability. Companies must invest in traceability and certifications to maintain credibility. Navigating these complexities demands strong partnerships and regulatory expertise. Delays or inconsistencies in supply can hinder brand adoption and consumer confidence.
Regional Analysis
North America
North America holds a 28% share in 2024, supported by mature cosmetic industries in the U.S. and Canada. The region benefits from strong regulatory frameworks that favor sustainable ingredients and restrict synthetic microplastics. Rising consumer awareness of clean beauty and premium natural products accelerates adoption. Hair care and skincare brands lead demand, while innovative product launches expand market penetration. With revenues expected to rise from USD 2,082.28 million in 2024 to USD 3,294.05 million by 2032, the region is forecast to grow at a CAGR of 5.5%.
Europe
Europe accounts for a 17% share in 2024, reflecting robust demand in Germany, France, and the UK. Strict environmental regulations and consumer preference for eco-certified cosmetics strengthen the adoption of biobased polymers. Major European cosmetic manufacturers invest heavily in sustainable formulations, driving steady growth. The market value is projected to increase from USD 1,240.95 million in 2024 to USD 1,773.24 million by 2032, advancing at a CAGR of 4.2%. Europe remains a leader in product innovation and compliance-driven adoption, consolidating its position in the global landscape.
Asia Pacific
Asia Pacific dominates with the largest 45% share in 2024, driven by high consumption in China, Japan, South Korea, and India. Rising disposable incomes, urbanization, and beauty-conscious populations fuel strong demand for sustainable cosmetic solutions. Multinational and local brands actively promote natural hair care and skincare products, boosting adoption of biobased polymers. Revenues are forecast to grow from USD 3,297.57 million in 2024 to USD 5,508.92 million by 2032, reflecting the highest CAGR of 6.2%. The region’s fast growth cements its role as the global demand hub.
Latin America
Latin America captures a 4% share in 2024, led by Brazil and Argentina’s thriving personal care sectors. Growing awareness of eco-friendly cosmetics and the expansion of local natural brands support demand. Rising middle-class spending on premium and organic products further accelerates growth. The market is projected to expand from USD 321.90 million in 2024 to USD 446.23 million by 2032, with a CAGR of 3.8%. Although smaller in size, the region presents long-term opportunities for global suppliers targeting sustainability-focused consumers.
Middle East
The Middle East represents a 2% share in 2024, with growth centered in GCC countries and Turkey. Rising investments in beauty retail, particularly in luxury and halal-certified products, drive adoption of biobased polymers. Demand is further supported by growing consumer preference for high-quality, sustainable formulations. The market is expected to advance from USD 164.58 million in 2024 to USD 213.85 million by 2032, growing at a CAGR of 2.9%. While niche, the segment benefits from premium cosmetic trends and regulatory pushes for sustainability.
Africa
Africa holds a modest 2% share in 2024, with South Africa and Egypt driving regional demand. Increasing awareness of natural personal care products and gradual expansion of cosmetic retail channels foster adoption. Limited disposable income and high price sensitivity, however, constrain faster growth. Revenues are set to increase from USD 102.59 million in 2024 to USD 122.09 million by 2032, reflecting the slowest CAGR of 1.8%. Despite challenges, Africa presents emerging opportunities as urbanization and consumer education gradually increase demand for biobased cosmetic products.
Market Segmentations:
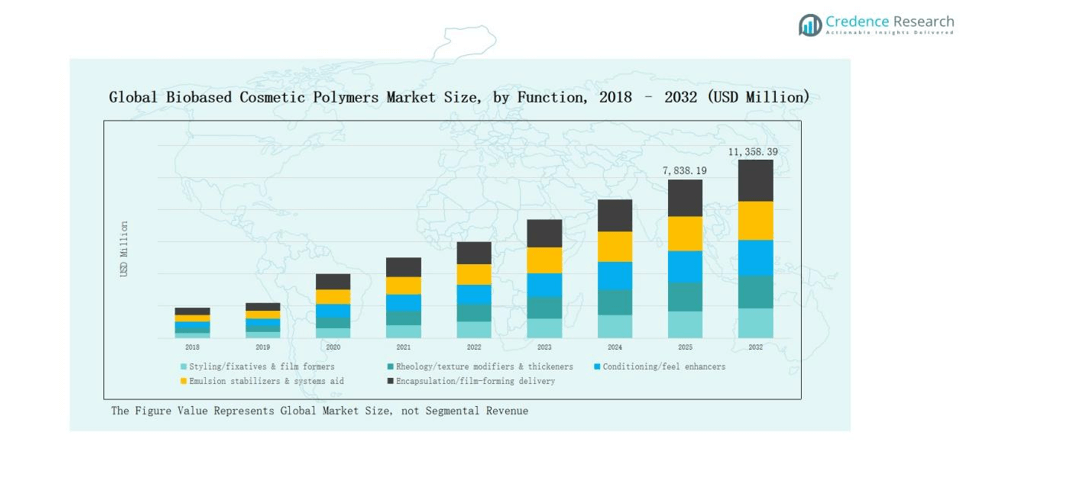
By Function
- Styling/fixatives & film formers
- Rheology/texture modifiers & thickeners
- Conditioning/feel enhancers
- Emulsion stabilizers & systems aid
- Encapsulation/film-forming delivery
By Chemistry/Origin
- Polysaccharides
- Chitosan & chitin-glucan
- Fermentation biopolymers
- Bio-based specialty polyesters/others
By Application
- Hair care
- Skin care
- Color cosmetics
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Competitive Landscape
The Global Biobased Cosmetic Polymers Market is characterized by strong competition among multinational chemical companies, specialized biopolymer producers, and ingredient suppliers focused on sustainable innovation. Leading players such as BASF SE, Dow, Solvay, Ashland, Lubrizol, Evonik, dsm-firmenich, Givaudan Active Beauty, Croda, and Clariant dominate the landscape with extensive product portfolios and global distribution networks. These companies invest heavily in R&D to develop high-performance biopolymers that enhance texture, stability, and delivery efficiency in cosmetics while meeting strict sustainability and regulatory standards. Strategic collaborations with cosmetic brands and biotechnology firms drive innovation in polysaccharides, chitosan derivatives, and fermentation-based polymers. Niche players like CP Kelco, Gelymar, KitoZyme, and EcoSynthetix focus on specialized offerings such as algae-derived and plant-based polymers, strengthening their positions in natural product segments. The competitive environment emphasizes product differentiation, eco-certifications, and traceability, with companies leveraging clean beauty trends and rising demand in Asia Pacific to expand market share and secure long-term growth.
Key Players
- BASF SE
- Dow
- Solvay
- Ashland
- Lubrizol
- Evonik
- dsm-firmenich
- Givaudan Active Beauty
- Croda
- Nouryon
- CP Kelco
- Gelymar
- KitoZyme
- EcoSynthetix
- Clariant
Recent Developments
- In June 2023, Solvay SA introduced Naternal, a new line of bio-based and biodegradable polymers tailored for hair and skin care applications.
- In April 2025, BASF launched Verdessence® Maize, a new natural-based styling polymer derived from hydrolyzed corn starch, offering biodegradable alternatives for personal care products.
- In June 2025, Dongsung Chemical, in partnership with Cosmax, commercialized a bio-based hot melt adhesive incorporating biodegradable bioplastic PHA for cosmetic packaging, marking a significant sustainability advancement.
- In April 2025, CovationBio introduced a bio-based alternative to PTMEG at Chinaplas 2025. The new polymer offers drop-in performance, lower emissions, and supports high-performance applications.
Report Coverage
The research report offers an in-depth analysis based on Function, Chemistry/Origin, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for sustainable cosmetic ingredients will continue to strengthen across global markets.
- Biopolymer innovations will improve texture, stability, and functional performance in formulations.
- Clean beauty trends will drive higher adoption of natural and biodegradable polymers.
- Asia Pacific will remain the largest growth hub with expanding consumer bases.
- Partnerships between chemical firms and cosmetic brands will accelerate new product launches.
- Regulatory pressures will encourage faster replacement of synthetic polymers with natural alternatives.
- Premium and luxury cosmetics will increasingly feature biobased polymer solutions.
- Supply chain optimization will play a critical role in cost competitiveness.
- Emerging markets in Latin America and Africa will create untapped opportunities.
- Companies will focus on eco-certifications and transparent sourcing to build consumer trust.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Biobased Cosmetic Polymers Market, and what is its projected size in 2032?
Which Global Biobased Cosmetic Polymers Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Biobased Cosmetic Polymers Market?
Who are the leading companies in the Global Biobased Cosmetic Polymers Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Biobased Cosmetic Polymers Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Biobased Cosmetic Polymers Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 7,209.87 million → forecast year: USD 11,358.39 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Biobased Cosmetic Polymers Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Biobased Cosmetic Polymers Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Biobased Cosmetic Polymers Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Biobased Cosmetic Polymers Market Drivers
- 3.3 Biobased Cosmetic Polymers Market Restraints & Challenges
- 3.4 Biobased Cosmetic Polymers Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Biobased Cosmetic Polymers Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Biobased Cosmetic Polymers Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Biobased Cosmetic Polymers category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Biobased Cosmetic Polymers Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Biobased Cosmetic Polymers Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Biobased Cosmetic Polymers market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Biobased Cosmetic Polymers Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Biobased Cosmetic Polymers Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Biobased Cosmetic Polymers Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Biobased Cosmetic Polymers (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Biobased Cosmetic Polymers Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Biobased Cosmetic Polymers Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Biobased Cosmetic Polymers Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Biobased Cosmetic Polymers Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Biobased Cosmetic Polymers Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Biobased Cosmetic Polymers Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Biobased Cosmetic Polymers Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Biobased Cosmetic Polymers Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Biobased Cosmetic Polymers Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
