
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Implant Biomaterials Market Size 2024 | USD 118,310 million |
| Implant Biomaterials Market , CAGR | 10.1% |
| Implant Biomaterials Market Size 2032 | USD 255,458.3 million |
Market Overview:
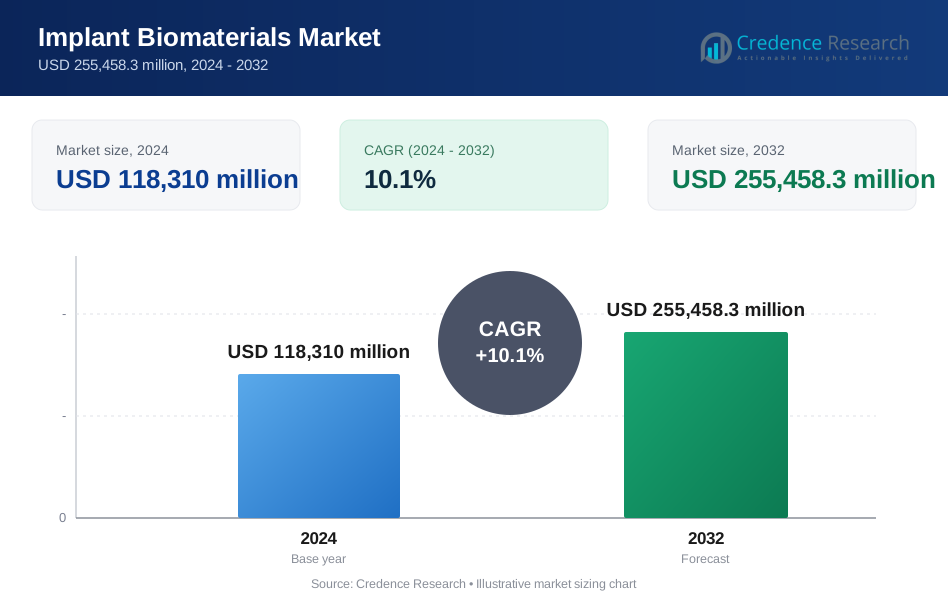
The global implant biomaterials market, valued at approximately USD 118,310 million in 2024, is projected to grow to USD 255,458.3 million by 2032, expanding at a compound annual growth rate (CAGR) of 10.1% over the forecast period. Implant biomaterials, which include metals, polymers, ceramics, and composites, are used extensively across orthopaedic, dental, and cardiovascular applications. These materials are designed to support, enhance, or replace biological structures, making them crucial in medical advancements for improving patient outcomes. The market’s growth reflects an increasing demand for durable and biocompatible materials in medical implants, driven by advancements in healthcare and an aging global population.
Key drivers of growth in the implant biomaterials market include the rising incidence of chronic diseases, such as osteoporosis and cardiovascular conditions, which increase the need for implants. Additionally, advancements in biomaterial technology are enhancing implant durability, biocompatibility, and functionality, encouraging broader adoption. The demand for minimally invasive procedures and the development of bioactive materials further support market growth. Innovations, such as 3D-printed implants and biodegradable materials, are transforming implant applications, providing patients with customized and natural integration options. Increasing healthcare expenditure, combined with supportive government policies in many regions, continues to bolster the market’s expansion.
Regionally, North America holds the largest share of the implant biomaterials market, driven by high healthcare spending, advanced medical infrastructure, and a large number of market-leading manufacturers. The United States, in particular, supports market growth through its strong demand for orthopaedic and dental implants, as well as a focus on innovation in biomaterial technology. Europe follows closely, with substantial growth supported by its aging population and regulatory initiatives that promote high-quality standards in implantable biomaterials. The Asia-Pacific region is expected to experience the highest growth rate, due to its expanding healthcare sector, increasing awareness of medical implants, and rising investments in medical infrastructure in countries like China and India. Latin America and the Middle East & Africa are witnessing moderate growth, propelled by improving healthcare systems and a growing awareness of advanced implant treatments.
Market Drivers:
Increasing Prevalence of Chronic Diseases and Aging Population:
The growing incidence of chronic conditions, such as osteoporosis, cardiovascular diseases, and arthritis, is significantly driving demand for implant biomaterials. According to the World Health Organization (WHO), approximately 20% of the global population will be aged 60 or above by 2050, highlighting a rise in age-related degenerative diseases. As the elderly are particularly susceptible to conditions requiring implants, this demographic shift drives the need for orthopedic, cardiovascular, and dental implants. For instance, in the United States alone, more than 1 million hip and knee replacements are performed each year, creating substantial demand for durable and biocompatible biomaterials.
Advancements in Biomaterial Technology:
Ongoing innovation in biomaterials is enhancing implant durability, biocompatibility, and functionality, broadening their applications in medicine. Technological advancements, such as 3D printing, are enabling manufacturers to produce patient-specific implants with complex structures that offer better integration and reduced rejection rates. For example, Stryker Corporation utilizes 3D printing to create customized orthopedic implants, allowing for precise fitting and improved recovery outcomes. Additionally, the development of bioactive and bioresorbable materials is providing patients with implants that naturally integrate with or dissolve in the body, minimizing long-term complications and surgical follow-ups.
Growing Demand for Minimally Invasive Procedures:
The shift towards minimally invasive procedures is fueling demand for advanced implant biomaterials that support easier, faster, and safer implantations. The American Hospital Association (AHA) reports a 10% annual increase in minimally invasive surgeries over traditional methods. Implant biomaterials that allow for smaller incisions and quicker recovery times, such as titanium alloys and polymer-based materials, are becoming highly sought after in orthopedic and dental applications. Companies like Zimmer Biomet focus on developing biomaterials suited for minimally invasive techniques, providing options that offer both strength and flexibility for complex procedures.
Government Support and Rising Healthcare Expenditure:
Government initiatives and increasing healthcare expenditures worldwide are supporting the growth of the implant biomaterials market. Many governments are investing in healthcare infrastructure, with the U.S. Centers for Medicare & Medicaid Services (CMS) projecting healthcare spending to grow by 5.4% annually. Additionally, regulatory bodies such as the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA) are setting stringent standards for biomaterial quality and safety, encouraging companies to innovate and maintain high standards. This regulatory support, combined with increased spending, makes advanced implant treatments more accessible, expanding market opportunities for biomaterial providers.
Market Trends:
Growth in 3D-Printed Implants:
3D printing technology is transforming the implant biomaterials market, allowing for the creation of custom, patient-specific implants with high precision. According to a report by the American Society of Mechanical Engineers, the global medical 3D printing market is projected to grow by 15% annually. Companies like Johnson & Johnson and Stryker are leading the adoption of 3D printing, developing implants tailored to patients’ unique anatomy. For instance, Stryker’s Tritanium implants are created using 3D printing to mimic the porosity of human bone, improving osseointegration and reducing the risk of rejection.
Increasing Use of Bioactive and Biodegradable Materials:
Bioactive and biodegradable materials are seeing rising demand due to their ability to integrate seamlessly into the body and reduce long-term complications. These materials help promote cell growth and, in some cases, dissolve over time, eliminating the need for additional surgeries. According to the National Institutes of Health (NIH), bioactive materials improve healing rates by up to 30%. For example, Zimmer Biomet has developed a bioresorbable scaffold material for orthopedic applications, enabling the body to gradually replace the scaffold with natural tissue.
Advancements in Surface Modification for Enhanced Biocompatibility:
Surface modification techniques are gaining traction in the implant biomaterials market, enhancing the interaction between implants and biological tissues. Surface treatments such as coating with calcium phosphates or plasma spraying improve biocompatibility, leading to better integration with bone or soft tissue. The International Journal of Biomaterials notes that surface-modified implants show a 20% increase in patient recovery rates. Companies like Medtronic use surface modification technologies on their spinal implants to improve integration and minimize complications related to implant rejection.
Rise of Hybrid Biomaterials for Improved Performance:
Hybrid biomaterials, combining properties of multiple materials, are emerging as a solution for implants that require a balance of strength, flexibility, and biocompatibility. These hybrid materials integrate metals, polymers, and ceramics to enhance durability while reducing the risk of wear and corrosion. For instance, DePuy Synthes, a subsidiary of Johnson & Johnson, is developing hybrid implants for joint replacements that combine ceramic and metal components for enhanced resilience and long-term performance. This trend addresses the need for implants that can withstand stress over time, especially in orthopedic applications.
Market Challenges Analysis:
High Costs of Advanced Biomaterials:
The development and manufacturing of advanced implant biomaterials come with significant costs, limiting access to these solutions, particularly in developing regions. High-grade biomaterials like titanium alloys, bioresorbable polymers, and ceramic composites require specialized production techniques, raising overall expenses for both manufacturers and patients. The Centers for Medicare & Medicaid Services (CMS) highlights that these costs often result in limited insurance coverage for some advanced implants, making them less accessible for patients outside high-income regions. This financial barrier restricts the broader adoption of premium biomaterial solutions.
Stringent Regulatory Requirements:
The implant biomaterials market is subject to rigorous regulatory requirements to ensure safety and biocompatibility, particularly due to the critical nature of implant applications. The U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA) impose strict guidelines for biomaterial testing, clinical trials, and quality assurance, which can delay product development and increase costs. Compliance with these standards requires significant investment in research, testing, and documentation, creating obstacles for new entrants and smaller companies. The regulatory process also extends time-to-market, limiting the pace of innovation and adoption.
Risk of Biocompatibility Issues and Complications:
Despite advancements in biomaterials, challenges in biocompatibility persist, as some materials can trigger adverse immune responses or tissue rejection. Variability in patients’ biological responses to materials like metals and polymers poses a significant challenge, particularly in long-term applications. The World Health Organization (WHO) notes that approximately 5-10% of orthopedic implants result in complications, often due to compatibility issues. This risk requires ongoing research into material properties, increasing development timelines and expenses.
Limited Infrastructure and Skilled Workforce:
The production of specialized biomaterials demands advanced manufacturing infrastructure and skilled technicians with expertise in biomaterial science and implant technology. In regions lacking this infrastructure, companies face difficulties in producing and delivering high-quality biomaterials. Furthermore, training requirements for healthcare providers who manage implant procedures are high, as the effectiveness of implant biomaterials often depends on precise handling and implantation techniques. This gap in skilled resources can restrict the expansion and application of implant biomaterials, particularly in emerging markets.
Market Segmentation Analysis:
By Type
The implant biomaterials market is segmented by type into metals, polymers, ceramics, and composites. Metals, including titanium and stainless steel, hold a significant share due to their strength and durability, making them ideal for load-bearing implants like hip and knee replacements. Polymers are also widely used for their flexibility and compatibility in applications such as spinal and dental implants. Ceramics, valued for their biocompatibility and resistance to wear, are gaining traction in orthopedic and dental implants, while composites, which combine the properties of multiple materials, are emerging as high-performance options for implants requiring both strength and biocompatibility.
By Technology
The market is further segmented by technology into 3D printing, surface modification, and biomimetic approaches. 3D printing technology is rapidly expanding within the biomaterials sector, enabling patient-specific implant designs that improve fit and reduce recovery times. Surface modification, which enhances biocompatibility through coatings or treatments, is increasingly applied in orthopedic and dental implants. Biomimetic technologies that mimic natural tissues are also advancing, offering promising applications in bone and cartilage replacement.
By End User
Key end-user segments include hospitals, specialty clinics, and research institutes. Hospitals represent the largest segment due to the high volume of implant procedures, particularly in orthopedic and cardiovascular applications. Specialty clinics, focusing on dental and spinal implants, are also significant users of biomaterials. Research institutes contribute to market growth through biomaterial innovation, testing, and development, driven by partnerships with manufacturers seeking advanced solutions. This diverse end-user base highlights the broad applicability of biomaterials across multiple healthcare settings.
Segmentations:
By Product
- Metals and Metal Alloys
- Synthetic Polymers
- Ceramics
- Natural Biomaterials
- Composites
By Application
- Cardiovascular
- Orthopedic Application
- Dental
- Plastic Surgery
- Wound Healing
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest market share, accounting for approximately 35% of the global implant biomaterials market. The region’s dominance is attributed to its advanced healthcare infrastructure, high healthcare spending, and a strong presence of key market players, particularly in the United States. High demand for orthopedic, dental, and cardiovascular implants drives significant consumption of biomaterials in this region. Regulatory bodies such as the U.S. Food and Drug Administration (FDA) maintain stringent quality and safety standards, encouraging manufacturers to prioritize advanced, biocompatible materials. Canada also contributes to the market’s growth, supported by government investments in healthcare and a rising demand for minimally invasive procedures.
Europe
Europe accounts for around 30% of the global market, driven by an aging population, a high incidence of chronic diseases, and supportive regulatory frameworks. Key countries like Germany, the United Kingdom, and France lead in adopting advanced biomaterials, particularly for orthopedic and dental implants. The European Medicines Agency (EMA) and various national health authorities enforce rigorous regulations, ensuring high standards in biomaterials production and application. Additionally, Europe’s focus on research and development in biomaterial technology fosters innovation, with companies investing heavily in bioactive and biodegradable options to meet the growing demand for sustainable solutions.
Asia-Pacific
Asia-Pacific is the fastest-growing region in the implant biomaterials market, currently holding approximately 20% of the market share. Rapidly expanding healthcare infrastructure, increasing awareness of implant treatments, and a rising incidence of chronic diseases contribute to this growth. Countries like China, Japan, and India are investing significantly in healthcare advancements, supporting demand for high-quality biomaterials. Japan’s focus on innovative medical technologies, coupled with China’s large patient population, further bolsters the market. Additionally, government initiatives across the region to improve healthcare access are expanding biomaterial usage, particularly in orthopedic and cardiovascular implants.
Latin America
Latin America represents about 8% of the market, with moderate but steady growth. Brazil and Mexico are the primary markets, supported by increasing healthcare investments and rising awareness of advanced implant options. Although the region faces challenges in regulatory alignment and infrastructure, its growing middle class and expanding healthcare sector are driving demand for implant biomaterials. Government support for healthcare improvements and the expansion of private healthcare providers contribute to the market’s development.
Middle East & Africa
The Middle East & Africa holds roughly 7% of the global market, with gradual growth driven by investments in healthcare infrastructure and rising demand for quality medical treatments. Countries like the United Arab Emirates and Saudi Arabia lead in adoption, supported by government initiatives to advance healthcare capabilities. While this region currently holds a smaller share, improving access to healthcare and the rising prevalence of chronic conditions are expected to contribute to increased demand for implant biomaterials over time.
Key Player Analysis:
- BASF SE
- Carpenter Technology Corporation
- Celanese Corporation
- CeramTec GmbH
- Corbion NV
- Covestro AG
- DSM
- Evonik Industries AG
- Mitsubishi Chemical Group Corporation
- Victrex Plc
Competitive Analysis:
The implant biomaterials market is competitive, led by prominent players such as BASF SE, DSM, and Evonik Industries AG, known for their advanced material technologies and global presence. These companies hold significant shares due to their extensive R&D capabilities and diverse portfolios, covering materials like polymers, metals, and ceramics tailored for various implant applications. Companies such as Carpenter Technology Corporation and Victrex Plc focus on high-performance metal and polymer biomaterials, particularly for orthopedic and dental implants, leveraging strong expertise in material science. Meanwhile, specialized firms like CeramTec GmbH and Corbion NV emphasize innovative bioactive and bioresorbable materials, meeting growing demand for implants that integrate naturally with human tissue. The competitive landscape is shaped by technological advancements, regulatory compliance, and a strong push toward biocompatible, durable, and customizable materials, with each company aiming to enhance implant safety and functionality through continuous innovation and strategic partnerships.
Recent Developments:
- Evonik Industries AG introduced VESTAKEEP® i4 3DF, the world's first implant-grade 3D-printable PEEK filament, designed for customized, long-term medical applications.
- Victrex plc launched PEEK-OPTIMA™ AM Filament, an implantable PEEK polymer optimized for additive manufacturing, expanding their portfolio of biocompatible polymers.
- DSM Biomedical introduced a sustainability initiative for their Dyneema Purity® UHMWPE medical-grade fiber, aiming to reduce environmental impact in medical applications.
- Evonik Industries AG developed VESTAKEEP® iC4800 3DF, an osteoconductive PEEK filament that enhances fusion between bone and implants, suitable for additive manufacturing technologies.
Market Concentration & Characteristics:
The implant biomaterials market demonstrates moderate to high concentration, with major players like BASF SE, DSM, and Evonik Industries AG leading through their advanced product portfolios and strong global presence. These companies leverage substantial R&D investments to develop biocompatible and durable materials tailored for various implant applications, such as orthopedic, dental, and cardiovascular implants. Specialized firms, including CeramTec GmbH and Victrex Plc, add to the competitive landscape by focusing on high-performance ceramics and polymers that enhance patient outcomes. The market is characterized by a strong emphasis on innovation, with growing trends in 3D-printable and bioresorbable materials that support customization and natural tissue integration. Additionally, strict regulatory requirements for biocompatibility and quality drive companies to prioritize safe, long-lasting materials. This dynamic foster continuous product development as companies strive to meet increasing demand for advanced, sustainable biomaterials in the healthcare industry.
Report Coverage:
The research report offers an in-depth analysis based on Product, Application, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for implant biomaterials will grow as the aging global population drives the need for orthopedic, dental, and cardiovascular implants.
- Advancements in 3D printing will enable more customized, patient-specific implants, enhancing fit and reducing recovery times.
- Bioactive and bioresorbable materials will gain popularity for their ability to integrate with or dissolve into the body, reducing the need for secondary surgeries.
- Hybrid biomaterials combining metals, ceramics, and polymers will offer enhanced strength, flexibility, and biocompatibility, addressing complex surgical needs.
- The push for sustainability will encourage development of eco-friendly biomaterials, with companies focusing on reducing environmental impact in production processes.
- Emerging markets in Asia-Pacific and Latin America will see higher adoption rates as healthcare infrastructure expands and awareness of implant treatments increases.
- Regulatory frameworks will continue to evolve, with more stringent standards for biocompatibility, encouraging innovation and high-quality material production.
- Increasing healthcare expenditure worldwide will improve accessibility to advanced biomaterials, especially in developed countries.
- Collaboration between medical device companies and material scientists will drive faster innovations, bringing advanced biomaterials to market more efficiently.
- Digital technologies, including AI and machine learning, will enhance biomaterial design and application, supporting precision in implant engineering and patient outcomes.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Prevalence of Chronic Diseases and Aging Population
The rising incidence of chronic conditions such as osteoporosis, cardiovascular diseases, and arthritis, coupled with a growing elderly population, is driving demand for implant biomaterials used in orthopedic, dental, and cardiovascular implants.
Advancements in Biomaterial Technology
Innovations such as 3D printing, bioactive, and bioresorbable materials are enhancing implant durability, biocompatibility, and customization, making implants safer and more effective, and expanding their use in complex medical procedures.
Growing Demand for Minimally Invasive Procedures
The shift toward minimally invasive surgeries is increasing the need for advanced biomaterials that enable smaller incisions, faster recovery, and reduced complications, particularly in orthopedic and dental applications.
Government Support and Rising Healthcare Expenditure
Increased healthcare spending and supportive government policies are improving access to advanced implant treatments, while stringent regulatory standards are encouraging the development of high-quality, safe biomaterials.
Emergence of Hybrid and Sustainable Biomaterials
The development of hybrid biomaterials combining metals, ceramics, and polymers, as well as a focus on eco-friendly production, is meeting the demand for implants that offer superior performance and reduced environmental impact.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Implant Biomaterials Market?
What factors are driving the growth of the Implant Biomaterials Market?
What are some challenges faced by the Implant Biomaterials Market?
Who are the major players in the Implant Biomaterials Market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Metals and Metal Alloys
- 1.2.2 Synthetic Polymers
- 1.2.3 Ceramics
- 1.2.4 Natural Biomaterials
- 1.2.5 Composites
- 1.3 By End User
- 1.3.1 Hospitals
- 1.3.2 Specialty Clinics
- 1.3.3 Research Institutes
- 1.4 By Technology
- 1.4.1 3D Printing
- 1.4.2 Surface Modification
- 1.4.3 Biomimetic Approaches
- 1.5 By Application
- 1.5.1 Cardiovascular
- 1.5.2 Orthopedic Application
- 1.5.3 Dental
- 1.5.4 Plastic Surgery
- 1.5.5 Wound Healing
- 1.5.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 118,310 million → 2032: USD 255,458.3 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Implant Biomaterials Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Implant Biomaterials Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Implant Biomaterials Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Implant Biomaterials Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Implant Biomaterials Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Implant Biomaterials Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Implant Biomaterials Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Implant Biomaterials Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 118,310 million → 2032: USD 255,458.3 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Implant Biomaterials Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Metals and Metal Alloys
- 12.3.7.2 Synthetic Polymers
- 12.3.7.3 Ceramics
- 12.3.7.4 Natural Biomaterials
- 12.3.7.5 Composites
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hospitals
- 12.4.7.2 Specialty Clinics
- 12.4.7.3 Research Institutes
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 3D Printing
- 12.5.7.2 Surface Modification
- 12.5.7.3 Biomimetic Approaches
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Cardiovascular
- 12.6.7.2 Orthopedic Application
- 12.6.7.3 Dental
- 12.6.7.4 Plastic Surgery
- 12.6.7.5 Wound Healing
- 12.6.7.6 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Implant Biomaterials End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Implant Biomaterials Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Implant Biomaterials Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Implant Biomaterials Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 BASF SE
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Carpenter Technology Corporation
- 18.4 Celanese Corporation
- 18.5 CeramTec GmbH
- 18.6 Corbion NV
- 18.7 Covestro AG
- 18.8 DSM
- 18.9 Evonik Industries AG
- 18.10 Mitsubishi Chemical Group Corporation
- 18.11 Victrex Plc
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

