
Biorationals Market Overview
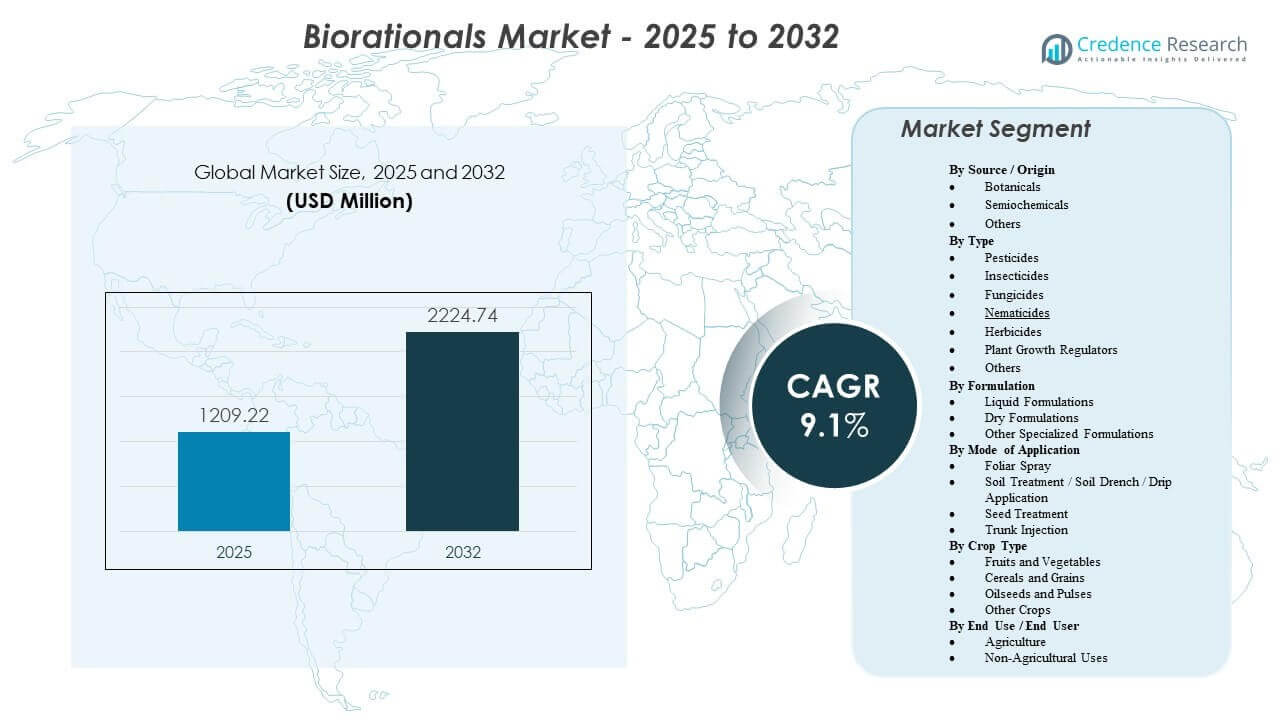
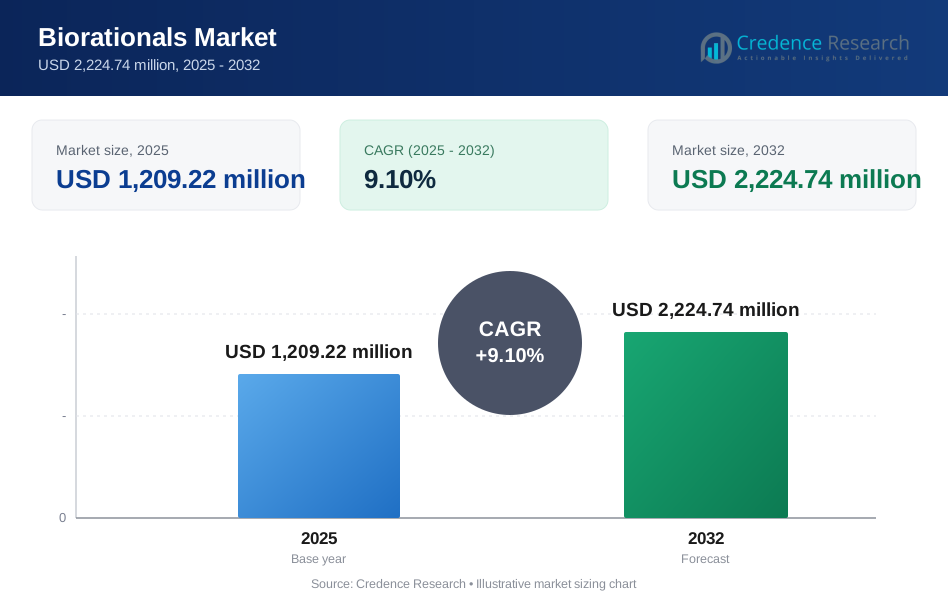
The global Biorationals Market market size was estimated at USD 1,209.22 million in 2025 and is expected to reach USD 2,224.74 million by 2032, growing at a CAGR of 9.1% from 2025 to 2032, supported by the shift toward lower-residue, safer crop protection solutions as growers balance pest pressure with tightening regulatory limits and buyer requirements on chemical residues. Demand remains strongest in crop systems where quality outcomes and compliance risks directly impact realized pricing and export access.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Biorationals Market Size 2025 | USD 1,209.22 million |
| Biorationals Market, CAGR | 9.1% |
| Biorationals Market Size 2032 | USD 2,224.74 million |
Key Market Trends & Insights
- The market is projected to expand from USD 1,209.22 million (2025) to USD 2,224.74 million (2032) at a 9.1% CAGR (2025–2032).
- North America accounted for 40% of global revenue in 2025, reflecting higher adoption of integrated pest management and premium crop protection programs.
- Botanicals held 43% share in 2025, supported by broader acceptance of plant-derived actives in residue-sensitive crop programs.
- Fruits and Vegetables captured 39% share in 2025, driven by intensive pest/disease cycles and high value-at-risk per hectare.
- Within product-type usage, Insecticides represented 40% of revenue contribution, indicating strong demand for targeted pest control in high-frequency application programs.
Biorationals Market Segment Analysis
Biorationals are increasingly integrated into grower programs where efficacy, residue compliance, and resistance management must be balanced within a single season. Adoption is typically higher in specialty crops and controlled production systems where quality parameters, market access standards, and re-entry interval constraints influence input selection. Buyers often evaluate biorationals based on fit within existing spray schedules, tank-mix compatibility, consistency across weather conditions, and supplier support for field performance.
Across regions, uptake tends to track regulatory direction, retailer and exporter residue standards, and the availability of technical advisory networks that support biological/biorational deployment. As portfolios mature, suppliers emphasize differentiated positioning by pest/disease target, crop fit, and performance under IPM programs, rather than direct one-to-one substitution for conventional chemistries.
By Source / Origin Insights
Botanicals accounted for the largest share of 43% in 2025. Plant-derived actives align well with residue-sensitive crop programs and support grower needs to maintain compliance with buyer standards. Broader availability of standardized extracts and improved formulation technologies has increased consistency in field use. Adoption also benefits from compatibility with integrated pest management programs, where botanicals can be rotated with other tools to reduce resistance pressure.
By Type Insights
Insecticides accounted for the largest share of 40% in 2025. Insect pressure remains a recurring and visible yield-risk driver, especially in horticulture and other intensive systems where timely control protects both quality and marketable yield. Bio-insecticide solutions are often selected for targeted activity, shorter pre-harvest intervals, and fit with resistance-management strategies. Demand also rises where conventional chemistries face restrictions or declining efficacy in certain pest complexes.
By Formulation Insights
Liquid formulations often gain preference in programs that rely on foliar spraying and tank-mix flexibility, supporting rapid adoption where ease of application matters. Dry formats can be selected for stability, storage, and logistics advantages in certain climates and distribution settings. Formulation selection is also shaped by the sensitivity of biological actives to temperature, UV exposure, and handling practices, which influences product performance at the farm level.
By Mode of Application Insights
Foliar spray remains the most common route in many crop protection programs because it fits established equipment and scheduling practices. Soil or drip-based approaches are used where root-zone protection and early-season crop establishment are priorities. Seed treatment is adopted where precision dosing and early protection can be delivered efficiently, though it depends on active stability and compatibility with seed handling processes.
By Crop Type Insights
Fruits and Vegetables accounted for the largest share of 39% in 2025. These crops face frequent pest and disease pressure, and quality specifications can be strict for both domestic retail and export channels. High crop value supports willingness to adopt higher-cost inputs when they reduce residue risk and protect marketability. Intensive production also increases the benefits of IPM-aligned tools that can be applied across multiple cycles within a season.
By End Use / End User Insights
Agriculture remains the core demand center because application volumes scale with planted area and seasonal pest cycles. Non-agricultural uses are driven by the need for safer pest control in settings where exposure concerns and environmental constraints are higher. Demand in this segment typically depends on local regulations, procurement cycles, and the availability of validated performance claims for specific pests and environments.
Biorationals Market Drivers
Regulatory Pressure And Residue Compliance Requirements
Biorationals benefit from tighter regulatory scrutiny of conventional pesticide actives and increasing attention to residue limits in food supply chains. Growers and suppliers prioritize solutions that reduce compliance risk without compromising crop quality or yield protection. Retailer and exporter requirements can influence input choices more directly in high-value crops, creating a pull for safer alternatives. This dynamic supports steady adoption, particularly where pest pressure is persistent and multiple applications are required.
- For instance, monitoring of leafy herbs in a UK program showed cyprodinil residues at less than one‑thirtieth of the legal maximum residue limit after two treatments and harvest intervals of 14–38 days, demonstrating how programs can stay comfortably within MRLs while maintaining protection.
Growth Of Integrated Pest Management And Resistance Concerns
IPM adoption continues to expand as resistance challenges reduce the effectiveness of certain conventional chemistries. Biorationals are used as rotation tools to diversify modes of action and preserve long-term control efficacy. Their compatibility with beneficial insects and targeted control profiles strengthens their role in IPM-based programs. Growers increasingly evaluate products on program fit and season-long outcomes rather than single-application performance alone.
Expansion In High-Value Horticulture And Specialty Crops
Fruits and vegetables represent a large share of demand because quality outcomes and marketability are tightly linked to pest and disease management. High value-at-risk supports investment in advanced crop protection inputs, especially in export-oriented production. Shorter harvest windows and multiple crop cycles also increase the need for solutions that meet residue and re-entry constraints. This helps sustain recurring demand across seasons and production regions.
Advancements In Formulation And Field Performance Consistency
Improved formulation systems help address historical concerns around variability and stability in biological and biorational products. Better shelf life, handling tolerance, and application compatibility can translate into higher repeat purchase rates. Enhanced delivery mechanisms can also support performance under variable climatic conditions. These improvements reduce adoption friction and broaden use cases across more crop systems and farm sizes.
- For instance, Biotrop has reported extending the shelf life of several microbial biopesticides in its portfolio to 36 months at ambient temperature with no refrigeration requirement, a step change from the 12–18 month cold‑chain-dependent products that historically limited biological adoption in tropical markets.
Biorationals Market Challenges
Biorationals can face variability in field performance due to weather sensitivity, application timing, and local pest pressure dynamics. This can increase the burden on technical advisory and trialing before full-scale adoption, especially for large-acre crops where consistency is critical. In some regions, uneven distribution networks and limited extension support can slow penetration, even when the value proposition is clear.
Cost-per-hectare considerations remain important, particularly in price-sensitive row crops where growers benchmark inputs against established chemistries. Adoption can also be constrained by product availability, regulatory timelines for new actives, and the need for clear guidance on program integration. As portfolios expand, suppliers must also differentiate claims and provide agronomic support to sustain confidence in repeat use.
- For instance, Valent BioSciences' Delfin biopesticide cost US$602.32 per hectare in cotton bollworm trials, higher than chemical options like Chlorpyrifos at US$27.93 per hectare, influencing adoption decisions despite efficacy.
Biorationals Market Trends and Opportunities
Portfolio expansion into semiochemicals, plant growth regulators, and integrated crop health solutions continues to broaden the biorationals value proposition beyond direct pest control. Products positioned around yield quality, stress tolerance, and program compatibility can unlock incremental adoption in diverse crop systems. Increased use of decision-support tools and precision application practices also improves fit for targeted solutions.
- For instance, BASF’s biological fungicide Serifel (Bacillus amyloliquefaciens MBI 600) has been shown in company and third‑party trials to improve marketable tomato yield by 5–10% and reduce blossom‑end rot incidence by up to 20% when integrated into standard spray programs, supporting both quality and compatibility claims.
Partnership-led commercialization and distribution alliances are becoming more visible as companies scale biological and biorational platforms across geographies. This can accelerate market access and shorten time-to-scale for new products. Opportunities also rise where public and private sustainability targets encourage lower-impact inputs, creating demand pull through procurement standards and supply-chain requirements.
Regional Insights
North America
North America held 40% revenue share in 2025. Adoption is supported by broad IPM usage, strong retailer and exporter residue expectations, and greater availability of technical advisory networks that help integrate biorationals into programs. Demand remains concentrated in high-value crop production and professionalized farm operations that can trial and optimize new inputs. Supplier presence and distribution reach also remain strong, supporting faster scale-up.
Europe
Europe accounted for 25% revenue share in 2025. The region’s regulatory environment and sustainability-linked policy direction support continued switching toward lower-impact crop protection tools. Adoption is influenced by country-level crop profiles, with strong demand in horticulture and protected cultivation. Technical validation and compliance positioning remain critical purchase drivers in the region.
Asia Pacific
Asia-Pacific represented 28% revenue share in 2025. Growth is supported by intensive agriculture, rising awareness of residue management, and increasing use of modern crop protection programs in high-value production. Adoption expands as distribution networks strengthen and suppliers provide region-specific performance guidance. Market development also benefits from expanding horticulture, protected cultivation, and export-oriented crop production.
Latin America
South America held 5% revenue share in 2025. Adoption is rising where export standards, residue compliance, and resistance challenges influence grower behavior. Large-scale agriculture requires strong evidence of consistency and economic value to support broader penetration. Distribution partnerships and field trials play an important role in scaling uptake across major crop belts.
Middle East & Africa
Middle East & Africa accounted for 2% revenue share in 2025. Demand is typically concentrated in higher-value production clusters and segments where safer pest control is prioritized. Adoption depends on product availability, technical support, and regulatory frameworks that enable market entry. Growth opportunities exist as controlled-environment agriculture expands and procurement standards evolve.
Competitive Landscape
Competition is shaped by portfolio breadth, efficacy validation, and the ability to support grower outcomes through field guidance and program integration. Leading players compete through biological and biorational pipeline development, distribution reach, and differentiated positioning by crop system and target pest/disease. Partnerships and collaborations are used to accelerate discovery, improve commercialization speed, and broaden geographic coverage.
BASF SE remains a key participant in the biorationals ecosystem through its broader crop protection strategy that emphasizes integrated solutions across conventional chemistries, biologicals, and digital agronomy support. Its approach typically centers on program fit positioning biorationals to complement spray schedules, improve resistance management, and address residue-sensitive crop requirements. BASF’s progress in this space is shaped by continued portfolio enhancement, partnerships, and formulation improvements that aim to improve performance consistency under field conditions.
- BASF SE
- Bayer AG
- Syngenta AG
- UPL Limited
- FMC Corporation
- Novozymes A/S
- Sumitomo Chemical Co., Ltd.
- Valent BioSciences LLC
- Koppert Biological Systems (Koppert B.V.)
- Certis Biologicals
- Gowan Company, LLC
- BioWorks, Inc.
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Developments
- In January 2026, Koppert Biological Systems announced a high‑tech moth‑breeding facility being built in partnership with Certhon, designed to secure and scale the in‑house production of flour moths that are essential for the company’s biological insect control production chain.
- In October 2025, Sumitomo Chemical Co., Ltd. announced that Valent BioSciences LLC, MGK, and Valent North America LLC will be merged into a new unified entity, Sumitomo Biorational Company LLC, effective April 2026, creating a global Center of Excellence for biorational innovation focused on microbial and botanical solutions.
- In April 2024, Bayer AG announced plans to launch its first bioinsecticide for broad‑acre arable crops through a licensing collaboration with AlphaBio Control, further strengthening Bayer’s biologics and biocontrol offering within its Crop Science division.
- In March 2024, FMC Corporation expanded its biologicals crop protection platform in Canada by strengthening distribution of its “Biologicals by FMC” portfolio, including a suite of microbial and biostimulant products positioned as biorational tools alongside conventional chemistries for the 2025 growing seasons.
Report Scope
| Report Attribute | Details |
| Market size value in 2025 | USD 1209.22 million |
| Revenue forecast in 2032 | USD 2224.74 million |
| Growth rate (CAGR) | 9.1% (2025–2032) |
| Base year | 2025 |
| Forecast period | 2026–2032 |
| Quantitative units | USD million |
| Segments covered | By Source / Origin; By Type; By Formulation; By Mode of Application; By Crop Type; By End Use / End User; By Region |
| Regional scope | North America, Europe, Asia Pacific, South America, Middle East & Africa |
| Key companies profiled | BASF SE; Bayer AG; Syngenta AG; UPL Limited; FMC Corporation; Novozymes A/S; Sumitomo Chemical Co., Ltd.; Valent BioSciences LLC; Koppert Biological Systems (Koppert B.V.); Certis Biologicals; Gowan Company, LLC; BioWorks, Inc. |
Segmentation
BY SOURCE / ORIGIN
- Botanicals
- Semiochemicals
- Others
BY TYPE
- Pesticides
- Insecticides
- Fungicides
- Nematicides
- Herbicides
- Plant Growth Regulators
- Others
BY FORMULATION
- Liquid Formulations
- Dry Formulations
- Other Specialized Formulations
BY MODE OF APPLICATION
- Foliar Spray
- Soil Treatment / Soil Drench / Drip Application
- Seed Treatment
- Trunk Injection
BY CROP TYPE
- Fruits and Vegetables
- Cereals and Grains
- Oilseeds and Pulses
- Other Crops
BY END USE / END USER
- Agriculture
- Non-Agricultural Uses
BY REGION
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size and growth outlook for the Biorationals Market?
Which region leads the Biorationals Market in 2025?
Which segment leads the market by source/origin?
Which crop type contributes the most demand for biorationals?
Which type category is most significant in biorationals usage?
What are the main factors shaping competition in this market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Biorationals Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2025; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Biorationals Market Snapshot
- 2.1.1 Market Size – Historical (2025) & Forecast (2025-2032) (2025: USD 1,209.22 million → 2032: USD 2,224.74 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Biorationals Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2025 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2025
- 2.3.2 Top 10 Players by Volume Share – 2025
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Biorationals Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Biorationals Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Biorationals Market Drivers
- 3.3 Biorationals Market Restraints & Challenges
- 3.4 Biorationals Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Biorationals Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Biorationals Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Biorationals category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Biorationals Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Biorationals Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2025)
- 5.1.2 Global Export Volume by Country (2025)
- 5.1.3 Global Import Value by Country (2025)
- 5.1.4 Global Import Volume by Country (2025)
- 5.1.5 Net Trade Balance by Country (2025)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2025)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Biorationals market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Biorationals Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2025
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Biorationals Market Share Analysis – 2025
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2025)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Biorationals Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Biorationals (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Biorationals Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Biorationals Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2025 & 2032)
- 7.1.2 Channel Mix Evolution (2025-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Biorationals Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Biorationals Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Biorationals Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Biorationals Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Biorationals Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Biorationals Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Biorationals Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
