
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
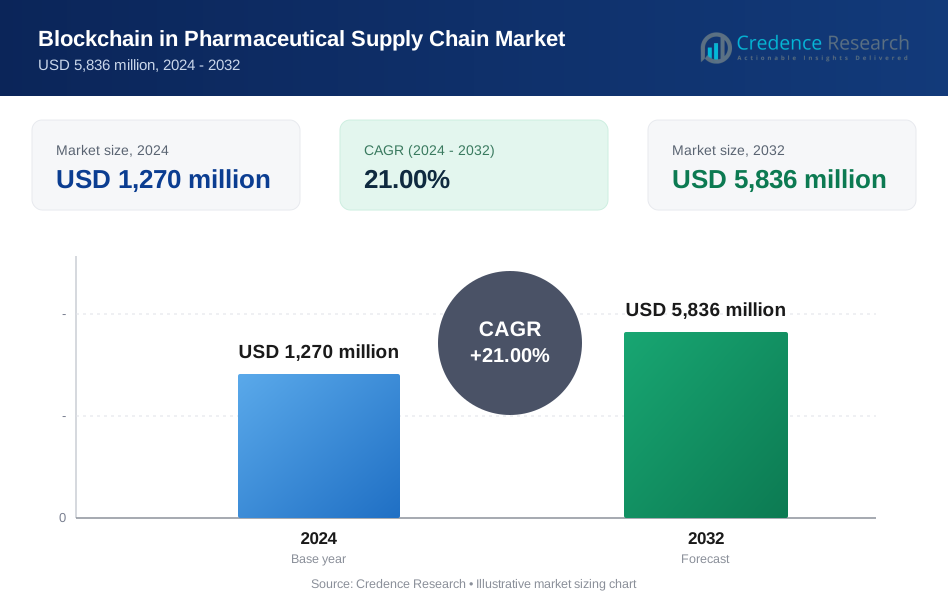
| Blockchain in Pharmaceutical Supply Chain Market Size 2024 | USD 1,270 million |
| Blockchain in Pharmaceutical Supply Chain Market, CAGR | 21% |
| Blockchain in Pharmaceutical Supply Chain Market Size 2032 | USD 5,836 million |
Market Overview:
The Blockchain in pharmaceutical supply chain market is projected to grow from USD 1,270 million in 2024 to USD 5,836 million by 2032, registering a robust CAGR of 21% during the forecast period.
The blockchain in pharmaceutical supply chain market is driven by the growing need for enhanced transparency, security, and traceability across the supply chain. Rising incidences of counterfeit drugs and regulatory mandates for drug serialization have accelerated the adoption of blockchain technology to ensure data integrity and real-time tracking. Pharmaceutical companies are increasingly leveraging blockchain to improve supply chain efficiency, reduce operational costs, and strengthen stakeholder collaboration. Additionally, the integration of IoT and AI with blockchain is creating new growth avenues, enabling automated and data-driven decision-making. The growing emphasis on patient safety and stringent global regulations further support the deployment of blockchain solutions. Key market players are focusing on strategic partnerships and pilot projects to scale blockchain implementation across various stages of drug manufacturing and distribution. With the pharmaceutical industry undergoing digital transformation, the trend toward decentralized and secure data management is expected to intensify, positioning blockchain as a critical enabler of a more resilient and transparent supply chain.
The blockchain in pharmaceutical supply chain market is experiencing strong growth across all major regions. North America, holding the largest market share, leads with robust adoption driven by strict regulations like DSCSA and high technological infrastructure, with key players such as IBM, Microsoft, and Oracle. Europe follows closely, benefiting from the EU's Falsified Medicines Directive, with prominent players like SAP SE and Tibco Software shaping the market. In Asia Pacific, the market is growing rapidly, with China and India emerging as key hubs for blockchain adoption, supported by companies like Auxesis Group and Omnichain. The Rest of the World, including Latin America, the Middle East, and Africa, is gradually adopting blockchain solutions, with emerging players such as Chainvine and Applied Blockchain offering localized solutions to address regional challenges in pharmaceutical supply chains.
Market Insights:
- The blockchain in pharmaceutical supply chain market is projected to grow from USD 1,270 million in 2024 to USD 5,836 million by 2032, with a robust CAGR of 21%.
- Rising incidences of counterfeit drugs and increasing regulatory requirements are driving the adoption of blockchain technology to ensure product traceability and data integrity.
- Integration of IoT and AI with blockchain is creating new growth avenues, enabling automated decision-making and predictive insights in supply chain management.
- North America leads the market with a 40% share in 2024, driven by stringent regulations such as DSCSA and strong technological infrastructure.
- Europe follows with a 30% market share, benefiting from the EU’s Falsified Medicines Directive and increasing blockchain adoption by pharmaceutical companies.
- Asia Pacific holds a 20% share in 2024, with rapid blockchain adoption in China and India, aimed at addressing counterfeit drugs and improving supply chain efficiency.
- The Rest of the World (Latin America, Middle East, Africa) holds a 10% market share, with gradual blockchain adoption driven by regional regulatory changes and a focus on enhancing pharmaceutical distribution.
Market Drivers:
Rising Demand for Transparency and Traceability:
One of the primary drivers of the blockchain in pharmaceutical supply chain market is the increasing demand for transparency and traceability across the entire supply chain. Counterfeit drugs continue to pose a major threat to patient safety and brand reputation, prompting stakeholders to seek robust technological solutions. For instance, Walmart, as part of the MediLedger consortium, uses blockchain to improve product traceability, especially for high-value pharmaceuticals, ensuring product authenticity and improving supply chain security. Blockchain provides a tamper-proof, immutable ledger that ensures real-time visibility of drug movement from manufacturing to distribution, enabling efficient tracking and authentication of pharmaceutical products.
Stringent Regulatory Requirements:
Global regulatory bodies are implementing stricter compliance mandates to combat counterfeit and substandard medicines. Regulations such as the Drug Supply Chain Security Act (DSCSA) in the United States and similar frameworks worldwide are pushing pharmaceutical companies to adopt technologies that ensure product authenticity and traceability. Blockchain aligns well with these regulatory requirements by offering secure, verifiable records that meet compliance standards and improve audit readiness, thus driving its adoption in the pharmaceutical supply chain.
Increasing Focus on Patient Safety:
Ensuring patient safety remains a top priority for pharmaceutical companies and healthcare providers. Blockchain technology addresses critical challenges in drug recalls, adverse event reporting, and supply chain disruptions by providing a secure, real-time record of every transaction and process. For instance, FDA DSCSA Pilot Program An FDA pilot program demonstrated that blockchain technology could expedite the drug recall process, alerting partners in as little as ten seconds, a significant improvement over the current process that can take up to 3 days. This transparency helps identify and isolate issues quickly, minimizing harm to patients and reinforcing trust in the pharmaceutical ecosystem. As awareness around patient-centric care grows, the adoption of blockchain to enhance safety protocols is expected to rise significantly.
Digital Transformation and Technological Advancements:
The pharmaceutical industry is undergoing rapid digital transformation, with an increasing shift toward integrated and data-driven supply chains. The convergence of blockchain with technologies such as artificial intelligence (AI), Internet of Things (IoT), and big data analytics is unlocking new efficiencies and automation capabilities. These innovations are enabling predictive insights, smart contracts, and real-time monitoring, further strengthening the case for blockchain as a foundational technology in modernizing pharmaceutical supply chains.
Market Trends:
Integration of Blockchain with Emerging Technologies:
A prominent trend in the blockchain in pharmaceutical supply chain market is the integration of blockchain with emerging technologies such as artificial intelligence (AI), Internet of Things (IoT), and machine learning. For instance, IBM's Blockchain Transparent Supply platform allows pharmaceutical companies to track products in real-time, significantly reducing the risk of counterfeit drugs. These combinations enhance the capabilities of blockchain by enabling real-time data analytics, predictive insights, and automated processes. IoT sensors can track temperature and handling conditions, while AI can analyze blockchain data for potential disruptions, ensuring that the supply chain remains agile and responsive.
Growing Adoption of Smart Contracts:
The use of smart contracts is gaining momentum as pharmaceutical companies seek to automate and streamline supply chain operations. These self-executing contracts, coded on blockchain platforms, automatically trigger actions when predefined conditions are met. This innovation reduces administrative overhead, minimizes human error, and accelerates transaction processing. In pharmaceutical supply chains, smart contracts are increasingly being used for automating compliance checks, payment settlements, and inventory management.
Focus on End-to-End Supply Chain Visibility:
Achieving end-to-end visibility is becoming a strategic priority for pharmaceutical firms, and blockchain is proving to be an effective enabler. Stakeholders are adopting blockchain solutions to track each stage of the supply chain-from raw material sourcing to final delivery-ensuring transparency and accountability. This comprehensive visibility not only enhances operational efficiency but also supports ethical sourcing and sustainability efforts, aligning with global demands for responsible business practices.
Collaborative Industry Initiatives and Consortia:
Another significant trend is the rise of collaborative initiatives and blockchain consortia among pharmaceutical companies, technology providers, and regulatory bodies. These partnerships aim to develop standardized blockchain frameworks and shared platforms to reduce fragmentation and facilitate interoperability. For instance, MediLedger is a consortium of leading pharmaceutical firms utilizing blockchain to enhance product verification and prevent counterfeit medications from reaching consumers. By working together, stakeholders can accelerate blockchain adoption, drive innovation, and establish industry-wide best practices that ensure the secure and efficient movement of pharmaceutical products across borders.
Market Challenges Analysis:
Lack of Standardization and Interoperability:
The lack of standardization and interoperability remains a critical challenge in the adoption of blockchain within the pharmaceutical supply chain. The supply chain comprises numerous stakeholders-manufacturers, wholesalers, regulatory authorities, logistics providers, and pharmacies-all operating on varied technological infrastructures and compliance standards. Without a unified protocol, blockchain platforms may struggle to communicate effectively, limiting the potential for seamless, real-time data sharing. This fragmentation leads to inefficiencies and hinders the development of a consistent, secure, and transparent digital record across the entire supply chain. For instance, SAP's Pharma Blockchain offers end-to-end visibility and traceability, allowing pharmaceutical companies to monitor the entire supply chain with greater transparency, ensuring better control over the distribution process so medications reach patients safely. Furthermore, global supply chains must comply with diverse regional regulations, many of which are not yet adapted to blockchain technologies. Inconsistencies in legal frameworks, data-sharing policies, and technological readiness create barriers to global interoperability. To overcome this, industry-wide collaboration is essential to establish universal standards, shared governance models, and regulatory alignment that enable scalable and cross-border blockchain implementation in the pharmaceutical domain.
High Implementation Costs and Technical Complexity:
The high cost of blockchain implementation poses another significant hurdle for pharmaceutical companies, especially small and medium-sized enterprises. Developing and deploying blockchain infrastructure involves substantial capital expenditure on network development, cybersecurity measures, integration with existing enterprise systems, and continuous maintenance. The complexity increases when trying to merge blockchain solutions with legacy IT systems that were not designed to accommodate decentralized technologies. Additionally, there is a notable skills gap; many organizations lack in-house blockchain expertise, making them reliant on external vendors, which can further increase costs. Concerns around scalability, transaction processing speeds, and energy consumption also persist, particularly for permissionless blockchain networks. Moreover, pharmaceutical data is highly sensitive, and ensuring robust data privacy and regulatory compliance within decentralized systems is a technical challenge. These factors collectively contribute to organizational hesitance and delay the transition from pilot programs to full-scale implementation. Addressing these issues requires investment in education, infrastructure subsidies, and the development of more cost-effective, scalable blockchain solutions.
Market Opportunities:
The blockchain in pharmaceutical supply chain market presents significant opportunities driven by the growing demand for more efficient, secure, and transparent operations. As the pharmaceutical industry faces increasing pressure to combat counterfeit drugs and ensure regulatory compliance, blockchain provides a robust solution for tracking and verifying products throughout the entire supply chain. The ability to create an immutable, tamper-proof record of every transaction offers a new level of accountability, reducing the risk of fraud and ensuring product authenticity. This enhanced transparency not only boosts consumer confidence but also helps companies meet stringent regulatory requirements, such as serialization mandates and product traceability regulations. As these demands continue to rise, the market is expected to see increased investment in blockchain solutions that improve both operational efficiency and compliance, opening up opportunities for technology providers to innovate and scale their offerings.
Additionally, blockchain's integration with emerging technologies like artificial intelligence (AI) and the Internet of Things (IoT) provides the opportunity to revolutionize the pharmaceutical supply chain. By combining real-time data from IoT sensors with AI-powered analytics, companies can gain actionable insights into supply chain performance, predict potential disruptions, and automate key processes. The increasing adoption of smart contracts, which facilitate automatic transactions when certain conditions are met, further streamlines operations and reduces costs. These technological advancements enable pharmaceutical companies to enhance their overall supply chain management, optimize inventory, and ensure the safety and quality of their products. As the industry moves towards digital transformation, these opportunities for innovation and collaboration will likely drive market growth, positioning blockchain as a critical enabler of future supply chain modernization.
Market Segmentation Analysis:
By Application
The blockchain in pharmaceutical supply chain market is segmented by application into product traceability, risk and compliance management, payment and settlement, and others. Product traceability dominates the segment, driven by the need for transparency and security in tracking pharmaceutical products throughout the supply chain. Risk and compliance management is also a significant focus, with blockchain ensuring regulatory adherence and reducing fraud. Payment and settlement solutions leverage blockchain to streamline transactions and reduce costs, while other applications focus on optimizing supply chain operations.
By End-User
The market is also segmented by end-user, including manufacturers, distributors, and healthcare providers. Manufacturers are the largest adopters of blockchain solutions, seeking enhanced visibility and security in product development and distribution. Distributors use blockchain to track product movements and verify authenticity, ensuring a secure supply chain. Healthcare providers benefit from blockchain by improving the management of pharmaceuticals and ensuring timely, accurate deliveries to patients, thus increasing operational efficiency and safety.
Segments:
Based on Application
- Product Traceability
- Risk & Compliance Management
- Payment & Settlement
- Others
Based on End-User
- Manufacturers
- Distributors
- Healthcare Providers
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a dominant position in the blockchain in pharmaceutical supply chain market, with a market share of 40% in 2024. This can be attributed to the region’s advanced technological infrastructure, strong regulatory frameworks, and high adoption rates of blockchain technology across various industries, including pharmaceuticals. The United States, in particular, is a key driver, with stringent regulations like the Drug Supply Chain Security Act (DSCSA) pushing pharmaceutical companies to adopt technologies that enhance product traceability and compliance. The presence of major pharmaceutical companies and technology providers further contributes to North America's leadership in this market. Additionally, the growing focus on combatting counterfeit drugs, improving supply chain efficiency, and meeting regulatory requirements supports continued blockchain adoption, positioning North America as the largest market for blockchain in pharmaceutical supply chains.
Europe
Europe is the second-largest market for blockchain in pharmaceutical supply chains, holding a market share of 30% in 2024. The region’s robust regulatory environment, particularly the EU’s Falsified Medicines Directive (FMD), mandates the use of advanced technologies for product traceability, making blockchain an attractive solution. European pharmaceutical companies are increasingly adopting blockchain for improving supply chain transparency, ensuring product authenticity, and enhancing overall operational efficiency. The region also benefits from strong collaboration between industry players, regulators, and technology providers, which accelerates the development and deployment of blockchain solutions. Countries such as Germany, the UK, and France lead the market, with significant investments in blockchain-based supply chain innovations. Europe's proactive stance on addressing counterfeit drugs and enhancing patient safety positions it for continued growth in the blockchain sector.
Asia Pacific
Asia Pacific is experiencing rapid growth in the blockchain in pharmaceutical supply chain market, with a market share of 20% in 2024. This growth is driven by the expanding pharmaceutical industry in countries such as China and India, which are key global producers and exporters of pharmaceutical products. Blockchain offers a viable solution for addressing challenges such as counterfeit drugs, supply chain inefficiencies, and regulatory compliance. Additionally, the increasing adoption of blockchain by government bodies, along with advancements in digital infrastructure, is helping fuel the market. While the region faces challenges related to regulatory consistency and technological adoption, the rapid pace of development in key countries indicates strong future potential for blockchain integration in pharmaceutical supply chains.
Rest of the World
The Rest of the World (RoW) includes regions such as Latin America, the Middle East, and Africa, collectively accounting for a market share of 10% in 2024. In these regions, blockchain adoption in the pharmaceutical supply chain is still emerging but gaining traction. The need for enhanced traceability, security, and efficiency in pharmaceutical distribution is gradually being recognized by local governments and healthcare providers. While the market in these regions is smaller compared to North America and Europe, growing investment in digital transformation and regulatory changes are expected to drive further adoption of blockchain in pharmaceutical supply chains over the coming years. The RoW market is expected to see steady growth as the industry matures and more localized solutions are developed.
Key Player Analysis:
- Omnichain
- Vechain Foundation
- SAP SE
- Auxesis Group
- IBM
- Oracle
- Tibco Software
- Applied Blockchain
- Huawei
- Chainvine
- Microsoft
- AWS
Competitive Analysis:
The blockchain in pharmaceutical supply chain market is highly competitive, with key players including IBM, Microsoft, SAP SE, Oracle, Tibco Software, Auxesis Group, Omnichain, Vechain Foundation, Chainvine, Applied Blockchain, AWS, and Huawei. These companies are leveraging their technological expertise to provide innovative blockchain solutions aimed at improving supply chain transparency, product traceability, and regulatory compliance. IBM and Microsoft lead the market with their strong technological infrastructure and extensive experience in blockchain and supply chain solutions. SAP SE and Oracle follow closely, offering integrated blockchain solutions to enhance operational efficiency and compliance. Emerging players like Auxesis Group and Omnichain focus on providing tailored solutions for specific regional markets, while Vechain Foundation and Chainvine are gaining traction with their unique blockchain platforms tailored for industries like pharmaceuticals. Applied Blockchain and AWS bring strong cloud-based solutions, while Huawei capitalizes on its expertise in connectivity and IoT to integrate blockchain into the pharmaceutical supply chain. Competitive strategies include partnerships, technological innovations, and expanding service offerings to capture market share.
Recent Developments:
- In the 2025 Gartner Magic Quadrant for Data Center Switching, Huawei has been recognized as a leader. The company is upgrading its data center network with the Xinghe Intelligent Fabric Solution, which features AI Brain, AI Connection, and AI NEs.
- In January 2025,VeChain's blockchain-powered smart contracts enhance supply chain management by improving transparency, automating compliance, and ensuring product quality.
- In November 2024, The Ethiopia Food and Drug Authority (EFDA) and Medical Value Chain announced a strategic partnership to implement a blockchain-enabled pharmaceutical track and trace system.
- In December 2024, VeChain is recognized as a blockchain technology specializing in enterprise-grade solutions, capable of hosting DeFi, DApp, and NFT ecosystems.
Market Concentration & Characteristics:
The blockchain in pharmaceutical supply chain market is characterized by a moderate level of concentration, with several key players dominating the landscape. These companies, including IBM, Microsoft, SAP SE, Oracle, and emerging players like Auxesis Group and Omnichain, lead the development of blockchain solutions tailored to the pharmaceutical sector. The market is marked by a high level of innovation and competition, with players focusing on strategic partnerships, pilot projects, and technological advancements to gain a competitive edge. Additionally, the market is shaped by increasing collaboration between technology providers and pharmaceutical companies to address key challenges such as counterfeit drugs, regulatory compliance, and supply chain inefficiencies. While large corporations control a significant portion of the market, there is ample opportunity for smaller players and startups to provide specialized, region-specific solutions. Overall, the market is evolving rapidly, driven by the growing demand for secure, transparent, and efficient supply chain management in the pharmaceutical industry.
Report Coverage:
The research report offers an in-depth analysis based on Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The blockchain in pharmaceutical supply chain market will continue to expand as the demand for transparency and traceability grows globally.
- Integration with emerging technologies such as AI, IoT, and big data analytics will drive further innovation and efficiency in pharmaceutical supply chains.
- The adoption of blockchain will increase as pharmaceutical companies seek solutions to combat counterfeit drugs and ensure product authenticity.
- Regulatory bodies will play a critical role in driving blockchain adoption through the introduction of more stringent compliance standards and mandates.
- The trend towards decentralized data management will intensify as pharmaceutical companies focus on improving security and reducing fraud.
- Collaboration between pharmaceutical companies, technology providers, and regulators will accelerate blockchain implementation across global supply chains.
- Blockchain will continue to support the digital transformation of the pharmaceutical industry by improving operational efficiency and reducing costs.
- Blockchain's role in enhancing patient safety will increase as its ability to ensure real-time tracking and quick responses to drug recalls becomes more widespread.
- Market players will focus on developing scalable and cost-effective blockchain solutions to address challenges related to implementation and technical complexity.
- Emerging regions such as Asia Pacific and Latin America will see significant growth in blockchain adoption as digital infrastructure improves and regulatory frameworks evolve.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Blockchain in Pharmaceutical Supply Chain Market?
What factors are driving the growth of the Blockchain in Pharmaceutical Supply Chain Market?
What are the key segments within the Blockchain in Pharmaceutical Supply Chain Market?
Who are the major players in the Blockchain in Pharmaceutical Supply Chain Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Blockchain in Pharmaceutical Supply Chain Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Blockchain in Pharmaceutical Supply Chain Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,270 million → 2032: USD 5,836 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Blockchain in Pharmaceutical Supply Chain Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Blockchain in Pharmaceutical Supply Chain Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Blockchain in Pharmaceutical Supply Chain Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Blockchain in Pharmaceutical Supply Chain Market Drivers
- 3.3 Blockchain in Pharmaceutical Supply Chain Market Restraints & Challenges
- 3.4 Blockchain in Pharmaceutical Supply Chain Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Blockchain in Pharmaceutical Supply Chain Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Blockchain in Pharmaceutical Supply Chain Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Blockchain in Pharmaceutical Supply Chain category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Blockchain in Pharmaceutical Supply Chain Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Blockchain in Pharmaceutical Supply Chain Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Blockchain in Pharmaceutical Supply Chain. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Blockchain in Pharmaceutical Supply Chain Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Blockchain in Pharmaceutical Supply Chain Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Blockchain in Pharmaceutical Supply Chain Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Blockchain in Pharmaceutical Supply Chain (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Blockchain in Pharmaceutical Supply Chain
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Blockchain in Pharmaceutical Supply Chain Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Blockchain in Pharmaceutical Supply Chain Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Blockchain in Pharmaceutical Supply Chain Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Blockchain in Pharmaceutical Supply Chain Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Blockchain in Pharmaceutical Supply Chain Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Blockchain in Pharmaceutical Supply Chain Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Blockchain in Pharmaceutical Supply Chain Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Blockchain in Pharmaceutical Supply Chain Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
