
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Blood Dialyzer Market Size 2024 | USD 3,663.38 Million |
| Blood Dialyzer Market, CAGR | 5.26% |
| Blood Dialyzer Market Size 2032 | USD 5,507.64 Million |
Market Overview
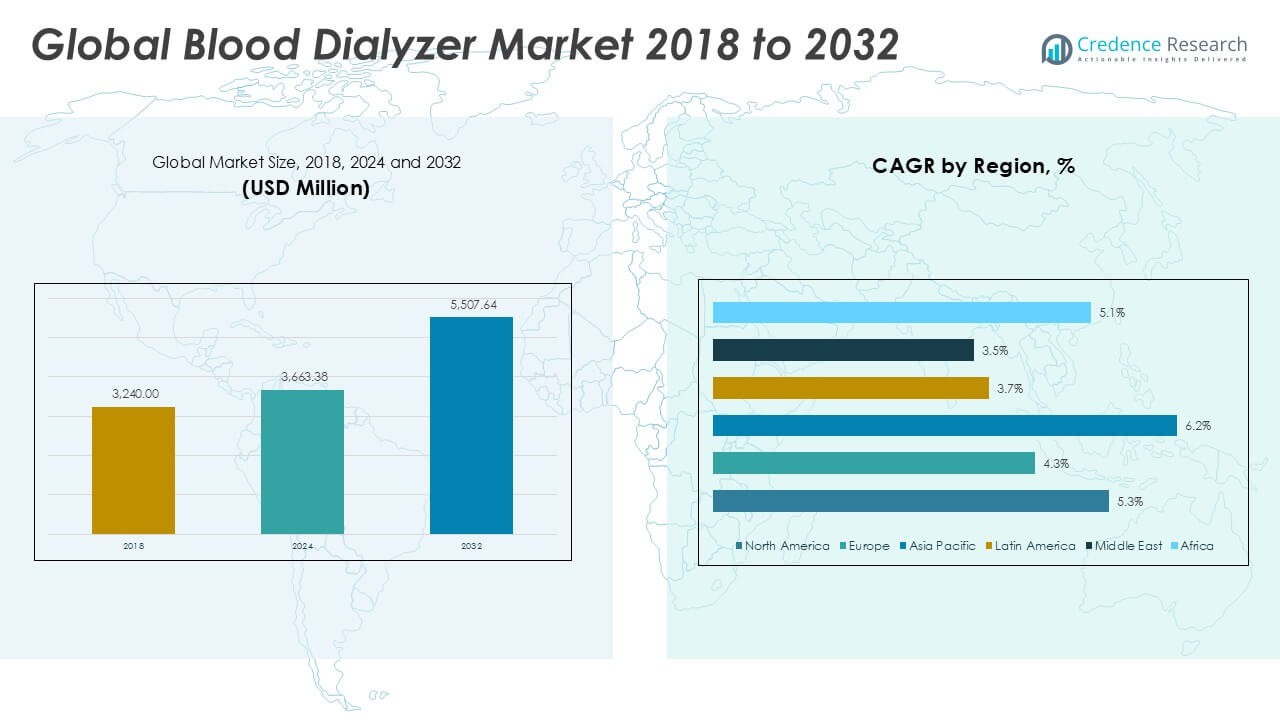
The Blood Dialyzer Market was valued at USD 3,240 million in 2018, reached USD 3,663.38 million in 2024, and is anticipated to reach USD 5,507.64 million by 2032, at a CAGR of 5.26% during the forecast period.
The Blood Dialyzer Market is primarily driven by the rising prevalence of chronic kidney diseases, increasing rates of diabetes and hypertension, and the growing geriatric population worldwide. Advancements in dialyzer membrane technology, improved biocompatibility, and the adoption of high-flux and high-efficiency dialyzers are further enhancing market growth. Healthcare infrastructure development and increased access to dialysis treatment in emerging economies are also boosting demand. However, cost constraints and reimbursement challenges may limit market expansion in certain regions. Market trends include a shift toward home-based hemodialysis, increasing demand for single-use dialyzers to reduce infection risks, and a focus on eco-friendly and sustainable products. Leading manufacturers are investing in research to enhance dialyzer performance and patient safety, while digital health integration is streamlining patient monitoring and treatment outcomes. These factors collectively support steady market expansion and innovation in the blood dialyzer segment.
The geographical analysis of the Blood Dialyzer Market highlights strong growth across North America, Europe, and Asia Pacific, driven by advanced healthcare infrastructure, rising incidence of chronic kidney disease, and growing access to dialysis services. North America, with the United States leading, continues to benefit from robust investments in technology and home-based care models. Europe sees consistent demand in countries such as Germany and the United Kingdom, supported by established renal care frameworks and innovation in medical devices. Asia Pacific experiences rapid expansion in China, Japan, and India due to improving healthcare access and increasing awareness about early diagnosis and treatment. Key players shaping the competitive landscape of the Blood Dialyzer Market include Fresenius Medical Care AG & Co. KGaA, Baxter International Inc., and Nipro Corporation, each known for their extensive product portfolios, global presence, and continuous advancements in dialysis technologies.
Market Insights
- The Blood Dialyzer Market was valued at USD 3,240 million in 2018, reached USD 3,663.38 million in 2024, and is projected to reach USD 5,507.64 million by 2032, registering a CAGR of 5.26% during the forecast period.
- Increasing prevalence of chronic kidney disease and rising rates of diabetes and hypertension remain major drivers fueling demand for blood dialyzers worldwide.
- Market growth is supported by technological advancements in dialyzer membranes, improved biocompatibility, and the development of high-efficiency products that enhance patient outcomes.
- Notable trends include a shift toward home-based dialysis, increasing adoption of single-use dialyzers to reduce infection risk, and ongoing focus on eco-friendly, sustainable product solutions.
- Key players such as Fresenius Medical Care AG & Co. KGaA, Baxter International Inc., and Nipro Corporation dominate the competitive landscape, leveraging innovation and broad distribution networks to maintain market leadership.
- Market restraints involve high treatment costs, reimbursement challenges in developing regions, and strict regulatory requirements that slow product launches and increase operational expenses.
- Regionally, North America, Europe, and Asia Pacific are the primary contributors to market growth, with rapid expansion seen in China, Japan, India, and the United States, while Latin America, the Middle East, and Africa present emerging opportunities through improving healthcare infrastructure and access.
Market Drivers
Growing Incidence of Chronic Kidney Diseases and Related Disorders Fuels Demand
The Blood Dialyzer Market benefits significantly from the rising prevalence of chronic kidney diseases, diabetes, and hypertension. These conditions continue to contribute to a larger population requiring regular dialysis, placing dialyzers at the forefront of renal care solutions. Healthcare professionals report an uptick in patients requiring long-term renal replacement therapy, which supports consistent market demand. The growing global geriatric population, which faces an elevated risk of renal impairment, further increases the need for efficient blood purification systems. Markets with aging populations experience higher demand for dialyzer products and related services. Patients increasingly rely on advanced medical devices to manage chronic health conditions, propelling steady growth for the sector. The escalating disease burden across both developed and emerging regions underscores the critical role of dialyzers in modern healthcare.
- For instance, Fresenius Medical Care treated 344,000 patients across its dialysis clinics globally in 2023, highlighting the widespread adoption of its blood dialyzer technologies.
Advances in Membrane Technology and Biocompatibility Support Innovation
Continuous improvements in dialyzer membrane technology and biocompatibility drive innovation within the Blood Dialyzer Market. Manufacturers develop high-flux and high-efficiency membranes that provide better toxin removal and reduced treatment times for patients. It enables healthcare providers to offer safer and more effective dialysis sessions, addressing the evolving needs of diverse patient populations. Medical device companies invest in research to enhance dialyzer performance, leading to safer materials and lower risks of adverse reactions. Innovations in synthetic and natural polymers help create more durable and user-friendly dialyzers, attracting both clinics and patients. Technological advancements contribute to the overall reliability of the products. These developments ensure that dialyzers remain a preferred choice for managing renal failure.
- For instance, Baxter International has shipped more than 100,000 Theranova dialyzers since its launch, with clinical evidence demonstrating significantly higher clearance rates of large middle molecules compared to standard high-flux dialyzers.
Expansion of Dialysis Infrastructure and Accessibility in Emerging Markets
The Blood Dialyzer Market gains momentum from significant investments in healthcare infrastructure, particularly in developing regions. Governments and private organizations expand dialysis centers and improve access to treatment, which increases product adoption rates. Expanded insurance coverage and public health programs enable more patients to receive regular dialysis, broadening the market base. Efforts to train medical professionals and standardize dialysis protocols further boost patient outcomes and confidence in advanced dialyzer solutions. It ensures that a larger segment of the population benefits from life-saving renal therapy. The growing focus on healthcare access continues to strengthen market fundamentals in underserved regions. Increased investment in facilities and technology helps bridge care gaps.
Rising Preference for Home-Based Dialysis and Sustainable Solutions Shapes Market Direction
Shifting patient preferences toward home-based dialysis and eco-friendly products create new opportunities in the Blood Dialyzer Market. Portable and user-friendly dialyzers make home treatment more viable, improving patient quality of life and reducing the need for frequent clinic visits. The rising demand for single-use dialyzers addresses infection control and meets stricter regulatory standards. Environmental sustainability influences product development, encouraging manufacturers to design recyclable and biodegradable components. Market leaders respond by launching green initiatives and expanding portfolios to include low-waste options. Growing awareness about infection risk and sustainability shapes procurement choices in hospitals and clinics. These shifts help the market evolve in line with changing patient and provider expectations.
Market Trends
Shift Toward Home-Based Hemodialysis and Patient-Centric Solutions Accelerates
The Blood Dialyzer Market observes a distinct trend toward home-based hemodialysis as patients seek greater convenience and autonomy in disease management. Healthcare providers introduce portable and easy-to-use dialyzers, making home treatment accessible to a wider range of patients. It enables reduced hospital visits and supports better quality of life for individuals managing chronic kidney disease. Home-based solutions also help address capacity constraints in dialysis centers and minimize exposure to healthcare-associated infections. Manufacturers respond by developing compact devices and training resources tailored for at-home use. The increasing adoption of telemedicine platforms further strengthens this trend, allowing clinicians to monitor patients remotely. Greater patient empowerment and flexible care models now shape market expectations.
- For instance, Fresenius Medical Care’s NxStage system had over 32,000 home hemodialysis machines in operation by the end of 2023, marking a significant increase in home-based renal therapy options.
Advances in High-Performance Membranes and Next-Generation Materials Lead Innovation
Recent years have seen rapid development in dialyzer membrane technology within the Blood Dialyzer Market. Companies introduce high-flux, high-efficiency membranes capable of superior toxin removal and reduced treatment duration. It enables clinicians to deliver more effective and personalized dialysis sessions, contributing to improved patient outcomes. Research in novel synthetic and natural polymers expands the options for more biocompatible and durable products. Medical professionals increasingly prefer membranes with enhanced hemocompatibility, which lowers the risk of inflammatory responses. Next-generation dialyzers with innovative materials support higher treatment safety and reliability. Continuous innovation in this space keeps the market highly competitive and dynamic.
- For instance, Nipro Corporation shipped 93 million dialyzers globally in 2023, reflecting both scale and advances in membrane design.
Focus on Infection Prevention and Single-Use Dialyzer Adoption Intensifies
Infection control has become a central concern in the Blood Dialyzer Market, driving a pronounced shift toward single-use dialyzers. Hospitals and clinics adopt disposable products to lower cross-contamination risks and comply with stringent regulatory guidelines. It also addresses concerns regarding multi-patient use and potential biohazard exposure. The preference for sterile, single-use solutions prompts leading manufacturers to scale up production and invest in automated packaging technologies. Greater awareness among patients and clinicians supports demand for safer, more hygienic dialyzer products. Regulatory agencies reinforce this trend by updating standards and inspection protocols. This collective focus raises the overall safety profile of renal care.
Sustainability Initiatives and Digital Health Integration Redefine Market Landscape
Growing environmental awareness leads the Blood Dialyzer Market toward sustainable practices and eco-friendly product innovation. Companies invest in recyclable and biodegradable dialyzer components to reduce medical waste and align with global sustainability goals. It encourages healthcare facilities to reconsider procurement strategies and select greener options where available. Digital health integration also transforms market operations, supporting remote monitoring, predictive maintenance, and real-time data analytics. Enhanced data collection helps providers optimize treatment protocols and improve patient outcomes. The convergence of sustainability and digitalization drives a new era of responsible, tech-enabled renal care. These trends collectively set the direction for future market evolution.
Market Challenges Analysis
High Treatment Costs and Reimbursement Barriers Limit Accessibility
The Blood Dialyzer Market faces significant challenges due to the high cost of dialysis treatments and the complexities of reimbursement structures across various regions. Patients often struggle to afford ongoing therapies, especially in low- and middle-income countries where public funding remains limited. It restricts access to life-saving renal care for a substantial portion of the global population. Insurance coverage and government support vary widely, leading to disparities in treatment availability. Dialysis providers encounter difficulties in managing operational costs while maintaining quality care standards. Fluctuating prices for raw materials and medical components add further strain. Addressing these economic barriers is crucial for expanding market reach and improving patient outcomes.
Regulatory Compliance and Quality Assurance Hinder Rapid Market Entry
Strict regulatory requirements and evolving standards challenge both established and emerging players in the Blood Dialyzer Market. Manufacturers must navigate complex approval processes, extensive clinical trials, and rigorous quality assurance protocols before bringing new products to market. It increases development timelines and raises operational expenses, especially for small and medium enterprises. Meeting international and regional standards for safety and efficacy remains a significant hurdle. Any delay or non-compliance can disrupt supply chains and delay product launches. Frequent updates to regulations force companies to invest in continuous monitoring and adaptation, impacting overall market agility. These compliance demands shape the pace and direction of innovation across the sector.
Market Opportunities
Expansion into Emerging Markets and Healthcare Infrastructure Development Presents New Growth Avenues
The Blood Dialyzer Market presents significant opportunities through expansion into emerging economies where the demand for renal care services is rapidly increasing. Rising investments in healthcare infrastructure create favorable conditions for introducing advanced dialysis technologies and services. It allows manufacturers to establish strong distribution networks and form partnerships with local healthcare providers. Governments and private entities are prioritizing improved access to life-saving therapies, supporting wider adoption of blood dialyzers. Increased health awareness and early diagnosis initiatives further expand the potential patient base. These dynamics create a promising landscape for companies seeking to broaden their global footprint. Strengthening presence in underserved regions will drive sustained growth for the sector.
Innovation in Product Design and Digital Integration Drives Future Market Potential
The Blood Dialyzer Market sees opportunity in the ongoing development of next-generation dialyzers featuring improved biocompatibility, reduced treatment times, and enhanced patient comfort. Manufacturers have begun integrating digital solutions such as remote monitoring, predictive analytics, and telemedicine support into dialysis care, elevating both clinical outcomes and operational efficiency. It encourages healthcare providers to adopt technologically advanced products, ensuring better treatment adherence and patient satisfaction. Growing interest in personalized medicine and eco-friendly product designs further fuels innovation. Collaborative research and development efforts with academic and clinical partners are expected to yield breakthroughs in dialyzer performance and sustainability. These advancements position the market for robust long-term expansion.
Market Segmentation Analysis:
By Services:
Within the services segment, recruitment services play a critical role by supplying skilled healthcare professionals for dialysis centers and hospitals. It supports the growing demand for nephrology specialists, dialysis technicians, and trained nursing staff, directly impacting the operational efficiency of care facilities. Homecare services are gaining traction with rising patient preference for treatment in comfortable, familiar settings. This segment enables chronic kidney disease patients to receive regular dialysis at home, which not only improves quality of life but also reduces the burden on hospital-based dialysis units. Managed services continue to gain relevance in the Blood Dialyzer Market by offering integrated solutions for dialysis facility operations. These providers streamline administration, ensure regulatory compliance, and maintain equipment, allowing healthcare providers to focus on patient care. Specialist care services address complex cases and rare renal conditions, delivering tailored interventions for high-risk patients who require advanced treatment protocols. It ensures that even the most challenging clinical needs receive dedicated support, promoting positive outcomes for vulnerable populations.
- For instance, DaVita Inc. employs 69,000 healthcare professionals worldwide, directly enabling high-quality care for more than 200,000 patients in its network.
By Application:
The pharmaceuticals and biotechnology segment drives significant demand by supplying dialyzer-compatible medications and innovating biocompatible materials for use in dialysis membranes. It supports the development of therapies that reduce side effects and improve treatment efficacy. The nursing and healthcare segment forms the backbone of the market, with nurses and allied professionals providing essential monitoring, patient education, and procedural support throughout the dialysis process. Medical devices constitute a pivotal segment, encompassing a range of advanced dialyzers, monitoring equipment, and disposables necessary for routine and emergency dialysis procedures. The “others” segment includes research institutions, academic hospitals, and specialty clinics that contribute to clinical innovation and training within the renal care ecosystem.
- For instance, Asahi Kasei Medical supplied dialyzers to over 80 countries and supported more than 10,000 research collaborations in the past decade, advancing both clinical practice and device development.
Segments:
Based on Services:
- Recruitment Services
- Homecare Services
- Managed Services
- Specialist Care Services
Based on Application:
- Pharmaceuticals & Biotechnology
- Nursing/Healthcare
- Medical Devices
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America Blood Dialyzer Market
North America Blood Dialyzer Market grew from USD 1,141.78 million in 2018 to USD 1,277.14 million in 2024 and is projected to reach USD 1,930.18 million by 2032, reflecting a compound annual growth rate (CAGR) of 5.3%. North America is holding a 35% market share. The United States dominates regional demand, driven by a high prevalence of chronic kidney disease and robust healthcare infrastructure. Canada supports market expansion through government-backed renal care programs and widespread adoption of advanced dialysis technologies. Ongoing investment in digital health platforms and home-based care models continues to support strong growth.
Europe Blood Dialyzer Market
Europe Blood Dialyzer Market grew from USD 799.96 million in 2018 to USD 867.02 million in 2024 and is projected to reach USD 1,215.39 million by 2032, reflecting a CAGR of 4.3%. Europe is holding a 24% market share. Germany, France, and the United Kingdom lead market activity, supported by universal healthcare systems and a focus on quality renal care. Research and development in biocompatible dialyzers, as well as partnerships with leading medical device companies, help sustain steady growth across the region. Increased patient awareness and early diagnosis of kidney conditions support greater product demand.
Asia Pacific Blood Dialyzer Market
Asia Pacific Blood Dialyzer Market grew from USD 954.18 million in 2018 to USD 1,118.60 million in 2024 and is projected to reach USD 1,815.55 million by 2032, reflecting a CAGR of 6.2%. Asia Pacific is holding a 33% market share. China, Japan, and India remain key growth engines, fueled by expanding healthcare access and large populations affected by diabetes and hypertension. Governments invest in healthcare infrastructure and early-stage diagnosis programs, enabling greater adoption of dialysis services. Rising demand for cost-effective and high-efficiency dialyzers is driving innovation in local manufacturing.
Latin America Blood Dialyzer Market
Latin America Blood Dialyzer Market grew from USD 158.44 million in 2018 to USD 176.90 million in 2024 and is projected to reach USD 236.44 million by 2032, reflecting a CAGR of 3.7%. Latin America is holding a 4% market share. Brazil and Mexico account for the majority of regional demand, benefiting from expanding private healthcare and new dialysis clinics in urban centers. Access to dialysis treatment improves as governments implement health initiatives and partnerships with international device manufacturers grow. Infrastructure development in secondary cities supports continued market expansion.
Middle East Blood Dialyzer Market
Middle East Blood Dialyzer Market grew from USD 111.78 million in 2018 to USD 117.57 million in 2024 and is projected to reach USD 154.73 million by 2032, reflecting a CAGR of 3.5%. The Middle East holds a 3% market share. Saudi Arabia and the United Arab Emirates lead the region with investments in advanced dialysis centers and digital health integration. Public health campaigns for early screening and chronic disease management contribute to increasing demand. The market responds to a gradual rise in the number of patients requiring long-term renal support.
Africa Blood Dialyzer Market
Africa Blood Dialyzer Market grew from USD 73.87 million in 2018 to USD 106.14 million in 2024 and is projected to reach USD 155.35 million by 2032, reflecting a CAGR of 5.1%. Africa holds a 3% market share. South Africa, Nigeria, and Egypt are key markets, where access to dialysis care steadily improves through public-private partnerships and international aid programs. Initiatives targeting early-stage renal disease, alongside growth in private healthcare investment, help drive product adoption. The market remains in an early phase, with long-term growth potential linked to continued improvements in healthcare infrastructure and training.
Key Player Analysis
- Accountable Healthcare Staffing
- AMN Healthcare
- Aya Healthcare
- CCM Recruitment
- CHG Management Inc.
- CPL Healthcare
- EGV Recruiting
- Euromotion Medical
- IMS Recruitment
- Medacs Global Group Limited
- Proclinical
- SOLIANT HEALTH
Competitive Analysis
The Blood Dialyzer Market is characterized by the presence of several leading players including Fresenius Medical Care AG & Co. KGaA, Baxter International Inc., Nipro Corporation, B. Braun Melsungen AG, and Asahi Kasei Corporation. These companies consistently invest in research and development to introduce advanced dialyzer membranes with enhanced biocompatibility and improved toxin clearance, catering to the evolving needs of dialysis patients. Their robust product portfolios include both high-flux and low-flux dialyzers, offering flexible solutions for diverse clinical settings. Strategic collaborations with hospitals, clinics, and government health organizations help them expand market reach and secure long-term supply agreements. Strong global distribution networks ensure timely product availability and technical support across developed and emerging regions. The top players maintain a competitive edge through continuous product innovation, strict adherence to quality standards, and a focus on sustainability, including the development of eco-friendly and single-use dialyzers. Pricing strategies and customer support services further strengthen their market positions. Regulatory compliance and local manufacturing capabilities enable these companies to address region-specific requirements efficiently. Overall, intense competition among these key players drives ongoing innovation and elevates the standard of care in the Blood Dialyzer Market.
Recent Developments
- In April 2024, Royal Victoria Regional Health Centre (RVH) introduced a Home Hemodialysis Program, offering patients with chronic kidney disease enhanced treatment flexibility. Home hemodialysis, compared to in-center sessions, not only grants patients greater autonomy but also promises improved health outcomes and a higher quality of life.
- In February 2024, Fresenius Medical Care (FME) received U.S. Food and Drug Administration (FDA) 510(k) clearance for its 5008X Hemodialysis System. This approval enables the company to introduce a new standard of care in dialysis therapy for individuals with kidney diseases in the United States.
- In February 2023, Asahi Kasei Corporation announced the development of a new dialyzer that is specifically designed for home hemodialysis. The new dialyzer is smaller and lighter than traditional dialyzers, making it easier for patients to use at home.
- In January 2023, Baxter International Inc. announced the launch of its new EverlinQ endoAVF System. The EverlinQ endoAVF System is a catheter-based dialyzer that is designed to create a connection between a patient's vein and artery. This connection allows blood to be filtered more efficiently than with traditional dialyzers.
Market Concentration & Characteristics
The Blood Dialyzer Market exhibits a moderately high level of market concentration, with a few multinational corporations commanding a significant share of global revenues. It is characterized by a strong emphasis on technological innovation, stringent quality standards, and continuous product development. Leading manufacturers consistently introduce new dialyzer models that feature advanced membrane materials, enhanced biocompatibility, and improved patient safety profiles. The market relies on a global supply chain and well-established distribution networks to ensure product availability across diverse healthcare environments. Intense competition encourages investment in research and development, driving improvements in performance, sustainability, and cost efficiency. Regulatory compliance remains a defining feature, with companies maintaining rigorous standards to meet both international and region-specific requirements. The Blood Dialyzer Market continues to evolve, shaped by shifting patient preferences, rising demand for home-based treatments, and the integration of digital health technologies.
Report Coverage
The research report offers an in-depth analysis based on Services, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Continued advancements in membrane technology will enhance toxin clearance and reduce treatment duration.
- Integration of digital health tools will support remote monitoring and real-time treatment adjustments.
- Demand for home-based and portable dialyzers will grow due to patient preference for convenience.
- Increased adoption of single-use dialyzers will improve infection control and compliance with hygiene standards.
- Manufacturers will expand in emerging markets, leveraging infrastructure development and rising healthcare access.
- Sustainability pressures will push companies to develop recyclable and biodegradable dialyzer components.
- Collaborative research between industry and academia will drive innovation in biocompatible materials.
- Customizable dialyzer solutions will gain popularity to cater to patient-specific treatment needs.
- Regulatory harmonization across regions will streamline product approvals and market entry.
- Artificial intelligence and predictive analytics will optimize treatment protocols and improve patient outcomes.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Chronic Kidney Disease and Related Disorders
The increasing global incidence of chronic kidney disease, diabetes, and hypertension is expanding the population requiring regular dialysis, directly fueling demand for blood dialyzers. The growing geriatric population, which is at higher risk for renal impairment, further amplifies this need.
Advancements in Dialyzer Membrane Technology and Biocompatibility
Continuous innovation in dialyzer membranes, including the development of high-flux and high-efficiency products, is improving toxin removal and patient safety. These technological advancements make dialysis more effective and appealing to both providers and patients.
Expansion of Dialysis Infrastructure and Accessibility in Emerging Markets
Significant investments in healthcare infrastructure, especially in developing regions, are increasing the number of dialysis centers and improving access to treatment. This expansion enables more patients to receive life-saving renal therapy and drives market growth.
Shift Toward Home-Based Hemodialysis and Single-Use Dialyzers
Patient preference for home-based dialysis is rising due to convenience and improved quality of life, prompting manufacturers to develop portable and user-friendly dialyzers. Additionally, the adoption of single-use dialyzers is increasing as healthcare providers prioritize infection control and regulatory compliance.
Focus on Sustainability and Eco-Friendly Product Development
Growing environmental awareness is pushing manufacturers to design recyclable and biodegradable dialyzer components, aligning with global sustainability goals. This trend is influencing procurement decisions and shaping the future direction of product innovation in the market.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Blood Dialyzer Market?
What factors are driving the growth of the Blood Dialyzer Market?
What are the key segments within the Blood Dialyzer Market?
What are some challenges faced by the Blood Dialyzer Market?
Who are the major players in the Blood Dialyzer Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Hospitals
- 1.2.2 Dialysis Centers
- 1.2.3 Home Care Settings
- 1.2.4 Specialty Clinics
- 1.3 By Services
- 1.3.1 Recruitment Services
- 1.3.2 Homecare Services
- 1.3.3 Managed Services
- 1.3.4 Specialist Care Services
- 1.4 By Application
- 1.4.1 Pharmaceuticals & Biotechnology
- 1.4.2 Nursing/Healthcare
- 1.4.3 Medical Devices
- 1.4.4 Others
- 1.5 By Product Type
- 1.5.1 High-Flux Dialyzers
- 1.5.2 Low-Flux Dialyzers
- 1.5.3 Single-Use Dialyzers
- 1.5.4 Reusable Dialyzers
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,663.38 million → 2032: USD 5,507.64 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Blood Dialyzer Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Blood Dialyzer Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Blood Dialyzer Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Blood Dialyzer Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Blood Dialyzer Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Blood Dialyzer Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Blood Dialyzer Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Blood Dialyzer Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,663.38 million → 2032: USD 5,507.64 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Blood Dialyzer Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Dialysis Centers
- 12.3.7.3 Home Care Settings
- 12.3.7.4 Specialty Clinics
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Services - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Recruitment Services
- 12.4.7.2 Homecare Services
- 12.4.7.3 Managed Services
- 12.4.7.4 Specialist Care Services
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Pharmaceuticals & Biotechnology
- 12.5.7.2 Nursing/Healthcare
- 12.5.7.3 Medical Devices
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Product Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 High-Flux Dialyzers
- 12.6.7.2 Low-Flux Dialyzers
- 12.6.7.3 Single-Use Dialyzers
- 12.6.7.4 Reusable Dialyzers
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Blood Dialyzer End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Blood Dialyzer Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Blood Dialyzer Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Blood Dialyzer Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Fresenius Medical Care AG & Co. KGaA
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Baxter International Inc.
- 18.4 Nipro Corporation
- 18.5 B. Braun Melsungen AG
- 18.6 Asahi Kasei Corporation
- 18.7 DaVita Inc.
- 18.8 Toray Medical Co., Ltd.
- 18.9 Medtronic plc
- 18.10 NxStage Medical (Fresenius)
- 18.11 JMS Co. Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

