
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Bone Sonometer Market Size 2024 | USD 12865 Million |
| Bone Sonometer Market, CAGR | 8.8% |
| Bone Sonometer Market Size 2032 | USD 25260.4 Million |
Market Overview:
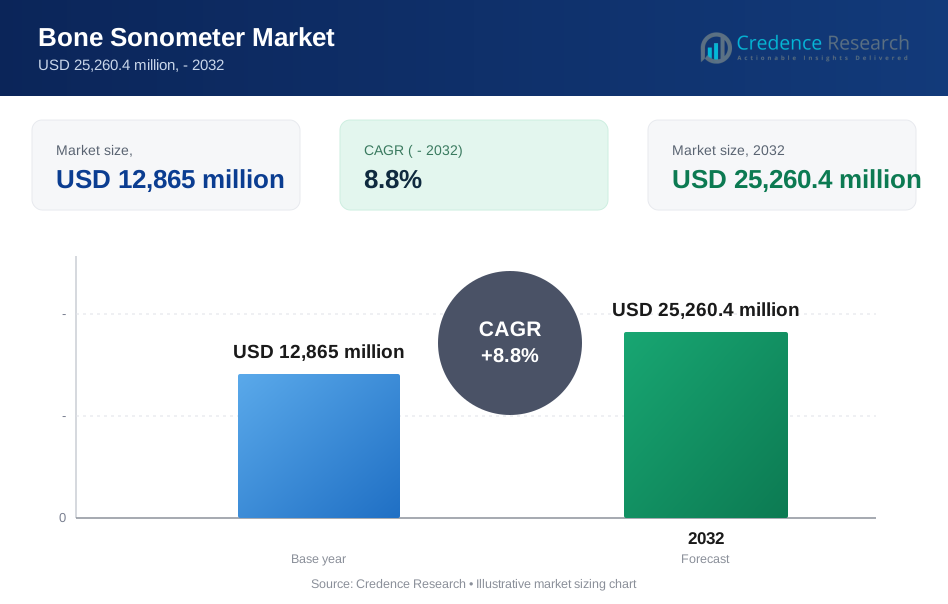
The Bone Sonometer Market is projected to grow from USD 12865 million in 2024 to an estimated USD 25260.4 million by 2032, with a compound annual growth rate (CAGR) of 8.8% from 2024 to 2032.
Market drivers for the bone sonometer market include the rising prevalence of osteoporosis and other musculoskeletal conditions, particularly within aging populations, which is leading to a growing demand for effective diagnostic tools. Bone sonometers offer a non-invasive, cost-effective solution for measuring bone density, making them highly attractive for routine screening and early diagnosis. The increased focus on preventive healthcare measures and early intervention strategies is further boosting demand. Additionally, advancements in medical imaging and diagnostic technologies have led to more accurate, efficient, and user-friendly bone sonometers, enhancing their utility and adoption. Supportive government initiatives aimed at public health awareness, bone health programs, and increasing funding for healthcare infrastructure are propelling market expansion. The market is also benefiting from rising disposable incomes, an increasing number of healthcare facilities, and the growing prevalence of sedentary lifestyles contributing to bone health challenges, especially in developing economies.
From a regional perspective, North America remains the leading market for bone sonometers, driven by a high incidence of osteoporosis, advanced healthcare infrastructure, and rising healthcare expenditure. The region benefits from strong public health initiatives, widespread awareness, and favorable reimbursement policies for bone health diagnostics. Europe follows closely, with its growth fueled by a significant elderly population and government-backed programs promoting bone health awareness and preventive care. The Asia-Pacific region is poised for rapid growth, driven by increasing healthcare investments, a rising middle-class population, and expanding awareness of bone health issues, particularly in countries like China, India, and Japan. Meanwhile, Latin America and the Middle East & Africa are experiencing steady growth, with improving healthcare infrastructure, growing health awareness campaigns, and an increasing focus on advanced diagnostic technologies contributing to market expansion.
Market Drivers:
Increasing Prevalence of Osteoporosis and Bone Disorders:
The rising prevalence of osteoporosis and other bone-related disorders globally is a significant driver of the bone sonometer market. As populations age, the incidence of bone density-related conditions continues to increase, driving the need for effective and reliable diagnostic tools. Bone sonometers provide non-invasive, precise measurements of bone density, making them an essential tool for early detection and intervention. For example, according to the International Osteoporosis Foundation, osteoporosis causes more than 8.9 million fractures annually, resulting in an osteoporotic fracture every 3 seconds. The growing awareness of osteoporosis prevention and management has further accelerated the demand for bone sonometers, as early detection can significantly reduce healthcare costs and improve patient outcomes.
Advancements in Diagnostic Technologies:
Technological advancements in medical imaging and diagnostic equipment are driving the adoption of bone sonometers. Recent innovations have resulted in more accurate, efficient, and portable devices, making bone density testing accessible to a broader range of healthcare settings, including hospitals, clinics, and even mobile health units. For example, the GE Healthcare Lunar iDXA system offers high-resolution images and precise measurements with a precision error of less than 1%. These advancements enhance the precision and speed of bone density measurements while offering a user-friendly experience for both healthcare professionals and patients. The integration of digital technologies and automated data analysis features has further strengthened the appeal of these devices.
Focus on Preventive Healthcare and Early Diagnosis:
The growing emphasis on preventive healthcare and early diagnosis is another key driver boosting the bone sonometer market. Healthcare systems worldwide are increasingly prioritizing proactive measures to detect and manage chronic conditions before they progress to more severe stages. Bone sonometers play a crucial role in this shift, enabling the early identification of individuals at risk for osteoporosis and fractures. Government health initiatives and campaigns aimed at raising awareness about bone health have further heightened demand for bone sonometry. Screening programs targeting at-risk populations, including the elderly, menopausal women, and individuals with specific risk factors, have proven effective in promoting the adoption of bone sonometers as a standard diagnostic tool in primary and specialized care settings.
Rising Healthcare Expenditure and Market Penetration in Emerging Economies:
The steady rise in healthcare expenditure across developed and emerging economies has contributed to the expansion of the bone sonometer market. Governments and private healthcare providers are investing in advanced diagnostic technologies to improve patient care and enhance the quality of life. In emerging economies, the growing availability of healthcare infrastructure, coupled with increasing disposable incomes, has facilitated the adoption of bone density testing equipment, including bone sonometers. Moreover, international organizations and health bodies are focusing on addressing the burden of bone-related diseases in low- and middle-income countries through awareness campaigns and subsidized healthcare initiatives. This trend is expected to continue driving market growth, as more individuals gain access to preventive and diagnostic bone health services, thus improving overall healthcare outcomes and reducing the incidence of osteoporosis-related complications.
Market Trends:
Growing Adoption of Portable and Handheld Bone Sonometers:
The bone sonometer market is witnessing a growing trend toward the adoption of portable and handheld devices. These compact, user-friendly sonometers are gaining traction due to their convenience, ease of use, and ability to perform bone density assessments in a variety of settings, including point-of-care environments, remote areas, and home healthcare. For instance, the Hologic Sahara portable bone sonometer weighs about 10 kg and can provide results in less than 60 seconds. The portability of these devices significantly expands their accessibility and allows for broader screening initiatives, especially in regions with limited healthcare infrastructure. As more healthcare providers prioritize convenience and flexibility in diagnostic procedures, the demand for portable bone sonometers is expected to rise, contributing to a broader reach and improved patient engagement.
Integration of AI and Advanced Data Analytics:
The integration of artificial intelligence (AI) and advanced data analytics capabilities into bone sonometers is reshaping the market landscape. AI-driven algorithms can enhance the accuracy and efficiency of bone density measurements by automating data analysis, reducing operator dependency, and identifying subtle changes in bone health over time. This integration not only improves diagnostic precision but also supports personalized treatment planning and ongoing patient monitoring. The use of AI-enabled bone sonometers aligns with the broader trend of digital transformation in healthcare, offering data-driven insights that can be seamlessly integrated into electronic health records (EHRs) and telemedicine platforms. As AI adoption in medical diagnostics grows, it is anticipated to further boost demand for advanced bone sonometers.
Emphasis on Early Detection and Preventive Care Programs:
Healthcare systems around the world are placing greater emphasis on early detection and preventive care, a trend that has directly impacted the bone sonometer market. Public health campaigns and community screening programs are being implemented to identify individuals at risk for osteoporosis and related conditions before they develop severe complications. For instance, the SCOOP study in the UK demonstrated that community-based screening using bone sonometers reduced hip fractures by 28% among older women. This focus on early intervention is driving demand for non-invasive and efficient bone density assessment tools. Bone sonometers, with their capability to provide fast and reliable measurements, are becoming a key component of these initiatives. In addition, partnerships between healthcare organizations and manufacturers to support preventive health strategies are further propelling market growth.
Increasing Awareness and Education on Bone Health:
A rising awareness of bone health, driven by educational campaigns, social media outreach, and advocacy by healthcare organizations, is playing a pivotal role in boosting the demand for bone sonometers. Patients and healthcare providers alike are becoming more aware of the importance of bone density testing for individuals at risk of osteoporosis, particularly post-menopausal women, older adults, and those with chronic health conditions. Greater patient education on bone health and the risks of untreated osteoporosis is encouraging routine testing and monitoring. As a result, healthcare providers are increasingly incorporating bone sonometers into standard diagnostic and preventive care protocols, reflecting a positive trend in both public and private healthcare sectors toward proactive bone health management.
Market Restraints and Challenges:
High Cost of Bone Sonometers:
One of the primary restraints in the bone sonometer market is the high cost of these devices. Advanced bone sonometers, equipped with cutting-edge technology and enhanced accuracy features, often come with a substantial price tag. This high initial cost poses a barrier to adoption, particularly for smaller healthcare facilities, clinics, and providers in resource-limited regions. Many healthcare systems in developing countries find it challenging to justify such capital expenditures without adequate reimbursement support. As a result, cost constraints can limit the reach and accessibility of bone sonometers, particularly for populations that would benefit from routine screening and early intervention.
Limited Availability and Accessibility in Low-Resource Settings:
Despite advancements in healthcare technology, the availability and accessibility of bone sonometers remain limited in low- and middle-income regions. Infrastructure deficiencies, insufficient healthcare funding, and a lack of trained personnel are common challenges in these areas, hindering the adoption of bone density testing devices. In addition, inadequate healthcare infrastructure makes it difficult for public health programs to reach underserved populations with effective screening initiatives. As a result, this limited penetration in emerging markets can slow overall market growth, as a substantial portion of the global population may remain underserved in terms of osteoporosis screening and management.
Dependence on Alternative Diagnostic Methods:
The reliance on alternative diagnostic methods, such as dual-energy X-ray absorptiometry (DEXA) and other imaging technologies, presents a challenge for the bone sonometer market. DEXA scans are considered the gold standard for bone density measurement, and their widespread use in established healthcare systems can limit the adoption of bone sonometers. Furthermore, healthcare providers' familiarity with established methods, combined with perceived differences in diagnostic accuracy and application scope, may slow the shift to sonometry-based alternatives, despite their benefits in terms of convenience and portability. Overcoming this challenge requires greater efforts in demonstrating comparable accuracy, efficacy, and broader use cases for bone sonometers.
Market Segmentation Analysis:
The bone sonometer market is segmented based on portability, extremity, technology, application, and end user.
By portability, the market is divided into stationary and portable devices. Portable bone sonometers are witnessing increased demand due to their flexibility and ease of use, especially in outpatient settings and remote areas. Stationary devices, on the other hand, are more commonly used in hospitals and large diagnostic centers due to their enhanced precision and capacity for high patient volumes.
By extremity, the market is categorized into axial and peripheral bone sonometry. Axial bone sonometers, used primarily for measuring bone density in the spine and hip, are more commonly utilized in clinical settings for their reliability in osteoporosis diagnosis. Peripheral bone sonometers, which assess bone density in areas such as the wrist, are valued for their portability and faster testing capabilities.
By technology, the market includes dual-energy X-ray absorptiometry (DEXA), ultrasound, quantitative computed tomography (QCT), quantitative ultrasound (QUS), and others like peripheral quantitative computed tomography (pQCT). DEXA remains the gold standard for bone density measurement, while QUS and portable devices are gaining traction for their cost-effectiveness and convenience.
By application, the market is segmented into osteoporosis diagnosis, fracture risk assessment, body composition measurement, rheumatoid arthritis (RA) and osteoarthritis diagnosis and prognosis, pediatric applications, and others.
By End-user segments include hospitals, specialty clinics, diagnostic centers, ambulatory surgical centers, research institutions, and others like physician offices, with hospitals and diagnostic centers being major revenue contributors due to their higher patient inflows and adoption of advanced diagnostics.
Segmentation:
By Portability:
- Stationary
- Portable
By Extremity:
- Axial Bone Sonometry
- Peripheral Bone Sonometry
By Technology:
- Dual Energy X-Ray Absorptiometry (DEXA),
- Ultrasound, Quantitative Computed Tomography (QCT),
- Quantitative Ultrasound (QUS),
- Others (Peripheral Quantitative Computed Tomography (pQCT))
By Application:
- Osteoporosis, (Osteopenia Diagnosis, fracture Risk Assessment)
- Body Composition Measurement
- RA & Osteoarthritis Diagnosis & Prognosis
- Pediatric Applications
- Others
By End User:
- Hospitals,
- Specialty Clinics,
- Diagnostic Centers,
- Ambulatory Surgical Centers,
- Research Institutions,
- Others (Physician Offices)
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
The bone sonometer market shows substantial regional differences, primarily driven by variations in healthcare infrastructure, the prevalence of osteoporosis, and the adoption of diagnostic technologies.
North America leads the market, with its growth driven by a high prevalence of osteoporosis and related bone conditions, as well as a well-developed healthcare infrastructure that prioritizes preventive healthcare. The United States plays a major role in this dominance due to strong public health initiatives, widespread adoption of bone density screening, and favorable reimbursement policies. The increasing use of advanced diagnostic tools, including portable bone sonometers, further contributes to the market's growth in the region.
Europe ranks as the second-largest market, with major contributions from countries like Germany, the United Kingdom, and France. The region's growth is propelled by a significant aging population and government-supported programs aimed at raising awareness of bone health and promoting early detection of osteoporosis. Europe's commitment to preventive healthcare measures and advanced diagnostic systems, alongside a growing emphasis on public health initiatives and research, supports market expansion. The use of portable and innovative technologies also continues to gain traction within this market.
The Asia-Pacific region is expected to experience rapid growth due to rising healthcare investments, increasing disposable incomes, and growing awareness of bone health issues across major markets such as China, India, and Japan. The region's large and diverse population, coupled with a greater emphasis on healthcare access and preventive care, presents substantial opportunities for bone sonometer manufacturers. Government programs focused on improving osteoporosis screening and treatment are also driving increased adoption of these devices.
Latin America and the Middle East & Africa are smaller but steadily growing markets. Expansion in these regions is fueled by improving healthcare infrastructure, a growing awareness of bone-related diseases, and increased access to diagnostic technologies. Although economic constraints and limited healthcare resources pose challenges, ongoing efforts by international organizations and governments to enhance healthcare delivery and promote bone health awareness are contributing to gradual market growth.
Key Player Analysis:
- Carestream Health
- Digirad
- Esaote
- FUJIFILM Holdings
- GE Healthcare
- Hitachi Medical
- Hologic
- Medtronic
- Mindray Medical
- Osteometer
- Planmed
- Samsung Electronics
- Siemens Healthineers
- Stryker
- Zimmer Biomet
Competitive Analysis:
The bone sonometer market is characterized by intense competition among key players striving to capture a larger share through innovation, product differentiation, and strategic partnerships. Major market players include established companies such as GE Healthcare, Hologic Inc., Diagnostic Medical Systems Group, and BeamMed Ltd., each focusing on enhancing their product offerings with advanced technologies, improved accuracy, and user-friendly features. Companies are investing heavily in research and development to introduce portable, cost-effective, and precise bone sonometers tailored to varying healthcare needs. Collaborations with healthcare providers and public health initiatives are common strategies to broaden market reach and foster awareness of bone health. Emerging competitors in the market are targeting niche applications, such as pediatric and portable solutions, to establish their presence. The competitive landscape is further shaped by price pressures, technological advancements, and growing demand in emerging markets, driving continuous innovation and market expansion.
Recent Developments:
- BeamMed Ltd. announced the launch of its new UltraSonic Bone Sonometer on October 15, 2024. This device features advanced ultrasound technology that provides high-resolution imaging for bone density assessment, aiming to enhance the accuracy of osteoporosis diagnosis and monitoring.
- Hologic Inc. entered into a strategic partnership with CompuMed, Inc. on November 1, 2024, to integrate their technologies for developing a comprehensive bone health management platform. This collaboration aims to combine Hologic's imaging capabilities with CompuMed's software solutions to improve patient outcomes through enhanced data analytics and reporting.
Market Concentration & Characteristics:
The bone sonometer market exhibits a moderately concentrated structure, with a mix of established players and emerging companies competing for market share. Dominant players, including GE Healthcare, Hologic Inc., and BeamMed Ltd., control a significant portion of the market, leveraging strong brand recognition, extensive distribution networks, and advanced product portfolios. Market concentration is driven by ongoing innovation, as key players focus on technological advancements and enhancements in portability, accuracy, and user-friendly features. The market is characterized by continuous innovation and a growing emphasis on preventive healthcare, leading to the development of portable and cost-effective bone sonometers. Intense competition and the rising demand for more accessible diagnostic tools have resulted in frequent product launches and strategic partnerships. The market's evolution is shaped by technological advancements, regulatory requirements, and regional healthcare dynamics, creating a competitive environment with opportunities for new entrants focused on specialized applications.
Report Coverage:
The research report offers an in-depth analysis based on By Portability, By Extremity, By Technology, By Application and By End User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising demand for portable bone sonometers will drive market expansion, enabling more widespread screening and diagnosis in remote and outpatient settings.
- Technological advancements, such as AI integration, will improve diagnostic accuracy, efficiency, and patient outcomes.
- Increased prevalence of osteoporosis and bone health issues will sustain strong market growth, particularly among aging populations.
- Greater emphasis on preventive healthcare and early intervention will boost demand for non-invasive bone density measurement tools.
- Expanding awareness campaigns by healthcare organizations will elevate public understanding and adoption of bone health diagnostics.
- Emerging markets in Asia-Pacific, Latin America, and Africa present growth opportunities due to improving healthcare infrastructure and rising disposable incomes.
- Strategic collaborations between market leaders and healthcare providers will enhance accessibility and broaden product reach.
- Ongoing competition and innovation will lead to more cost-effective solutions, making bone sonometers increasingly accessible.
- Regulatory support for advanced diagnostics will facilitate market entry and technology adoption across diverse healthcare settings.
- Investments in pediatric and specialized applications will create niche market opportunities and drive product diversification.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth rate of the bone sonometer market?
What will be the market size by 2032?
What drives the demand for bone sonometers?
Which region dominates the bone sonometer market?
What challenges does the market face?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Bone Sonometer Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Bone Sonometer Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (2032) (base year: USD 12,865 million → 2032: USD 25,260.4 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Bone Sonometer Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Bone Sonometer Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Bone Sonometer Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Bone Sonometer Market Drivers
- 3.3 Bone Sonometer Market Restraints & Challenges
- 3.4 Bone Sonometer Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Bone Sonometer Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Bone Sonometer Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Bone Sonometer category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Bone Sonometer Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Bone Sonometer Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Bone Sonometer market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Bone Sonometer Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Bone Sonometer Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Bone Sonometer Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Bone Sonometer (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Bone Sonometer Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Bone Sonometer Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & 2032)
- 7.1.2 Channel Mix Evolution (2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Bone Sonometer Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Bone Sonometer Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Bone Sonometer Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Bone Sonometer Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Bone Sonometer Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Bone Sonometer Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Bone Sonometer Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
