
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Canada Data Center UPS Market Size 2023 | USD 166.21 Million |
| Canada Data Center UPS Market, CAGR | 4.56% |
| Canada Data Center UPS Market Size 2032 | USD 248.43 Million |
Market Overview
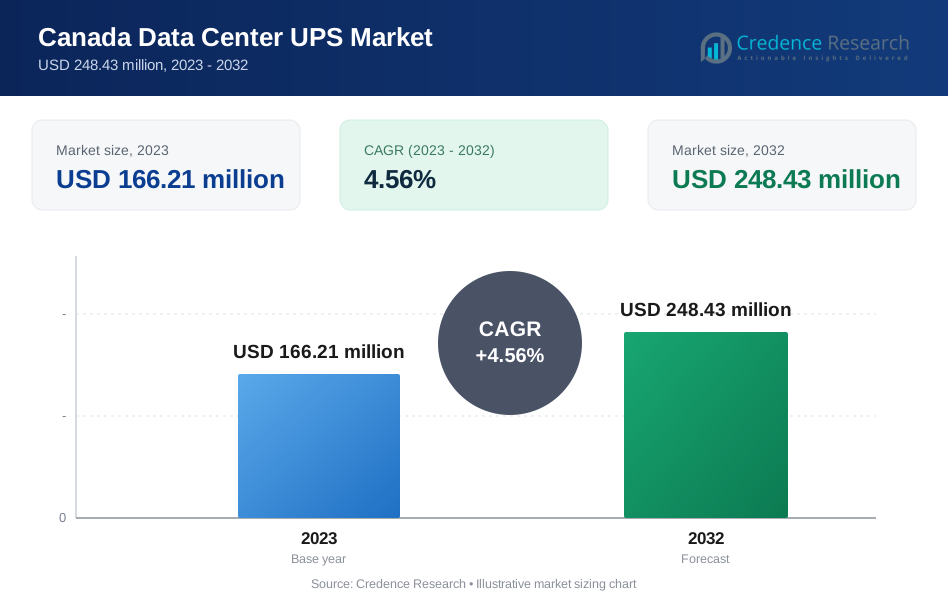
The Canada Data Center UPS Market is projected to grow from USD 166.21 million in 2023 to an estimated USD 248.43 million by 2032, achieving a compound annual growth rate (CAGR) of 4.56% from 2024 to 2032. This growth reflects an increasing demand for reliable power backup systems as the expansion of digital infrastructure and the surge in data generation continue across the country.
The market growth is driven by several key factors, including the rapid digital transformation across sectors such as finance, healthcare, and telecommunications. Additionally, the increase in cloud adoption and the proliferation of IoT devices have intensified the demand for robust data centers and, consequently, UPS systems. Trends toward green energy solutions and modular UPS systems are also influencing market dynamics, with organizations emphasizing energy efficiency and scalability in their infrastructure strategies.
Geographically, key market growth is observed in regions with high concentrations of data centers, such as Ontario, British Columbia, and Quebec. These areas benefit from strong digital infrastructure investments and favorable policies supporting data center expansion. Leading players in the Canadian data center UPS market include Schneider Electric, Eaton, Vertiv, and ABB, who continue to innovate and introduce solutions tailored to meet the evolving needs of data center operators in Canada. Their commitment to enhancing UPS technology positions them well to capture the growing market demand.
Market Drivers
Rapid Digital Transformation and Data Center Expansion
One of the primary drivers of the Canada Data Center UPS market is the accelerated pace of digital transformation across various industries. Sectors such as finance, healthcare, e-commerce, and telecommunications are increasingly reliant on data-driven operations, which require robust data center infrastructures to process, store, and manage large volumes of information securely and efficiently. As businesses expand their digital services to meet growing customer demands, they are building and upgrading data centers across Canada to ensure operational stability and scalability. For instance, the number of data centers in Canada has grown from 279 in 2020 to over 350 in 2024, reflecting the rapid pace of digital transformation across industries.With more organizations investing in data centers to support critical business processes, the demand for uninterrupted power supply (UPS) systems is rising sharply. UPS systems play a vital role in protecting data centers from power disruptions, voltage fluctuations, and other electrical anomalies that could result in data loss, downtime, and financial losses. Thus, the need for reliable and resilient power backup solutions is increasing in parallel with the growth of the data center infrastructure, driving the Canada Data Center UPS market forward.
Increased Cloud Adoption and IoT Proliferation
The adoption of cloud computing and the proliferation of Internet of Things (IoT) devices represent significant market drivers for UPS systems in Canadian data centers. Cloud adoption is expanding as more organizations prioritize flexibility, scalability, and cost efficiency in their IT infrastructure, with a shift toward hybrid and multi-cloud environments. This increased reliance on cloud-based services intensifies the need for high-performance data centers, which, in turn, depend on effective UPS solutions to ensure continuous availability and performance. For instance, cloud adoption in Canada has led to a 45% increase in data center capacity between 2019 and 2023.Similarly, the IoT ecosystem is expanding rapidly, connecting various devices across industrial, commercial, and residential settings to exchange real-time data and insights. The surge in connected devices generates a substantial influx of data, necessitating more data storage and processing capabilities within data centers. In this context, UPS systems are crucial for maintaining the uptime and reliability of data centers housing IoT ecosystems, especially in sectors like manufacturing, transportation, and healthcare, where uninterrupted power supply is critical to avoid operational disruptions. For instance, the number of IoT devices in Canada is projected to reach 500 million by 2025, driving the need for expanded data center infrastructure. Therefore, cloud adoption and IoT proliferation are key contributors to the rising demand for UPS solutions in Canada's data center market.
Growing Emphasis on Energy Efficiency and Sustainability
With increasing awareness of climate change and environmental responsibility, the demand for energy-efficient and sustainable solutions has become a significant driver in the Canada Data Center UPS market. Data centers are energy-intensive facilities, often consuming substantial amounts of power to ensure optimal operation. Consequently, businesses and organizations are seeking ways to minimize their carbon footprint and reduce energy consumption without compromising performance. This shift in focus has spurred interest in advanced UPS systems that incorporate energy-efficient technologies, such as modular configurations, lithium-ion batteries, and renewable energy integration. For instance, energy-efficient UPS systems have helped reduce power consumption in Canadian data centers by up to 30% compared to traditional systems.Modular UPS systems, in particular, enable organizations to scale their power backup capacity based on demand, thereby optimizing energy use and lowering operational costs. The adoption of modular UPS configurations has increased by 60% in Canadian data centers over the past 3 years. Additionally, some companies are exploring renewable energy sources, like solar or wind power, to power their data centers, further reducing reliance on conventional power sources.This shift toward sustainability is not only a cost-saving initiative but also a response to government regulations and policies aimed at reducing carbon emissions in Canada. The push for energy-efficient UPS systems is therefore a key driver as organizations prioritize eco-friendly practices while ensuring data center reliability.
Stringent Regulatory Requirements for Data Security and Uptime
Another critical factor propelling the Canada Data Center UPS market is the regulatory landscape that mandates stringent data security, privacy, and uptime standards across industries. Canada has implemented several data protection regulations, such as the Personal Information Protection and Electronic Documents Act (PIPEDA), which requires organizations to uphold robust data security practices and ensure data availability. Additionally, industries such as finance and healthcare are subject to compliance standards that mandate high levels of uptime and data protection to maintain continuity and safeguard sensitive information. For example, financial institutions must ensure uninterrupted access to transactional data to avoid service disruptions and maintain customer trust. In healthcare, patient information and medical records must be accessible at all times to support critical care and decision-making processes. Consequently, compliance with these regulations necessitates the deployment of UPS systems that can maintain data center uptime even during power failures, effectively mitigating risks associated with downtime and data loss. As regulatory oversight continues to intensify, the demand for reliable UPS systems is expected to grow, solidifying their importance in meeting compliance standards and supporting data center resilience across Canada.
Market Trends
Shift Toward Modular and Scalable UPS Solutions
In the evolving Canada Data Center UPS market, a prominent trend is the shift toward modular and scalable UPS systems, which offer flexibility, efficiency, and cost-effectiveness. Modular UPS solutions allow data center operators to add power modules incrementally, based on demand, without the need for a complete overhaul of the power infrastructure. This scalability is particularly valuable in a fast-changing environment where data requirements continue to expand rapidly. For instance, a leading data center in Toronto recently implemented a modular UPS system that allowed them to increase their power capacity from 2 MW to 5 MW over a period of 18 months, without any significant downtime or infrastructure overhaul. Modular UPS systems are designed to optimize energy use by allowing only necessary modules to operate, reducing overall power consumption and operational costs. They also simplify maintenance, as individual modules can be serviced or replaced without affecting the entire system, thereby improving reliability and minimizing downtime. Additionally, this trend aligns with sustainability goals, as data centers can enhance energy efficiency and reduce carbon emissions, responding to both regulatory pressures and corporate sustainability initiatives. With these advantages, the adoption of modular and scalable UPS solutions is becoming increasingly common in Canada's data centers, especially among operators seeking both operational resilience and energy efficiency.
Increased Adoption of Lithium-Ion Batteries in UPS Systems
Another significant trend shaping the Canada Data Center UPS market is the increased adoption of lithium-ion batteries over traditional valve-regulated lead-acid (VRLA) batteries. Lithium-ion batteries offer several advantages, including a longer lifespan, reduced weight, and better performance under high-temperature conditions, which make them particularly suitable for data centers. While lithium-ion batteries typically have a higher upfront cost, their extended lifespan and lower maintenance requirements result in reduced total cost of ownership over time. For instance, a major data center operator in Vancouver reported that after switching to lithium-ion batteries in their UPS systems, they experienced a 40% reduction in battery replacement frequency over a 5-year period compared to their previous VRLA battery setup. Additionally, lithium-ion batteries have a higher power density, allowing for smaller footprints in data centers where space optimization is a priority. As data centers become more complex and power-intensive, the reliability and longevity of lithium-ion batteries address both performance and efficiency requirements. Moreover, the shift toward lithium-ion batteries aligns with broader market demands for environmentally sustainable and energy-efficient solutions, as these batteries are less harmful to the environment compared to lead-acid counterparts. This transition toward lithium-ion technology highlights the market's focus on optimizing both the cost-efficiency and environmental impact of UPS solutions in Canada's data centers.
Market Restraints and Challenges
High Initial Investment and Maintenance Costs
One of the main challenges restraining the growth of the Canada Data Center UPS market is the high initial investment required for advanced UPS systems. Procuring and installing UPS infrastructure, especially modern solutions with features such as modularity and lithium-ion battery technology, demand significant upfront capital. This cost burden can deter smaller and mid-sized businesses from upgrading or expanding their data center infrastructure, especially when competing with other essential operational expenditures. Additionally, while high-performance UPS systems promise longevity and efficiency, they require regular maintenance and periodic testing to ensure uninterrupted performance. Maintenance costs, along with potential replacement expenses for components, add to the total cost of ownership, making these systems financially challenging for some organizations. These factors collectively present a notable barrier, as companies may delay upgrading their power infrastructure due to cost considerations, potentially affecting the market’s overall growth trajectory.
Complexity of Integrating with Existing Infrastructure
Integrating new UPS systems with legacy infrastructure is another significant challenge faced by data center operators in Canada. Many existing data centers are equipped with traditional, non-modular UPS systems that may not be compatible with modern, modular solutions, necessitating substantial infrastructure adjustments or complete overhauls. Additionally, data centers are often limited by spatial constraints, and adding or upgrading UPS equipment can be a logistical challenge in terms of space allocation and load balancing. The process of integrating new UPS systems also requires skilled technical expertise to ensure seamless operation, adding to operational complexity and costs. Furthermore, during integration or upgrades, data centers may need to schedule planned downtimes, which could disrupt service availability and impact end-user satisfaction. This complexity of integration, combined with the need for technical expertise and careful planning, poses a restraint for organizations considering UPS upgrades, thereby challenging market growth.
Market Segmentation Analysis
By UPS Type
The Canada Data Center UPS market is segmented based on UPS types, with each type catering to different data center needs and sizes. Standby UPS systems are cost-effective and popular among small-scale data centers due to their simplicity, though they are limited in their ability to handle significant power fluctuations. Line Interactive UPS systems are suitable for mid-sized data centers, providing better power conditioning and backup than standby systems, making them appealing to facilities needing moderate protection and control. However, Double Conversion On-Line UPS systems dominate the market, particularly for large data centers requiring continuous and robust power conditioning. This type of UPS is known for its reliability in handling critical loads, making it ideal for industries that prioritize high uptime, such as financial services and healthcare. Additionally, other UPS types, including hybrid solutions, are gaining traction as data centers seek flexibility and energy efficiency.
By Size of Data Center
Market segmentation by data center size reflects varying UPS requirements across different operational scales. Small data centers, such as those owned by SMEs, typically prefer cost-efficient standby or line-interactive UPS systems. Medium-sized data centers demand higher protection levels, often opting for line-interactive or modular UPS solutions to scale with their growing data needs. In contrast, large data centers, which handle extensive data volumes and require maximum uptime, predominantly use double-conversion UPS systems for continuous power conditioning. The large data center segment holds the largest market share due to the high demand for reliable backup power to support their high-performance infrastructure, especially among enterprises in the banking, technology, and healthcare sectors.
Segments
Based on UPS Type
- Standby UPS Systems
- Line-Interactive UPS Systems
- Double Conversion Online UPS Systems
- Other UPS Types
Based on Size of Data Center
- Small Data Centers
- Medium Data Centers
- Large Data Centers
Based on End-Use Vertical
- Banking and Financial Services
- Information Technology (IT)
- Healthcare
- Entertainment and Media
- Other End-User Verticals
Based on Region
- Ontario
- British Columbia
- Quebec
Regional Analysis
Ontario (45%)
Ontario holds the largest share of the Canada Data Center UPS market, accounting for approximately 45% of total market demand. The province’s leadership in this sector is due to its high concentration of data centers, particularly in the Greater Toronto Area, which is recognized as Canada’s primary tech hub. Major financial institutions, IT companies, and cloud service providers have their operations based in Ontario, necessitating robust data center infrastructure with reliable power backup solutions. The demand for double-conversion and modular UPS systems is particularly high in Ontario, as organizations seek to ensure data integrity and business continuity. Additionally, Ontario’s provincial government has shown a proactive approach toward digital infrastructure and renewable energy adoption, further supporting data center growth and fueling demand for advanced UPS solutions.
British Columbia (25%)
British Columbia follows Ontario with a market share of approximately 25%. Vancouver, as a prominent technology and entertainment hub, drives demand for data centers, which in turn supports a growing UPS market. The province’s close ties to the U.S. West Coast technology ecosystem make it an attractive location for data center operations. Demand for UPS systems in British Columbia is led by industries such as media, entertainment, and technology, where uptime is critical. Many organizations in British Columbia prioritize energy efficiency and sustainability, aligning with provincial goals for green energy, which has increased the adoption of lithium-ion and modular UPS systems. The province’s emphasis on environmental responsibility also supports the demand for UPS solutions that incorporate energy-saving technologies.
Key players
- ABB Group
- Eaton Corp.
- Riello
- Emerson Network Power
- Gamatronic Electron
- General Electric
- Phoenix Contact
- HBL Power Systems
- IntelliPower
- Mitsubishi Electric
- Controlled Power Company
- Delta Electronics
- Fuji Electric
- Piller Group
- Power Innovation International
- Riello
- Borri Industrial Power Solutions
- Clary
- AEG
- Belkin International
- Ametek
- Benning Power Electronics
- Toshiba
- Tripp Lite
- TDK
- Swelect Energy Systems
Competitive Analysis
The Canada Data Center UPS market is characterized by intense competition, with both global conglomerates and specialized manufacturers actively pursuing market share. Key players like ABB Group, Eaton Corp., and Mitsubishi Electric dominate due to their extensive product portfolios, advanced UPS technologies, and strong regional presence. Companies such as Emerson Network Power and General Electric leverage their diversified product lines and expertise in power management to meet the critical power needs of Canadian data centers.Mid-sized players, including Riello and Borri Industrial Power Solutions, focus on niche solutions such as modular and energy-efficient UPS systems, appealing to data centers aiming for scalability and reduced carbon footprint. Meanwhile, brands like Phoenix Contact and Delta Electronics are increasingly adopting sustainable practices and lithium-ion technology to stay competitive. The market’s emphasis on reliability, efficiency, and energy conservation creates opportunities for innovation and intensifies the competition among these leading and emerging players.
Recent Developments
- In October 2024, Phoenix Contact Group acquired iS5 Communications Inc., a Canadian company based in Mississauga, Ontario. This acquisition aims to strengthen Phoenix Contact's position in the market for critical infrastructure networks, including data centers. The expertise of iS5 Communications in cybersecurity and data analysis is expected to play a crucial role in developing solutions for infrastructure networks.
- In October 2024, ABB India launched the MegaFlex DPA (Decentralized Parallel Architecture) UPS solutions. While this launch was specifically for the Indian market, it's worth noting as ABB is a global company, and similar product launches might be expected in other markets, including Canada. The MegaFlex DPA is designed for high-density computing environments with high efficiency ratings and a small footprint, which could be relevant to the Canadian data center market.
Market Concentration and Characteristics
The Canada Data Center UPS Market is moderately concentrated, with a mix of global giants and specialized regional players catering to diverse industry needs. Key players like ABB Group, Eaton Corp., and Mitsubishi Electric dominate the market due to their extensive product portfolios and strong technical expertise, which appeal to large-scale data centers requiring robust, high-capacity UPS systems. The market also includes smaller firms and niche providers, such as Riello and Borri Industrial Power Solutions, that focus on modular and energy-efficient UPS solutions to meet the growing demand for scalability and sustainability. Characterized by innovation-driven competition, the market sees a strong emphasis on reliability, efficiency, and environmentally friendly technologies, with trends leaning toward lithium-ion batteries and modular UPS configurations that align with Canadian regulations and sustainability goals. This blend of innovation and adherence to stringent standards shapes the market's overall structure and drives continuous advancements in UPS offerings.
Report Coverage
The research report offers an in-depth analysis based on UPS Type, Size of Data Center, End-Use Vertical, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Increased investment in digital infrastructure, driven by sectors like finance, IT, and healthcare, will propel demand for reliable UPS solutions across Canada.
- The rising adoption of cloud computing and IoT is expected to drive the growth of data centers, increasing the need for advanced and scalable UPS systems.
- Modular UPS systems will see greater adoption due to their flexibility, allowing data centers to scale power backup as capacity needs evolve, optimizing both cost and energy efficiency.
- Lithium-ion batteries, with their longer lifespan and energy efficiency, are anticipated to replace traditional lead-acid batteries in UPS systems, supporting sustainability goals.
- Market players are likely to innovate in energy-efficient UPS designs as companies prioritize sustainability, complying with Canadian environmental standards and reducing operational costs.
- The growth of small and medium-sized data centers, particularly from SMEs, will fuel demand for affordable and compact UPS solutions, fostering market diversity.
- Government incentives and favorable policies aimed at digital transformation will encourage data center investments, boosting the need for reliable UPS infrastructure across regions.
- Essential sectors like banking, healthcare, and telecommunications will continue to rely on high-performance UPS systems to ensure continuous uptime and safeguard sensitive data.
- As data centers prioritize operational resilience, the demand for UPS maintenance services and lifecycle management is projected to rise, driving service-based revenue streams.
- Data center growth will likely expand to provinces beyond Ontario, Quebec, and British Columbia, driven by improved connectivity and regional investments, increasing UPS market penetration.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Canada Data Center UPS Market in 2023 and 2032, and what is the expected CAGR?
What factors are driving the growth of the Canada Data Center UPS Market?
How are trends in energy efficiency influencing the UPS market?
Which regions in Canada are seeing the most growth in the data center UPS market?
Who are the major players in the Canada Data Center UPS Market?
Why is there a growing demand for UPS systems in Canadian data centers?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Canada Data Center UPS Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Canada Data Center UPS Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 166.21 million → 2032: USD 248.43 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Canada Data Center UPS Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Canada Data Center UPS Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Canada Data Center UPS Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Canada Data Center UPS Market Drivers
- 3.3 Canada Data Center UPS Market Restraints & Challenges
- 3.4 Canada Data Center UPS Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Canada Data Center UPS Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Canada Data Center UPS Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Canada Data Center UPS category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Canada Data Center UPS Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Canada Data Center UPS Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Canada Data Center UPS market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Canada Data Center UPS Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Canada Data Center UPS Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Canada Data Center UPS Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Canada Data Center UPS (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Canada Data Center UPS Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Canada Data Center UPS Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Canada Data Center UPS Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Canada Data Center UPS Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Canada Data Center UPS Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Canada Data Center UPS Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Canada Data Center UPS Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Canada Data Center UPS Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Canada Data Center UPS Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
