
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Canada Diabetes Drugs Market Size 2024 | USD 2,676.75 Million |
| Canada Diabetes Drugs Market, CAGR | 2.55% |
| Canada Diabetes Drugs Market Size 2032 | USD 3,473.89 Million |
Market Overview
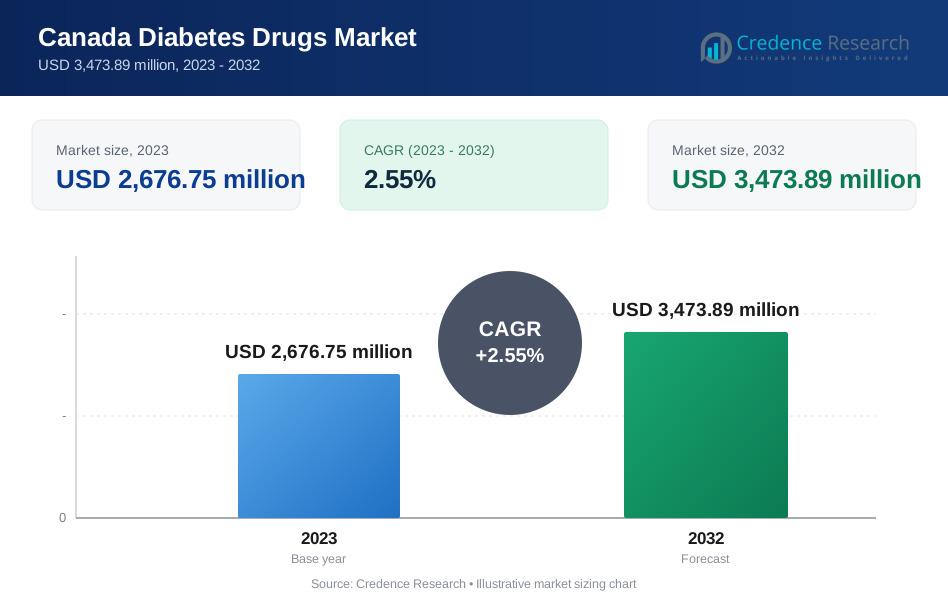
Canada Diabetes Drugs Market size was valued at USD 2,676.75 million in 2023 and is anticipated to reach USD 3,473.89 million by 2032, at a CAGR of 2.55% during the forecast period (2023-2032).
The Canada diabetes drugs market is driven by rising diabetes prevalence, an aging population, and increasing obesity rates. Advances in drug development, particularly in GLP-1 receptor agonists and SGLT2 inhibitors, are enhancing treatment efficacy and patient adherence. Government initiatives and healthcare funding support diabetes management, fostering market growth. The adoption of digital health solutions, including remote monitoring and AI-driven diagnostics, is improving disease management and treatment personalization. Additionally, the shift towards combination therapies is gaining traction, offering enhanced glycemic control with fewer side effects. Pharmaceutical companies are investing in R&D to develop novel therapeutics, including oral insulin and regenerative medicine approaches. The growing emphasis on preventive care and early diagnosis further bolsters demand for innovative diabetes medications. However, pricing pressures and stringent regulatory requirements pose challenges. Overall, increasing awareness, technological advancements, and strategic collaborations among key players are shaping the future of the Canada diabetes drugs market.
The Canada diabetes drugs market is geographically diverse, with strong demand across major provinces, including Ontario, Quebec, Western Canada, British Columbia, and Atlantic Canada. Urban centers benefit from advanced healthcare infrastructure and widespread access to innovative diabetes treatments, while rural areas face challenges in accessibility, prompting the expansion of telemedicine and digital health solutions. The market is highly competitive, with key players such as Novo Nordisk, Sanofi, Merck & Co., Eli Lilly, AstraZeneca, and Boehringer Ingelheim leading innovation in diabetes management. These companies focus on developing next-generation therapies, including GLP-1 receptor agonists, SGLT2 inhibitors, and combination treatments, to enhance efficacy and patient adherence. Additionally, firms like Medtronic and Roche are integrating smart diabetes management technologies, such as continuous glucose monitoring and digital insulin delivery systems. Strategic collaborations, R&D investments, and regulatory approvals are shaping the competitive landscape, driving the market toward advanced and patient-centric diabetes care solutions.
Market Insights
- The Canada diabetes drugs market was valued at USD 2,676.75 million in 2023 and is projected to reach USD 3,473.89 million by 2032, growing at a CAGR of 2.55%.
- Increasing diabetes prevalence, aging population, and obesity rates are key drivers fueling market growth.
- The adoption of innovative therapies like GLP-1 receptor agonists and SGLT2 inhibitors is reshaping treatment approaches.
- Stringent regulations and high drug costs pose challenges, limiting accessibility for some patients.
- Leading companies, including Novo Nordisk, Sanofi, Merck & Co., and Eli Lilly, focus on R&D and digital health integration.
- Ontario and Quebec dominate the market, while Western Canada and Atlantic Canada show steady growth.
- Rising demand for telemedicine and smart diabetes management solutions is driving technological advancements in the sector.
Market Drivers
Rising Prevalence of Diabetes and Aging Population
The increasing prevalence of diabetes in Canada is a primary driver of the diabetes drugs market. Sedentary lifestyles, poor dietary habits, and rising obesity rates contribute significantly to the growing number of diabetes cases. For instance, Diabetes Canada reports that over 11 million Canadians currently live with diabetes or prediabetes, with projections indicating a steady rise in these numbers. Additionally, the aging population further exacerbates the demand for diabetes medications, as older adults are more susceptible to type 2 diabetes. With a growing patient base, pharmaceutical companies and healthcare providers are focusing on improving access to effective treatments, driving market expansion.
Advancements in Drug Development and Personalized Medicine
The introduction of innovative diabetes drugs, particularly GLP-1 receptor agonists and SGLT2 inhibitors, is reshaping the treatment landscape. These drugs offer improved glycemic control, weight management benefits, and reduced cardiovascular risks compared to traditional therapies. For instance, Health Canada has approved several advanced therapies that leverage biotechnology and artificial intelligence to enable personalized treatment approaches. Precision medicine allows for the customization of drug regimens based on genetic and metabolic profiles, improving patient outcomes and adherence. As pharmaceutical companies invest heavily in research and development, new drug formulations, including oral insulin and regenerative therapies, are expected to further drive market growth.
Government Initiatives and Healthcare Funding
Supportive government policies and healthcare funding initiatives play a crucial role in the expansion of the diabetes drugs market in Canada. The government has implemented various programs to enhance diabetes management, including public reimbursement plans and subsidies for insulin and other essential medications. Additionally, Health Canada’s stringent regulatory framework ensures the safety and efficacy of new diabetes treatments, fostering trust and encouraging pharmaceutical innovation. The increasing collaboration between public health agencies and private organizations to promote early diagnosis and preventive care also contributes to market growth. These efforts are aimed at reducing the long-term economic burden of diabetes on the healthcare system while ensuring broader access to advanced treatments.
Integration of Digital Health Solutions and Telemedicine
The growing adoption of digital health technologies is transforming diabetes management, boosting the demand for innovative drug therapies. The rise of telemedicine, remote patient monitoring, and AI-driven diagnostic tools enables real-time tracking of blood glucose levels and medication adherence. Digital solutions, such as smart insulin pens and mobile health applications, provide patients with better disease management tools, increasing compliance with prescribed treatments. Additionally, pharmaceutical companies are integrating digital health platforms with diabetes medications to enhance patient engagement and improve therapeutic outcomes. As the healthcare industry continues to embrace digital transformation, the combination of technology and pharmaceuticals is expected to drive further growth in the Canadian diabetes drugs market.
Market Trends
Growing Demand for Innovative Therapies
The Canada diabetes drugs market is witnessing a shift towards novel treatment options that offer superior efficacy and improved patient outcomes. The increasing adoption of GLP-1 receptor agonists and SGLT2 inhibitors reflects a preference for advanced therapies with cardiovascular and renal benefits beyond glucose control. Additionally, the development of oral insulin and gene-based therapies is gaining momentum, aiming to enhance convenience and long-term disease management. As pharmaceutical companies continue to invest in research and development, the market is expected to see the introduction of more targeted and personalized treatment options that improve patient adherence and quality of life.
Emphasis on Preventive Care and Early Diagnosis
Preventive care and early diagnosis initiatives are gaining traction as healthcare providers focus on reducing the long-term burden of diabetes. For instance, public health campaigns like "Diabetes 360°" have led to a significant increase in routine screenings and early interventions, according to Diabetes Canada. These initiatives emphasize lifestyle modifications and pharmacological interventions to delay or prevent disease progression. Pharmaceutical companies are responding by expanding their product portfolios to include medications specifically designed for early-stage diabetes management, aligning with the growing emphasis on prevention and early diagnosis.
Rise in Combination Drug Therapies
Combination drug therapies are becoming a preferred choice for diabetes management due to their ability to address multiple disease mechanisms simultaneously. Fixed-dose combinations (FDCs) that integrate different classes of diabetes medications into a single formulation enhance glycemic control while minimizing side effects. For instance, a study by the Canadian Agency for Drugs and Technologies in Health (CADTH) reported that FDCs have significantly improved medication adherence among patients with complex diabetes profiles. As regulatory bodies continue to approve new FDCs, the market is expected to expand further in this direction.
Integration of Digital Health and Smart Diabetes Management
The integration of digital health solutions into diabetes management is transforming how patients monitor and control their condition. The rise of telemedicine, AI-powered analytics, and connected devices such as continuous glucose monitors (CGMs) and smart insulin pens has improved real-time disease tracking and medication adherence. These technologies enable healthcare providers to personalize treatment plans and offer remote consultations, enhancing patient engagement and clinical outcomes. Pharmaceutical companies are increasingly collaborating with digital health firms to develop integrated solutions that combine medication with data-driven insights, driving further innovation in the market.
Market Challenges Analysis
Regulatory Hurdles and Pricing Pressures
The Canada diabetes drugs market faces significant challenges due to stringent regulatory requirements and pricing pressures. Health Canada enforces rigorous approval processes to ensure the safety and efficacy of new diabetes treatments, often leading to lengthy timelines for drug approvals. Additionally, pharmaceutical companies must navigate complex pricing negotiations with provincial healthcare systems and private insurers, which can limit market access for innovative but high-cost therapies. The push for cost-containment measures, including price caps and formulary restrictions, further adds to the financial strain on drug manufacturers. These factors create barriers to the rapid commercialization of advanced diabetes medications, slowing down market growth.
Affordability and Access Disparities
Despite government subsidies and insurance coverage, affordability remains a challenge for many diabetes patients in Canada. High out-of-pocket costs for newer medications, such as GLP-1 receptor agonists and SGLT2 inhibitors, limit their accessibility, particularly for uninsured or underinsured individuals. For instance, patients in Alberta face higher out-of-pocket expenses compared to those in Ontario, as highlighted in a recent analysis of provincial healthcare systems. Furthermore, rural and remote communities face additional challenges due to limited healthcare infrastructure and pharmacy availability, making it harder for individuals to access essential diabetes medications. Addressing these accessibility issues requires collaborative efforts between government bodies, pharmaceutical companies, and healthcare providers to ensure equitable distribution of diabetes treatments across all patient demographics.
Market Opportunities
The Canada diabetes drugs market presents significant growth opportunities driven by advancements in treatment innovation and the increasing focus on personalized medicine. The rising adoption of GLP-1 receptor agonists, SGLT2 inhibitors, and combination therapies offers pharmaceutical companies the chance to expand their product portfolios with more effective and patient-friendly solutions. Additionally, the development of oral insulin and next-generation biologics is expected to enhance treatment adherence and convenience, further driving market demand. As precision medicine gains traction, integrating genetic profiling and AI-driven analytics into diabetes management will enable more tailored treatment approaches, improving patient outcomes and expanding market potential.
Another key opportunity lies in the expansion of digital health and remote patient monitoring solutions. The growing adoption of telemedicine, wearable glucose monitors, and smart insulin delivery systems is transforming diabetes care, creating opportunities for pharmaceutical companies to collaborate with tech firms in developing integrated treatment solutions. Government initiatives focused on early diagnosis, preventive care, and improved drug accessibility also provide a favorable environment for market growth. Expanding public reimbursement programs and fostering partnerships between healthcare providers and pharmaceutical companies can enhance treatment affordability and accessibility, especially in underserved regions. As healthcare policies continue to prioritize chronic disease management, the demand for innovative diabetes therapies in Canada is expected to rise, presenting long-term growth opportunities for market players.
Market Segmentation Analysis:
By Drug Class:
The Canada diabetes drugs market is categorized into several drug classes, including insulin, DPP-4 inhibitors, GLP-1 receptor agonists, SGLT2 inhibitors, and others. Insulin remains a cornerstone of diabetes treatment, particularly for type 1 and advanced type 2 diabetes patients. The increasing prevalence of insulin-dependent diabetes, along with advancements in long-acting and ultra-rapid insulin formulations, continues to drive demand. DPP-4 inhibitors, known for their ability to enhance insulin secretion with minimal hypoglycemia risk, remain a widely used option for type 2 diabetes management. GLP-1 receptor agonists are gaining traction due to their dual benefits of glycemic control and weight loss, making them a preferred choice for patients with obesity-related diabetes. Meanwhile, SGLT2 inhibitors have shown significant growth in the market due to their cardiovascular and renal protective benefits. The "others" category includes emerging therapies such as dual agonists and novel biologics, which are expected to contribute to market expansion as research and development efforts advance.
By Diabetes Types:
Diabetes in Canada is classified into multiple types, including type 1, type 2, and the less common diabetes types 3, 4, and 5. Type 1 diabetes, an autoimmune condition requiring lifelong insulin therapy, constitutes a significant share of the market, with ongoing innovation in insulin delivery systems driving demand. Type 2 diabetes, the most prevalent form, accounts for the largest segment, driven by lifestyle factors, an aging population, and rising obesity rates. The increasing adoption of combination therapies and novel drug classes such as GLP-1 receptor agonists and SGLT2 inhibitors is enhancing treatment options for type 2 diabetes patients. Diabetes types 3, 4, and 5, though less common, represent emerging areas of research and therapeutic development. These categories include conditions such as Alzheimer's-related diabetes (type 3), genetic and syndromic diabetes (type 4), and rare metabolic disorders linked to insulin resistance (type 5). Growing awareness and improved diagnostic techniques for these diabetes subtypes create new opportunities for targeted drug development and market expansion.
Segments:
Based on Drug Class:
- Insulin
- DPP-4 Inhibitors
- GLP-1 Receptor Agonists
- SGLT2 Inhibitors
- Others
Based on Diabetes Types:
- Type 1
- Type 2
- Diabetes Type 3
- Diabetes Type 4
- Diabetes Type 5
Based on Route of Administration:
- Oral
- Subcutaneous
- Intravenous
- Route of Administration 4
- Route of Administration 5
Based on Technology:
- Technology 1
- Technology 2
- Technology 3
Based on Distribution Channel:
- Online Pharmacies
- Hospital Pharmacies
- Retail Pharmacies
- Distribution Channel 4
- Distribution Channel 5
Based on the Geography:
- Ontario
- Quebec
- Western Canada
- British Columbia
- Atlantic Canada
Regional Analysis
Ontario
Ontario holds the largest share of the Canada diabetes drugs market, accounting for approximately 35% of total market revenue. This dominance is attributed to the province’s high population density, increasing prevalence of diabetes, and strong healthcare infrastructure. Ontario has a well-established public healthcare system that supports diabetes management through government-funded programs, ensuring broad access to medications. The growing adoption of advanced therapies, including GLP-1 receptor agonists and SGLT2 inhibitors, is driving market growth in the region. Additionally, Ontario’s research institutions and pharmaceutical collaborations contribute to the development and commercialization of innovative diabetes treatments. As digital health solutions gain traction, the province is witnessing increased integration of telemedicine and remote patient monitoring, further enhancing diabetes care.
Quebec
Quebec represents 25% of the Canada diabetes drugs market, making it the second-largest regional contributor. The province has a high prevalence of diabetes, driven by an aging population and lifestyle-related risk factors. Quebec’s healthcare system, supported by public insurance plans, provides comprehensive coverage for essential diabetes medications, boosting market accessibility. The region is also at the forefront of clinical research, with several pharmaceutical companies and research centers engaged in diabetes drug development. In recent years, the adoption of newer drug classes, such as GLP-1 receptor agonists and combination therapies, has increased significantly. Government initiatives focused on preventive healthcare and patient education are also playing a crucial role in promoting early diagnosis and effective disease management, further expanding market opportunities.
Western Canada
Western Canada, including Alberta, Saskatchewan, and Manitoba, holds a 20% market share in the diabetes drugs segment. The rising number of diabetes cases in this region is fueling demand for innovative treatment options. While insulin remains a staple therapy, the increasing awareness of SGLT2 inhibitors and DPP-4 inhibitors is driving their adoption among type 2 diabetes patients. Alberta, in particular, has a strong healthcare infrastructure and ongoing investment in digital health solutions, enhancing access to diabetes management tools. However, disparities in healthcare access between urban and rural populations pose challenges. Efforts to expand telehealth services and improve distribution channels for diabetes medications are expected to strengthen market growth in this region.
British Columbia & Atlantic Canada
British Columbia and Atlantic Canada collectively contribute 20% to the Canada diabetes drugs market. British Columbia benefits from a growing diabetic population and strong government support for chronic disease management. The province is witnessing increased demand for innovative therapies, including biosimilars and personalized treatment options. Meanwhile, Atlantic Canada, encompassing provinces such as Nova Scotia, New Brunswick, Prince Edward Island, and Newfoundland and Labrador, has a smaller but steadily growing market. Challenges such as limited healthcare accessibility in remote areas affect drug availability, but provincial healthcare programs and digital health adoption are improving patient care. As awareness and investment in diabetes management continue to rise, both British Columbia and Atlantic Canada are expected to see steady market growth in the coming years.
Key Player Analysis
- Novo Nordisk A/S
- Sanofi
- Merck & Co., Inc.
- Eli Lilly and Company
- AstraZeneca
- Takeda Pharmaceutical Company Limited
- Boehringer Ingelheim International GmbH
- Novartis AG
- Johnson & Johnson Services, Inc.
- Bayer AG
- Roche
- Medtronic
- Company 13
- Company 14
Competitive Analysis
The Canada diabetes drugs market is highly competitive, with key players such as Novo Nordisk, Sanofi, Merck & Co., Eli Lilly, AstraZeneca, Boehringer Ingelheim, Takeda Pharmaceutical, Novartis, Johnson & Johnson, Bayer, Roche, and Medtronic leading the industry. These companies focus on developing innovative diabetes treatments, including GLP-1 receptor agonists, SGLT2 inhibitors, and combination therapies, to improve patient outcomes and treatment adherence. Advanced therapies, such as GLP-1 receptor agonists and SGLT2 inhibitors, are driving market growth, while insulin remains a crucial treatment option for diabetes management. Companies are investing heavily in research and development to introduce improved drug formulations that enhance patient adherence and outcomes. In addition to drug development, competition is intensifying in digital diabetes management solutions, including continuous glucose monitoring systems and smart insulin delivery devices. Market players are forming partnerships with healthcare providers and technology firms to integrate AI-driven analytics and telemedicine into diabetes care. Pricing pressures and regulatory constraints remain significant challenges, influencing market access and affordability. However, with the increasing prevalence of diabetes and government initiatives supporting early diagnosis and preventive care, the market is expected to witness steady expansion in the coming years.
Recent Developments
- In March 2025, Novo Nordisk signed a deal worth up to $2 billion for the rights to UBT251, a new obesity and diabetes drug developed by United BioTechnology. The drug combines GLP-1, GIP, and glucagon to manage blood sugar and reduce hunger.
- In February 2025, Sanofi received FDA approval for MERILOG, the first rapid-acting insulin aspart biosimilar, to improve glycemic control in adults and pediatric patients with diabetes.
- In December 2024, JD Health began offering Merck's GLUCOPHAGE XR (Reduce Mass) online in China, enhancing access to metformin hydrochloride extended-release tablets for type 2 diabetes patients.
- In December 2024, Torrent Pharma acquired three diabetes brands from Boehringer Ingelheim, including those with Empagliflozin, to strengthen its anti-diabetes portfolio
- In November 2024, AstraZeneca presented promising early data for its obesity pipeline, including AZD5004, an oral GLP-1 receptor blocker, at ObesityWeek 2024.
Market Concentration & Characteristics
The Canada diabetes drugs market is characterized by a high level of concentration, with a few dominant players, including Novo Nordisk, Sanofi, Merck & Co., Eli Lilly, AstraZeneca, and Boehringer Ingelheim, holding a significant market share. These companies leverage strong research and development capabilities, extensive distribution networks, and regulatory expertise to maintain their competitive positions. The market is driven by continuous innovation, with a focus on advanced therapies such as GLP-1 receptor agonists, SGLT2 inhibitors, and combination treatments that offer enhanced efficacy and patient convenience. Market characteristics include strict regulatory oversight, high investment in clinical trials, and increasing demand for digital health solutions like continuous glucose monitoring (CGM) and smart insulin delivery systems. While pricing pressures and reimbursement challenges pose constraints, government initiatives supporting diabetes management and preventive care create growth opportunities. The market’s competitive landscape is shaped by strategic collaborations, patent expirations, and evolving treatment guidelines, ensuring ongoing advancements in diabetes care.
Report Coverage
The research report offers an in-depth analysis based on Drug Class, Diabetes Types, Route of Administration, Technology, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Canada diabetes drugs market will continue to grow, driven by rising diabetes prevalence and an aging population.
- Innovation in GLP-1 receptor agonists and SGLT2 inhibitors will enhance treatment effectiveness and patient adherence.
- Insulin advancements, including ultra-rapid and long-acting formulations, will improve diabetes management.
- Digital health solutions, such as continuous glucose monitoring and smart insulin delivery, will gain widespread adoption.
- Government initiatives and public health programs will strengthen early diagnosis and preventive care efforts.
- Pharmaceutical companies will invest in precision medicine and AI-driven analytics for personalized treatment approaches.
- Expanding telemedicine services will improve diabetes care accessibility, particularly in remote areas.
- Regulatory challenges and pricing pressures will continue to influence market dynamics and drug affordability.
- Strategic collaborations between pharmaceutical firms and technology providers will drive innovation and market expansion.
- The market will witness steady growth, supported by evolving treatment guidelines and improved patient awareness.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Diabetes and Aging Population
Canada is experiencing a steady increase in diabetes cases, driven by sedentary lifestyles, poor dietary habits, and an aging population. This expanding patient base is fueling demand for diabetes drugs and encouraging pharmaceutical companies to develop more effective treatments.
Advancements in Drug Development and Personalized Medicine
Innovative therapies such as GLP-1 receptor agonists and SGLT2 inhibitors are improving glycemic control and patient adherence, while precision medicine enables tailored treatment regimens. These advancements are attracting investment and expanding the range of available diabetes drugs in Canada.
Government Initiatives and Healthcare Funding
Supportive government policies, public reimbursement plans, and healthcare funding initiatives are enhancing access to diabetes medications. These efforts reduce the economic burden of diabetes and encourage the adoption of advanced therapies across the country.
Integration of Digital Health Solutions and Telemedicine
The adoption of digital health technologies, including telemedicine, remote monitoring, and AI-driven diagnostics, is improving disease management and treatment personalization. This integration is making diabetes care more accessible, especially in rural and underserved regions.
Shift Toward Combination Therapies
Combination drug therapies that address multiple disease mechanisms are gaining popularity for their enhanced efficacy and reduced side effects. The approval and adoption of fixed-dose combinations are improving medication adherence and expanding treatment options for Canadian patients.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Canada Diabetes Drugs Market?
What factors are driving the growth of the Canada Diabetes Drugs Market?
What are the key segments within the Canada Diabetes Drugs Market?
What are some challenges faced by the Canada Diabetes Drugs Market?
Who are the major players in the Canada Diabetes Drugs Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Drug Class
- 1.2.1 Insulin
- 1.2.2 DPP-4 Inhibitors
- 1.2.3 GLP-1 Receptor Agonists
- 1.2.4 SGLT2 Inhibitors
- 1.2.5 Others
- 1.3 By Diabetes Type
- 1.3.1 Type 1
- 1.3.2 Type 2
- 1.3.3 Diabetes Type 3
- 1.3.4 Diabetes Type 4
- 1.3.5 Diabetes Type 5
- 1.4 By Route of Administration
- 1.4.1 Oral
- 1.4.2 Subcutaneous
- 1.4.3 Intravenous
- 1.4.4 Route of Administration 4
- 1.4.5 Route of Administration 5
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 2,676.75 million → 2032: USD 3,473.89 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Canada Diabetes Drugs Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Canada Diabetes Drugs Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Canada Diabetes Drugs Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Canada Diabetes Drugs Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Canada Diabetes Drugs Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Canada Diabetes Drugs Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Canada Diabetes Drugs Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Canada Diabetes Drugs Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 2,676.75 million → 2032: USD 3,473.89 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Canada Diabetes Drugs Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Drug Class - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Insulin
- 12.3.7.2 DPP-4 Inhibitors
- 12.3.7.3 GLP-1 Receptor Agonists
- 12.3.7.4 SGLT2 Inhibitors
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Diabetes Type - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Type 1
- 12.4.7.2 Type 2
- 12.4.7.3 Diabetes Type 3
- 12.4.7.4 Diabetes Type 4
- 12.4.7.5 Diabetes Type 5
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Route of Administration - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Oral
- 12.5.7.2 Subcutaneous
- 12.5.7.3 Intravenous
- 12.5.7.4 Route of Administration 4
- 12.5.7.5 Route of Administration 5
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Canada Diabetes Drugs Geographic Market Outlook, 2023-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 Canada Diabetes Drugs Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2023-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Canada Diabetes Drugs Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2023
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2023-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Novo Nordisk
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Sanofi
- 17.4 Merck & Co.
- 17.5 Eli Lilly and Company
- 17.6 AstraZeneca
- 17.7 Boehringer Ingelheim
- 17.8 Takeda Pharmaceutical Company Limited
- 17.9 Roche
- 17.10 Johnson & Johnson
- 17.11 Bayer AG
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

