
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Canada Hyperscale Data Center Market Size 2023 | USD 2,972.08 Million |
| Canada Hyperscale Data Center Market, CAGR | 5.19% |
| Canada Hyperscale Data Center Market Size 2032 | USD 4,614.93 Million |
Market Overview
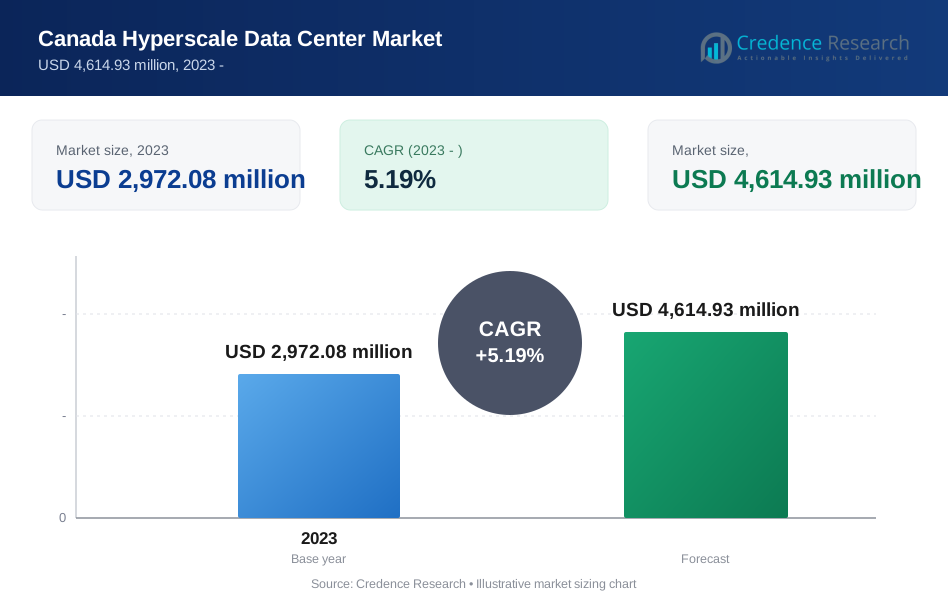
The Canada Hyperscale Data Center Market is projected to grow from USD 2,972.08 million in 2023 to an estimated USD 4,614.93 million by 2032, with a compound annual growth rate (CAGR) of 5.19% from 2024 to 2032. This growth is driven by the increasing demand for data storage and processing power due to the rise of cloud services, big data, and IoT technologies.
Key drivers influencing this market include the rapid adoption of digital transformation across industries, the growing need for data security and compliance, and advancements in data center technologies. Additionally, the demand for energy-efficient and sustainable data centers is driving innovation in cooling and power management solutions, contributing to market expansion.
Geographically, major investments are concentrated in regions like Ontario and Quebec, where access to renewable energy and favorable policies are attracting hyperscale data center developments. Key players in the Canada hyperscale data center market include Microsoft, Amazon Web Services (AWS), Google, IBM, and Oracle, who are investing heavily in expanding their infrastructure to meet the growing demand for cloud and data services. These companies are expected to maintain a dominant presence throughout the forecast period.
Market Drivers
Growing Demand for Cloud Computing and Data Services
The rapid growth in cloud computing adoption is one of the primary drivers of the Canada hyperscale data center market. As businesses across industries migrate their workloads to the cloud to enhance operational efficiency, reduce costs, and increase scalability, the need for large-scale data centers capable of handling vast amounts of data has surged. Hyperscale data centers, characterized by their ability to scale horizontally and efficiently manage large volumes of data and applications, have become essential for cloud service providers such as Amazon Web Services (AWS), Microsoft Azure, and Google Cloud. The Canadian market, in particular, has witnessed an increase in demand for cloud-based services due to the country’s growing tech sector, the rise of remote work, and the digital transformation initiatives across various industries. For instance, a report by Deloitte Canada highlights that despite barriers, the adoption of cloud technology in the Canadian public sector is accelerating, driven by the need for agility and rapid deployment of services.In addition, the increasing use of data-driven technologies such as artificial intelligence (AI), machine learning (ML), and big data analytics has further boosted the demand for cloud services. Companies in sectors such as finance, healthcare, retail, and government are adopting these technologies to improve decision-making processes and enhance customer experiences. The hyperscale data centers provide the infrastructure needed to support these applications, offering high computing power, scalability, and data storage capacity. As cloud adoption continues to accelerate, the demand for hyperscale data centers in Canada will expand significantly, driving growth in the market. According to a discussion paper by Innovation, Science and Economic Development Canada, embracing digital and data-driven technologies is critical for improving quality of life and driving productivity.
Rising Need for Data Security and Compliance
With the growing reliance on digital platforms and cloud-based services, ensuring data security and meeting regulatory compliance have become top priorities for businesses in Canada. Industries such as healthcare, finance, and government, which handle sensitive data, are particularly focused on securing their digital assets. The introduction of stringent data protection regulations, such as the Personal Information Protection and Electronic Documents Act (PIPEDA), has heightened the need for robust data storage solutions that ensure compliance with privacy and security requirements. For instance, the Digital Charter Implementation Act, 2022, introduced by the Government of Canada, aims to strengthen privacy laws and establish clear rules for the responsible development and use of AI.Hyperscale data centers are well-positioned to address these concerns, offering advanced security features such as encryption, multi-factor authentication, and real-time monitoring. These facilities also have the capacity to implement cutting-edge technologies to detect and mitigate cyber threats, ensuring that data stored in these centers remains secure. Additionally, hyperscale data centers provide businesses with the ability to store data locally, which is critical for organizations that must comply with regulations mandating that data remains within national borders. As regulatory frameworks evolve and cybersecurity threats become more sophisticated, the demand for hyperscale data centers with advanced security capabilities will continue to grow. According to Baker McKenzie, federal and provincial privacy laws in Canada regulate the way personal information can be collected, used, or disclosed, ensuring robust data protection.
Advancements in Data Center Technologies and Infrastructure
The Canada hyperscale data center market is also being driven by technological advancements that are enhancing the efficiency and performance of these facilities. Innovations in cooling technologies, power management, and server virtualization have significantly improved the operational efficiency of hyperscale data centers. For instance, advanced liquid cooling systems and immersion cooling techniques are being employed to manage the heat generated by the vast amounts of computing equipment in hyperscale facilities. These cooling solutions are not only more effective but also more energy-efficient, contributing to the growing focus on sustainability in the data center industry. According to ENCOR Advisors, the Canadian data center market is rapidly evolving, with significant investments in next-gen infrastructure and sustainable energy sources. Power management innovations, such as the use of renewable energy sources like hydroelectric and wind power, are also gaining traction in Canada. Hyperscale data centers are increasingly being built in regions where access to renewable energy is abundant, allowing operators to reduce their carbon footprint and adhere to sustainability goals. These advancements align with the global trend toward green data centers, as businesses and governments prioritize environmental responsibility. The integration of artificial intelligence and automation technologies in data center management has further streamlined operations, reducing downtime and optimizing resource allocation. These technological advancements are expected to fuel the expansion of hyperscale data centers in Canada, making them more efficient and sustainable. CBRE Canada reports that the North American data center market is seeing significant growth, driven by the adoption of cloud services and the need for advanced infrastructure.
Expansion of Digital Transformation and IoT Adoption
The ongoing digital transformation across various sectors in Canada is another significant driver of the hyperscale data center market. Businesses are increasingly adopting digital technologies to streamline operations, improve customer engagement, and gain a competitive edge. This shift has led to an exponential increase in the amount of data being generated, processed, and stored, necessitating the deployment of hyperscale data centers. The financial services, healthcare, retail, and manufacturing industries, in particular, are undergoing significant digital transformation efforts, leveraging technologies such as cloud computing, big data, AI, and automation. Additionally, the growing adoption of the Internet of Things (IoT) has contributed to the increased demand for hyperscale data centers. IoT devices generate massive amounts of data that require real-time processing and storage, placing a greater burden on existing data infrastructure. Hyperscale data centers, with their ability to scale rapidly and handle large volumes of data, are critical to supporting IoT applications in industries such as smart cities, transportation, and agriculture. As IoT adoption continues to expand, particularly with the rollout of 5G networks, the demand for hyperscale data centers in Canada is expected to rise.
Market Trends
Focus on Sustainability and Energy Efficiency
One of the most prominent trends in the Canada hyperscale data center market is the growing focus on sustainability and energy efficiency. With increasing awareness of environmental impact and stricter government regulations on carbon emissions, data center operators are prioritizing the use of renewable energy sources and energy-efficient technologies. Many hyperscale data centers in Canada are being built in regions with access to hydroelectric, wind, and solar power, allowing operators to significantly reduce their reliance on fossil fuels and lower their carbon footprint. For instance, a report by CBRE highlights that the Canadian data center market is rapidly evolving, with significant investments in next-gen infrastructure and sustainable energy sources. Additionally, there has been a surge in the adoption of advanced cooling technologies, such as liquid cooling and immersion cooling, which are more energy-efficient than traditional air-based systems. These innovations not only lower operational costs but also help data centers meet the growing demand for greener infrastructure. The shift toward sustainability is expected to remain a key trend, as data center operators seek to balance operational efficiency with environmental responsibility.
Increased Investment in Edge Computing and IoT
The rising demand for edge computing and the Internet of Things (IoT) is also shaping the Canada hyperscale data center market. As more devices become connected and the amount of data generated at the edge increases, there is a growing need for data centers that can process and store this data close to its source. Hyperscale data centers are adapting to this trend by investing in edge computing capabilities, allowing them to support low-latency applications and real-time data processing. For instance, a report by NMSC indicates that the Canadian data center market is witnessing widespread adoption of cloud services, alongside the emergence of edge computing to minimize latency. Industries such as healthcare, manufacturing, and transportation, which rely heavily on IoT devices, are driving this demand. The expansion of 5G networks is further accelerating the adoption of edge computing, as businesses look to leverage the higher speeds and lower latency to improve their operations. Hyperscale data centers are evolving to meet these needs by expanding their infrastructure and developing partnerships with telecom providers, ensuring they remain competitive in an increasingly decentralized data environment.
Market Restraints and Challenges
High Capital Investment and Operational Costs
One of the primary challenges in the Canada hyperscale data center market is the significant capital investment required for the construction and maintenance of these large-scale facilities. Building a hyperscale data center involves substantial costs related to land acquisition, infrastructure development, and the installation of advanced cooling, power, and networking technologies. Additionally, operational costs remain high due to the need for continuous power supply, cooling systems, and staffing to manage the data center operations. For instance, the North American data center market faces a shortage of available power and longer lead times for electrical infrastructure, which continue to delay construction completions. While hyperscale data centers benefit from economies of scale, the initial financial outlay can be a barrier for many companies looking to enter the market. Smaller businesses or new entrants may find it difficult to compete with established players like Amazon Web Services (AWS) and Google, who have the financial resources to invest in expanding their infrastructure. As a result, the high cost of capital investment and operational expenses poses a significant restraint to market growth.
Challenges in Energy Availability and Sustainability
Despite Canada’s abundance of renewable energy sources, ensuring a stable and continuous energy supply for hyperscale data centers presents a challenge. Hyperscale facilities consume vast amounts of electricity, and while many operators are investing in renewable energy solutions, the transition to fully sustainable energy sources can be complex and expensive. For instance, a strong demand for IT and increasingly high-density IT systems, along with the need to meet tough sustainability requirements, will drive a new wave of investment. Additionally, data center operators must navigate fluctuating energy prices, regional disparities in energy availability, and the limitations of existing power grids. Ensuring energy efficiency while maintaining the high levels of performance required by hyperscale operations is a continuous challenge. Furthermore, meeting government sustainability regulations and environmental standards adds another layer of complexity, as data center operators must invest in green technologies and carbon-reduction strategies. These challenges make it difficult for some data center providers to balance growth with sustainability goals, potentially slowing market expansion.
Market Segmentation Analysis
By Component
The Canada hyperscale data center market is segmented by component into two main categories: solutions and services. The solutions segment encompasses essential hardware and software technologies vital for data center operations, including servers for processing and managing workloads, scalable storage solutions that incorporate various technologies like SSDs and traditional HDDs, robust networking components to ensure seamless data flow and connectivity, and management software for optimizing operations and ensuring high availability. The services segment includes professional offerings that enhance data center functionality, such as consulting services that provide expert guidance on data center strategy design and optimization, efficient installation and deployment services that adhere to best practices and operational requirements, and ongoing maintenance and support services critical for reliability and issue resolution.
By End User
The end-user segment of the Canada hyperscale data center market comprises three main categories: cloud providers, colocation providers, and enterprises. Cloud providers are significant players, utilizing large data centers to deliver scalable cloud solutions to both businesses and consumers. Colocation providers offer shared data center services, enabling businesses to rent space and resources according to their needs. Additionally, enterprises are increasingly investing in their own hyperscale data centers to effectively manage their expanding data and application requirements.
Segments
Based on Component
- Solutions
- Servers
- Storage
- Networking
- Software
- Services
- Consulting
- Installation and Deployment
- Maintenance and Support
Based on End User
- Cloud Providers
- Colocation Providers
- Enterprises
Based on Data Center Size
- Small and Medium-Sized Data Centers
- Large Data Centers
Based on Industry
- Banking, Financial Services, and Insurance (BFSI)
- IT and Telecom
- Government and Defense
- Retail and Manufacturing
- Healthcare
- Media and Entertainment
- Others
Based on Region
- Ontario
- Quebec
- British Columbia
- Alberta
Regional Analysis
Ontario (45%)
Ontario holds the largest market share in the Canada hyperscale data center market, accounting for approximately 45%. The province's capital, Toronto, serves as a major hub for technology and financial services, driving demand for data center infrastructure. Ontario benefits from a robust energy grid, competitive electricity prices, and access to renewable energy sources. The region's established tech ecosystem attracts cloud providers and enterprises looking to expand their data storage capabilities. Moreover, the province’s favorable business environment and government incentives for green technology investments further enhance its appeal for hyperscale data center development.
Quebec (30%)
Quebec ranks second, contributing around 30% to the market share. The province is known for its abundance of hydroelectric power, which offers a cost-effective and sustainable energy source for data centers. Cities like Montreal have become attractive locations for hyperscale operators due to lower energy costs and a strong focus on environmental sustainability. Quebec's government has actively promoted data center investments, creating a favorable regulatory environment. This has led to increased interest from both domestic and international players seeking to leverage Quebec's unique energy advantages.
Key players
- Amazon Web Services, Inc.
- Cisco Systems, Inc.
- IBM Corporation
- Oracle Corporation
- Microsoft Corporation
- Google, Inc.
- Intel Corporation
- Meta Platforms Inc.
- NTT Communications Corporation
- Broadcom
- Schneider Electric
Competitive Analysis
The Canada hyperscale data center market is highly competitive, with key players leveraging their strengths to capture market share. Amazon Web Services (AWS) leads with its comprehensive cloud solutions and extensive global infrastructure, making it a preferred choice for enterprises. Microsoft Corporation follows closely, offering Azure’s robust services and strong hybrid cloud capabilities. Google, Inc. emphasizes innovation and efficiency, continually enhancing its data center technologies. IBM and Oracle provide specialized solutions targeting enterprise clients, focusing on data management and analytics. Cisco Systems and Intel are critical for their networking and hardware innovations that support data center performance. Meanwhile, Meta Platforms and NTT Communications drive advancements in scalability and connectivity. Broadcom and Schneider Electric contribute by enhancing operational efficiencies and energy management solutions. This competitive landscape is characterized by rapid technological advancements and a strong push towards sustainability.
Recent Developments
- In December 2023, AWS launched its second infrastructure region in Canada, the AWS Canada West (Calgary) Region, providing customers with more options to run workloads with greater resilience and availability.
- In August 2024, Cisco announced the general availability of Cisco Hypershield, a new AI-native security solution built within the Cisco Security Cloud.
- In March 2024, IBM published an overview of hyperscale data centers, highlighting their importance in handling large-scale workloads and advanced technologies.
- In December 2023, Oracle announced the opening of its first hyperscale cloud region in Colombia as part of its global expansion strategy.
- In November 2023, Microsoft announced a USD$500 million investment to expand its hyperscale cloud computing and AI infrastructure in Quebec, increasing its local cloud infrastructure footprint by 750 percent across Canada.
- In February 2024, Google announced significant investments in expanding its data center infrastructure to meet the growing demand for its services.
- In January 2024, Intel was highlighted as a leading player in the hyperscale data center market, with significant contributions to AI server market growth.
- In March 2024, Meta announced the development of two 24k GPU clusters to support AI workloads, as part of its ambitious infrastructure roadmap.
- In September 2021, NTT expanded its global data center footprint by 20%, including significant pre-leasing activity and investments in renewable energy.
- In October 2022, Broadcom announced the availability of the industry’s first open end-to-end networking solution optimized for Remote Direct Memory Access (RDMA) over converged Ethernet (RoCE).
Market Concentration and Characteristics
The Canada hyperscale data center market exhibits moderate concentration, with a few key players dominating the landscape while numerous smaller firms also participate. Major companies such as Amazon Web Services, Microsoft Corporation, and Google lead the market, leveraging their extensive resources and technological expertise to establish large-scale data centers across the country. These dominant players benefit from economies of scale, enabling them to offer competitive pricing and comprehensive service portfolios. Additionally, the market is characterized by a strong focus on innovation, particularly in energy efficiency and sustainability, as operators seek to reduce their carbon footprint and operational costs. Emerging players are increasingly entering the market, motivated by the growing demand for cloud services and data storage solutions. This dynamic environment fosters healthy competition, driving advancements in technology and infrastructure that meet the evolving needs of businesses and consumers alike.
Report Coverage
The research report offers an in-depth analysis based on Component, End User, Data Center Size, Industry and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Canada hyperscale data center market is expected to experience steady growth, with a projected compound annual growth rate (CAGR) of around 5.19% over the next several years. Increasing data consumption and the shift towards cloud computing will drive this growth.
- Operators are anticipated to increasingly integrate renewable energy sources into their power supply. This shift will not only help reduce carbon footprints but also align with global sustainability initiatives.
- The growing adoption of edge computing will create demand for localized data processing capabilities. This trend will necessitate the development of smaller, strategically located data centers to support real-time applications.
- As cyber threats continue to evolve, hyperscale data centers will prioritize advanced security measures. Investment in cybersecurity technologies and protocols will be essential to protect sensitive data and ensure compliance with regulations.
- The demand for energy-efficient cooling solutions is expected to rise, prompting innovation in cooling technologies. Advanced cooling systems, such as liquid cooling and immersion cooling, will become more prevalent in hyperscale facilities.
- Data center operators will increasingly leverage artificial intelligence and automation to optimize operations. These technologies will enhance resource management, reduce downtime, and improve overall efficiency.
- Sectors such as healthcare, finance, and retail will increasingly rely on hyperscale data centers for data storage and processing. This trend will drive further investments and expansions in data center infrastructure.
- The Canadian government is likely to continue offering incentives and support for data center development. Policies promoting digital infrastructure and sustainable practices will encourage more investments in the sector.
- As businesses grow and evolve, the need for scalable and flexible data center solutions will become paramount. Hyperscale operators will need to develop infrastructures that can easily adapt to changing business requirements.
- The Canadian hyperscale data center market will face increased competition from global players entering the market. Strategic partnerships between local and international companies will likely emerge to enhance service offerings and expand market reach.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Canada hyperscale data center market in 2023 and 2032?
What are the primary drivers of growth in the Canada hyperscale data center market?
How are Canadian hyperscale data centers addressing sustainability concerns?
What role does edge computing play in the future of the Canada hyperscale data center market?
Who are the major players in the Canada hyperscale data center market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Canada Hyperscale Data Center Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Canada Hyperscale Data Center Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (the forecast period) (2023: USD 2,972.08 million → forecast year: USD 4,614.93 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Canada Hyperscale Data Center Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Canada Hyperscale Data Center Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Canada Hyperscale Data Center Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Canada Hyperscale Data Center Market Drivers
- 3.3 Canada Hyperscale Data Center Market Restraints & Challenges
- 3.4 Canada Hyperscale Data Center Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Canada Hyperscale Data Center Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Canada Hyperscale Data Center Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Canada Hyperscale Data Center category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Canada Hyperscale Data Center Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Canada Hyperscale Data Center Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Canada Hyperscale Data Center market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Canada Hyperscale Data Center Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Canada Hyperscale Data Center Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Canada Hyperscale Data Center Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Canada Hyperscale Data Center (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Canada Hyperscale Data Center Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Canada Hyperscale Data Center Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Canada Hyperscale Data Center Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Canada Hyperscale Data Center Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Canada Hyperscale Data Center Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Canada Hyperscale Data Center Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Canada Hyperscale Data Center Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Canada Hyperscale Data Center Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Canada Hyperscale Data Center Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
