
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
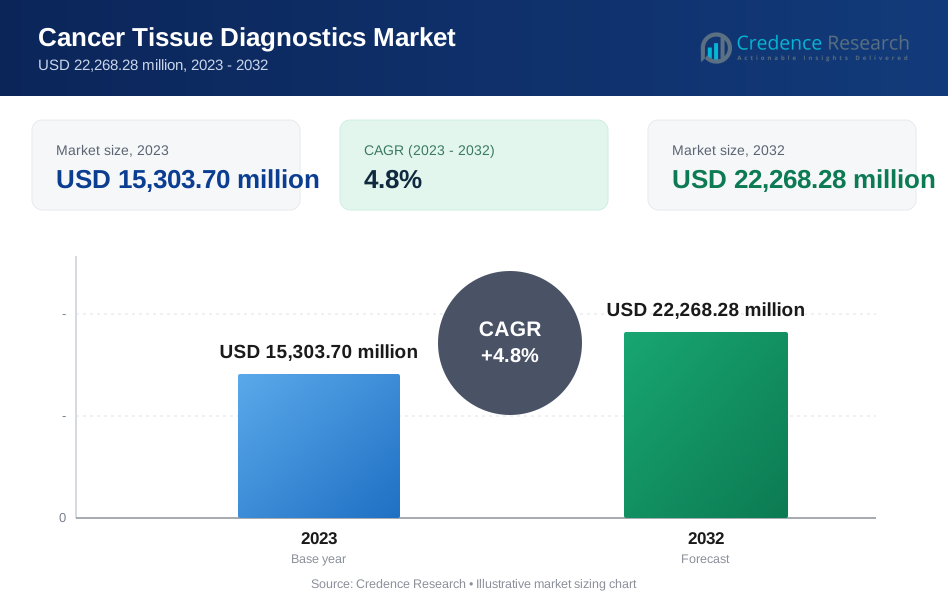
| Cancer Tissue Diagnostics Market Size 2023 | USD 15,303.70 Million |
| Cancer Tissue Diagnostics Market, CAGR | 4.8% |
| Cancer Tissue Diagnostics Market Size 2032 | USD 22,268.28 Million |
Market Overview
The Global Cancer Tissue Diagnostics Market is projected to grow from USD 15,303.70 million in 2023 to an estimated USD 22,268.28 million by 2032, with a compound annual growth rate (CAGR) of 4.8% from 2024 to 2032. This growth is driven by the increasing prevalence of cancer worldwide and the demand for advanced diagnostic solutions.
Key drivers include technological advancements in diagnostic techniques, such as immunohistochemistry and in situ hybridization, which enhance the accuracy and efficiency of cancer detection. Additionally, the rising awareness of early cancer detection and personalized medicine is propelling market expansion. The integration of artificial intelligence in diagnostic processes further contributes to improved patient outcomes.
Geographically, North America holds a significant share of the market due to its advanced healthcare infrastructure and high adoption of innovative diagnostic technologies. However, the Asia-Pacific region is anticipated to witness the highest growth rate during the forecast period, driven by increasing investments in healthcare infrastructure and a growing patient population. Key players in the market include Abbott Laboratories, F. Hoffmann-La Roche Ltd., Thermo Fisher Scientific Inc., and Bio-Rad Laboratories Inc., among others.
Market Drivers
Advancements in Diagnostic Technologies
Recent innovations in diagnostic methods have substantially enhanced the accuracy and efficiency of cancer detection. Techniques such as immunohistochemistry (IHC) and in situ hybridization (ISH) have become integral in identifying specific biomarkers, facilitating precise cancer subtyping and staging. The integration of digital pathology and artificial intelligence (AI) has further improved diagnostic capabilities by enabling high-throughput analysis and reducing human error. For instance, the integration of digital pathology utilizes high-resolution whole-slide imaging, allowing pathologists to review and analyze entire slides digitally, which enhances diagnostic accuracy and efficiency. AI algorithms are employed to assist in identifying specific biomarkers, such as Ki67 and PD-L1, which are crucial for determining cancer subtypes and staging.Moreover, the application of AI in diagnostic workflows has demonstrated substantial improvements in sensitivity and specificity. Studies have shown that AI can outperform traditional methods in detecting isolated tumor cells, thereby increasing the likelihood of early detection of metastasis. This capability is particularly vital given the rising global incidence of cancer, which underscores the urgent need for effective diagnostic solutions that facilitate timely interventions. These technological advancements have made cancer tissue diagnostics more reliable and accessible, thereby increasing their adoption in clinical settings.
Rising Global Cancer Incidence
The global prevalence of cancer is on the rise, with an estimated 10 million deaths worldwide in 2020, accounting for approximately one in every six deaths. This surge in cancer cases has heightened the demand for effective diagnostic solutions. Early detection through tissue diagnostics is crucial for improving patient outcomes, as it enables timely intervention and personalized treatment plans. The increasing burden of cancer underscores the need for advanced diagnostic tools to manage and treat the disease effectively.
Growing Awareness and Screening Initiatives
There is a global increase in awareness regarding the importance of early cancer detection. Public health campaigns and educational programs have emphasized the benefits of regular screening and prompt diagnosis. This heightened awareness has led to more individuals seeking diagnostic services, thereby driving the demand for cancer tissue diagnostics. Additionally, government initiatives and funding for cancer research have significantly increased, supporting the development and adoption of advanced diagnostic techniques.As more individuals seek screening and diagnostic services, the adoption of innovative technologies such as digital pathology and AI is becoming increasingly essential in clinical settings to meet this growing demand.
Advancements in Personalized Medicine
The shift towards personalized medicine has transformed cancer treatment approaches. Tailoring therapies based on individual genetic profiles requires precise diagnostic information, which is often obtained through tissue diagnostics. Techniques like next-generation sequencing (NGS) and molecular profiling provide detailed insights into tumor genetics, enabling clinicians to select the most effective treatment strategies. This trend towards personalized care has increased the reliance on accurate and comprehensive diagnostic methods, thereby propelling the growth of the cancer tissue diagnostics market.
Market Trends
Integration of Artificial Intelligence (AI) in Diagnostic Processes
The incorporation of AI into tissue diagnostics is enhancing the precision and efficiency of cancer detection. AI algorithms are being employed to analyze complex tissue samples, identifying patterns and anomalies that may be challenging for human pathologists to detect. This integration facilitates faster and more accurate diagnoses, leading to improved patient outcomes. For instance, researchers from the University of Cambridge have developed an AI system capable of detecting 13 types of cancers with a remarkable accuracy rate from tissue samples, showcasing the potential of AI to significantly improve diagnostic precision in oncology. Additionally, companies like Roche are integrating over 20 advanced AI algorithms into their digital pathology platforms, aiming to provide clinicians with high-value insights that can lead to targeted treatments and improved patient care. This trend indicates a shift towards more automated and reliable diagnostic processes, allowing pathologists to focus on complex cases while reducing the risk of human error.
Advancements in Liquid Biopsy Techniques
Liquid biopsy is emerging as a non-invasive alternative to traditional tissue biopsies, offering a less invasive method for cancer detection and monitoring. This technique involves analyzing blood samples to detect circulating tumor DNA (ctDNA) or other cancer-related biomarkers. For instance, Guardant Health's Shield test exemplifies this innovation by enabling the detection of ctDNA from blood samples, facilitating early cancer detection and personalized treatment strategies. The FDA's approval of various blood tests for hereditary cancer detection further underscores the growing importance of liquid biopsy in oncology. This approach not only minimizes patient discomfort but also allows for continuous monitoring of treatment responses, thus enhancing overall patient management in oncology.
Market Restraints and Challenges
High Cost and Limited Accessibility of Advanced Diagnostic Tools
The high cost of advanced cancer tissue diagnostic tools and procedures poses a significant restraint on the market. Sophisticated technologies like immunohistochemistry (IHC) and in situ hybridization (ISH) require substantial investment in equipment, reagents, and skilled personnel. This creates affordability issues, particularly in low- and middle-income countries, limiting the adoption of these tools. Additionally, disparities in healthcare infrastructure between developed and developing regions hinder the accessibility of these diagnostic solutions. As a result, patients in underserved areas may face delays or inaccuracies in cancer diagnosis, affecting treatment outcomes and overall market growth.
Stringent Regulatory and Compliance Requirements
The cancer tissue diagnostics market is highly regulated, with stringent requirements for product approvals and compliance with quality standards. Regulatory bodies such as the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA) enforce rigorous validation and approval processes, which often prolong the time-to-market for new diagnostic solutions. This creates challenges for companies, especially smaller players, to navigate complex regulatory landscapes and allocate substantial resources to meet compliance demands. Moreover, frequent changes in regulatory frameworks across different regions add an extra layer of complexity, making it difficult for manufacturers to maintain consistency in global operations. These hurdles contribute to increased costs and slow innovation, impacting market expansion.
Market Segmentation Analysis
By Test Type
The cancer tissue diagnostics market is segmented by test type, with breast cancer diagnostics leading with the largest market share of 50.45% in 2024 and anticipated to grow at the fastest CAGR. Techniques like immunohistochemistry (IHC) and in situ hybridization (ISH) are pivotal in detecting hormone receptors and HER2 status for breast cancer, specific biomarkers and genetic mutations for stomach (gastric) cancer, and tumor markers and genetic alterations for colorectal cancer, enabling early detection and personalized treatment strategies. In prostate cancer diagnostics, IHC assesses prostate-specific antigen (PSA) levels, while ISH detects gene fusions, aiding in distinguishing aggressive from indolent cases. Additionally, diagnostics for other cancers, such as lung, liver, and pancreatic, rely on these advanced techniques to enhance accuracy and efficiency, underscoring their critical role across various cancer types.
By In Situ Hybridization (ISH) Test
In situ hybridization (ISH) techniques play a crucial role in cancer diagnostics by detecting genetic alterations and guiding personalized treatment strategies. In breast cancer, ISH focuses on identifying HER2 gene amplification and other genetic markers, often in combination with immunohistochemistry (IHC), to enhance diagnostic precision. For non-small cell lung cancer (NSCLC), ISH helps identify critical mutations like EGFR and ALK rearrangements, supporting targeted therapies, particularly as NSCLC incidence rises. In bladder cancer, ISH detects genetic changes that improve diagnostic accuracy and prognosis, contributing to a deeper understanding of tumor biology. Beyond these, ISH is widely applied in cancers such as head and neck, esophageal, and gynecological types, where its ability to detect diverse genetic mutations underscores its versatility and importance in advancing cancer diagnostics across multiple malignancies.
Segments
Based on Test Type
- Breast Cancer
- Stomach (Gastric) Cancer
- Colorectal Cancer
- Prostate Cancer
- Others
Based on Situ Hybridization (ISH) Test
- Breast Cancer
- Non-Small Cell Lung Cancer (NSCLC)
- Bladder Cancer
- Others
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America (38.9%)
North America holds a significant share of the global market, accounting for approximately 38.9% in 2022. The region benefits from advanced healthcare systems, high adoption rates of innovative diagnostic technologies, and substantial investments in cancer research. The United States, in particular, leads in the development and implementation of cutting-edge diagnostic tools, contributing to its dominant position in the market.
Europe (30.1%)
Europe follows closely, with a market share of about 30.1% in 2022. The region boasts a robust healthcare infrastructure and a high incidence of cancer, driving the demand for effective diagnostic solutions. Countries like Germany and the United Kingdom are at the forefront, investing in research and development to enhance diagnostic capabilities.
Key players
- Abbott Laboratories
- Hoffmann-La Roche Ltd.
- Thermo Fisher Scientific Inc.
- Ventana Medical Systems, Inc.
- Bio-Rad Laboratories Inc.
- Enzo Life Sciences, Inc.
- Abcam plc.
- BioGenex
- Cell Signaling Technology, Inc.
- Agilent Technologies, Inc.
- PerkinElmer Inc.
- Bio SB
- Cancer Genetics Inc.
- Danaher Corporation
- Rosetta Genomics
- Nanoprobes, Inc.
- Creative-Biolabs
- Sigma-Aldrich Co., LLC
Competitive Analysis
The global cancer tissue diagnostics market is highly competitive, with leading companies focusing on technological advancements and strategic collaborations to enhance their market positions. F. Hoffmann-La Roche Ltd. and Thermo Fisher Scientific Inc. are at the forefront, offering a wide range of diagnostic solutions and investing in research and development to introduce innovative products. Abbott Laboratories and Agilent Technologies, Inc. are also significant players, providing specialized diagnostic tools and reagents. The market is characterized by mergers and acquisitions, such as Roche's acquisition of Foundation Medicine, Inc., aiming to expand genomic profiling capabilities. Additionally, companies are increasingly integrating artificial intelligence and digital pathology into their diagnostic platforms to improve accuracy and efficiency. This dynamic landscape underscores the importance of continuous innovation and strategic partnerships in maintaining a competitive edge in the market.
Recent Developments
- In July 2023, Abbott launched its new cancer diagnostic platform, which integrates advanced imaging technology and AI to enhance tissue analysis accuracy, aiming to provide faster and more reliable cancer diagnoses.
- In February 2024, Roche announced a partnership with PathAI to advance its digital pathology capabilities. This collaboration will focus on developing AI algorithms for Roche's navify Digital Pathology platform, enhancing diagnostic precision in cancer tissue analysis.
- In March 2023, Thermo Fisher launched a new line of tissue diagnostics products designed for high-throughput screening of cancer biomarkers, aimed at improving the efficiency of cancer research laboratories.
- In August 2023, Ventana introduced its latest automated staining system that enhances the efficiency of immunohistochemistry workflows, allowing pathologists to process more samples with increased accuracy.
- In January 2024, Bio-Rad expanded its portfolio with a new range of liquid biopsy assays designed for the detection of circulating tumor DNA (ctDNA), enabling non-invasive cancer monitoring.
- In February 2024, Cancer Genetics announced a strategic partnership with a leading pharmaceutical company to develop companion diagnostics for targeted therapies in oncology.
- In January 2024, Danaher acquired a diagnostic company focused on next-generation sequencing technologies to enhance its offerings in cancer genomics and tissue diagnostics.
- In April 2024, Creative-Biolabs announced the release of custom antibody services specifically tailored for cancer research applications.
Market Concentration and Characteristics
The Global Cancer Tissue Diagnostics Market is characterized by a moderate to high concentration, with several key players holding significant market shares. Companies such as Abbott Laboratories, F. Hoffmann-La Roche Ltd., Thermo Fisher Scientific Inc., and Bio-Rad Laboratories Inc. dominate the market, offering a wide range of diagnostic products and services. This concentration is driven by substantial investments in research and development, strategic mergers and acquisitions, and the continuous introduction of innovative diagnostic solutions. The market is also witnessing increased collaboration among industry leaders to enhance technological advancements and expand product portfolios, thereby strengthening their competitive positions. These dynamics contribute to a competitive landscape where leading companies continually strive to maintain and enhance their market presence.
Report Coverage
The research report offers an in-depth analysis based on Test Type, Situ Hybridization (ISH) Test and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Continuous innovations in diagnostic technologies, such as digital pathology and artificial intelligence integration, are enhancing diagnostic accuracy and efficiency.
- An increase in global cancer cases is amplifying the demand for effective diagnostic solutions.
- A shift towards individualized treatment plans is propelling the need for precise diagnostic tools.
- Enhanced funding and support for cancer research and diagnostic advancements are accelerating market growth.
- An aging demographic is contributing to a higher prevalence of cancer, thereby increasing diagnostic requirements.
- Developing regions are experiencing growth in healthcare infrastructure, expanding access to diagnostic services.
- The introduction of new diagnostic products and technologies is being facilitated by regulatory agencies, broadening market offerings.
- Partnerships between academic institutions and industry players are fostering innovation in diagnostic methods.
- Increased public awareness of cancer and its symptoms is leading to higher demand for diagnostic services.
- Advancements in diagnostic technologies are making cancer tissue diagnostics more affordable and accessible.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size of the Global Cancer Tissue Diagnostics Market in 2023 and 2032?
What are the key drivers of growth in the Global Cancer Tissue Diagnostics Market?
How is artificial intelligence influencing the cancer tissue diagnostics market?
Which region is expected to experience the highest growth in the cancer tissue diagnostics market?
Who are the key players in the Global Cancer Tissue Diagnostics Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Cancer Tissue Diagnostics Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Cancer Tissue Diagnostics Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 15,303.70 million → 2032: USD 22,268.28 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Cancer Tissue Diagnostics Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Cancer Tissue Diagnostics Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Cancer Tissue Diagnostics Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Cancer Tissue Diagnostics Market Drivers
- 3.3 Cancer Tissue Diagnostics Market Restraints & Challenges
- 3.4 Cancer Tissue Diagnostics Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Cancer Tissue Diagnostics Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Cancer Tissue Diagnostics Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Cancer Tissue Diagnostics category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Cancer Tissue Diagnostics Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Cancer Tissue Diagnostics Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Cancer Tissue Diagnostics market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Cancer Tissue Diagnostics Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Cancer Tissue Diagnostics Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Cancer Tissue Diagnostics Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Cancer Tissue Diagnostics (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Cancer Tissue Diagnostics Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Cancer Tissue Diagnostics Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Cancer Tissue Diagnostics Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Cancer Tissue Diagnostics Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Cancer Tissue Diagnostics Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Cancer Tissue Diagnostics Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Cancer Tissue Diagnostics Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Cancer Tissue Diagnostics Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Cancer Tissue Diagnostics Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
