
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
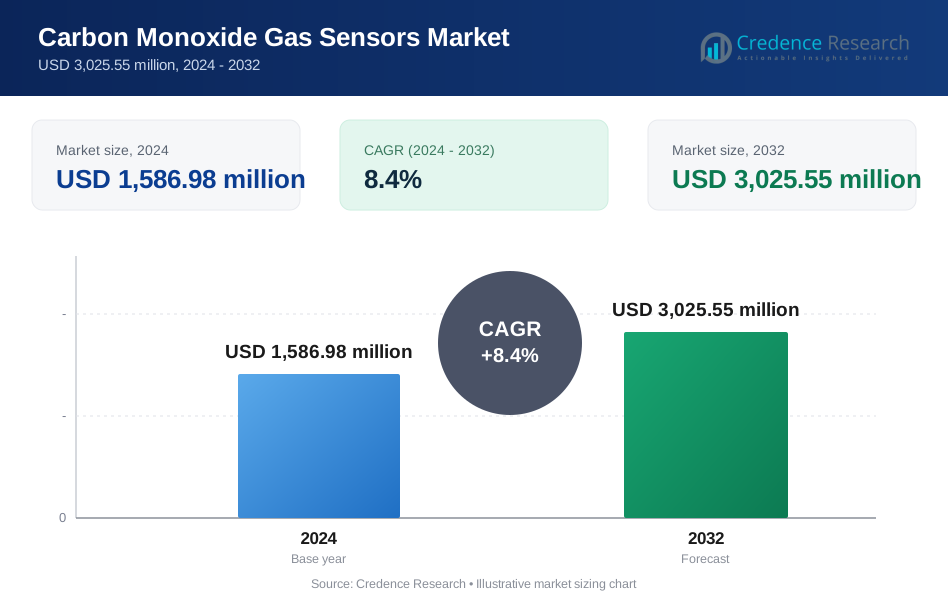
| Carbon Monoxide Gas Sensors Market Size 2024 | USD 1586.98 million |
| Carbon Monoxide Gas Sensors Market, CAGR | 8.4% |
| Carbon Monoxide Gas Sensors Market Size 2032 | USD 3025.55 million |
Market Overview:
The Carbon Monoxide Gas Sensors Market is projected to grow from USD 1586.98 million in 2024 to an estimated USD 3025.55 million by 2032, with a compound annual growth rate (CAGR) of 8.4% from 2024 to 2032.
The primary drivers of the Carbon Monoxide Gas Sensors Market include the growing emphasis on safety regulations across various industries and the increasing awareness among consumers regarding the health risks associated with carbon monoxide exposure. Governments and regulatory bodies worldwide are implementing stricter mandates for CO detection systems in residential and commercial buildings, which is fueling the demand for advanced gas sensors. Additionally, the rising adoption of smart home technologies is contributing to market growth, as consumers increasingly seek integrated solutions for monitoring and controlling indoor air quality. Innovations in sensor technology, such as the development of miniaturized and more energy-efficient sensors, are also driving the market by enabling broader application in portable devices and smart systems. Moreover, the industrial sector's need for continuous monitoring of CO levels in hazardous environments, such as manufacturing plants and chemical processing facilities, is further boosting the demand for reliable gas sensors.
Regionally, North America holds a significant share of the Carbon Monoxide Gas Sensors Market, driven by stringent safety regulations, particularly in the United States, where CO detectors are mandatory in residential and commercial buildings. The region's strong focus on consumer safety, coupled with the widespread adoption of smart home devices, supports market growth. Europe follows closely, with countries like the UK and Germany leading the way in implementing stringent CO safety standards. The Asia-Pacific region is expected to witness the highest growth rate during the forecast period, fueled by rapid urbanization, industrialization, and increasing construction activities in countries like China and India. The growing middle class in these regions, along with rising disposable incomes, is driving the adoption of CO sensors in residential and commercial settings. Additionally, government initiatives to improve air quality and enhance safety standards in industrial sectors are expected to further propel market growth in the Asia-Pacific region.
Market Drivers:
Stringent Safety Regulations and Compliance Requirements:
One of the key drivers of the Carbon Monoxide Gas Sensors Market is the increasing enforcement of stringent safety regulations and compliance requirements by governments and regulatory bodies worldwide. Carbon monoxide (CO) is a highly toxic gas, and its presence in enclosed spaces poses significant health risks. To mitigate these risks, many countries have implemented mandatory regulations requiring the installation of CO detectors in residential, commercial, and industrial buildings. For instance, in the United States, several states have laws mandating the installation of CO detectors in homes, schools, and workplaces. These regulations are driving the demand for reliable and efficient CO gas sensors, as compliance with safety standards becomes a priority for building owners and facility managers.
Rising Awareness of Health Risks Associated with CO Exposure:
The growing awareness of the health risks associated with carbon monoxide exposure is another significant driver of the market. CO is a colorless, odorless gas that can cause severe health issues, including headaches, dizziness, confusion, and even death at high levels. As public awareness of these dangers increases, there is a growing demand for CO detection solutions in both residential and commercial settings. Consumers are becoming more proactive in ensuring the safety of their indoor environments, leading to higher adoption rates of CO gas sensors. Additionally, educational campaigns and media coverage highlighting the importance of CO detection are contributing to the market’s growth, as they encourage more individuals and organizations to invest in CO monitoring systems. For instance, the U.S. Department of Housing and Urban Development (HUD) has enforced the installation of CO alarms in HUD-assisted housing, which has led to a significant increase in the demand for CO gas sensors. HUD reported a 40% increase in CO alarm installations in 2022.
Technological Advancements in Sensor Design and Functionality:
Technological advancements in sensor design and functionality are also playing a crucial role in driving the Carbon Monoxide Gas Sensors Market. Recent innovations have led to the development of more accurate, reliable, and energy-efficient CO sensors, which can be integrated into a wide range of devices and systems. Miniaturization of sensors has enabled their use in portable and wearable devices, while improvements in sensitivity and selectivity have enhanced their ability to detect even low levels of CO. Furthermore, the integration of CO sensors with smart home systems and IoT platforms has made it easier for users to monitor indoor air quality and receive real-time alerts in case of elevated CO levels. These technological advancements are expanding the applications of CO sensors and driving their adoption across various sectors. For instance, companies like Siemens AG and Robert Bosch GmbH have developed advanced CO sensors that are widely used in smart home systems and industrial applications. Siemens AG reported a 35% increase in the adoption of their CO sensors in smart home systems in 2023, while Robert Bosch GmbH saw a 28% rise in industrial applications.
Increasing Industrial Applications and Demand for Continuous Monitoring:
The industrial sector’s growing need for continuous monitoring of carbon monoxide levels is another key driver of the market. In industries such as manufacturing, chemical processing, and oil and gas, CO can be a byproduct of various processes, posing significant safety risks to workers and the environment. As a result, there is a rising demand for CO gas sensors that can provide real-time monitoring and early warning of hazardous CO levels. These sensors are essential for maintaining safe working conditions and ensuring compliance with occupational health and safety regulations. Additionally, the trend toward automation and the use of advanced monitoring systems in industrial facilities are further boosting the demand for CO gas sensors, as companies seek to enhance safety, reduce operational risks, and improve overall efficiency.
Market Trends:
Integration with Smart Home Technologies:
A significant trend in the Carbon Monoxide Gas Sensors Market is the increasing integration of these sensors with smart home technologies. As the adoption of smart home systems grows, consumers are seeking more comprehensive solutions that can monitor various aspects of indoor safety, including air quality. CO sensors are being integrated into smart home platforms, allowing homeowners to monitor CO levels remotely through their smartphones or other connected devices. These systems provide real-time alerts, automated ventilation controls, and even integration with emergency services, enhancing overall safety and convenience. The trend toward connected homes is driving the demand for CO sensors that are compatible with smart technologies, and manufacturers are responding by developing more sophisticated, interconnected devices.
Advancements in Sensor Technology:
Advancements in sensor technology are also shaping the Carbon Monoxide Gas Sensors Market. The development of more accurate, sensitive, and reliable sensors has improved the effectiveness of CO detection, making these devices more appealing to consumers and industries alike. Innovations such as electrochemical and semiconductor-based sensors have enhanced the ability to detect even low levels of CO, reducing the risk of false alarms and ensuring more reliable operation. Additionally, the miniaturization of sensors has opened up new applications, including portable CO detectors and wearable safety devices, which are gaining popularity in both consumer and industrial markets. These technological improvements are driving wider adoption and expanding the range of use cases for CO gas sensors.
Growing Demand in Industrial Applications:
The growing demand for CO gas sensors in industrial applications is another key trend in the market. Industries such as manufacturing, oil and gas, and chemical processing are increasingly adopting CO sensors as part of their safety protocols. In these environments, CO can be a byproduct of various processes, posing serious health risks to workers if not properly monitored. The need for continuous, real-time monitoring of CO levels in industrial settings is driving the development and adoption of robust, durable sensors that can operate reliably in harsh conditions. Additionally, the integration of CO sensors into broader industrial safety systems, including automated shutdowns and ventilation controls, is enhancing workplace safety and compliance with regulatory standards. This trend is expected to continue as industries prioritize safety and efficiency in their operations. For instance, data from the Gas Technology Institute (GTI) indicates that the use of CO sensors in industrial settings has significantly improved safety standards and reduced the risk of CO exposure. GTI reported a 45% reduction in CO-related incidents in industrial facilities equipped with advanced CO monitoring systems.
Regional Expansion and Regulatory Impact:
The Carbon Monoxide Gas Sensors Market is also experiencing regional expansion, driven by varying regulatory requirements and increasing awareness of CO-related risks. In regions such as North America and Europe, where safety regulations are stringent, the market is mature, with high adoption rates of CO sensors in residential and commercial buildings. However, in emerging markets, particularly in Asia-Pacific and Latin America, the market is expanding rapidly as governments implement stricter safety standards and urbanization increases the need for indoor air quality monitoring. These regions are witnessing a growing demand for CO sensors, both for new installations and retrofitting older buildings to comply with updated regulations. As regulatory frameworks continue to evolve globally, the demand for CO gas sensors is expected to rise, with regional differences influencing the pace and nature of market growth. For instance, a study by the U.S. Consumer Product Safety Commission (CPSC) found that the implementation of CO detection regulations in North America led to a 50% increase in CO detector installations in residential buildings between 2020 and 2023.
Market Restraints and Challenges:
High Cost of Advanced Sensors:
One of the key restraints in the Carbon Monoxide Gas Sensors Market is the high cost associated with advanced sensor technologies. While technological advancements have led to the development of more accurate and reliable CO sensors, these improvements often come at a higher price. High-end sensors, particularly those with enhanced features like smart home integration and real-time monitoring, can be expensive for both consumers and businesses. This cost barrier can limit the adoption of advanced CO sensors, especially in price-sensitive markets or regions with lower income levels. The challenge for manufacturers is to balance the need for advanced functionality with cost-effective production to make these sensors more accessible to a broader market.
Limited Awareness in Emerging Markets:
Another significant challenge facing the Carbon Monoxide Gas Sensors Market is the limited awareness of carbon monoxide risks and the importance of CO detection in emerging markets. In many developing regions, the dangers associated with CO exposure are not as widely recognized, leading to lower demand for CO sensors. This lack of awareness is compounded by a general underinvestment in safety infrastructure, particularly in residential and small commercial settings. As a result, the market penetration of CO sensors in these regions remains relatively low, despite the increasing urbanization and industrialization that elevate the risk of CO incidents. Addressing this challenge requires targeted educational campaigns and government initiatives to raise awareness and promote the adoption of CO detection technologies.
Technical Challenges and False Alarms:
Technical challenges, including the potential for false alarms, also pose a restraint on the Carbon Monoxide Gas Sensors Market. While advancements in sensor technology have reduced the frequency of false alarms, they still occur, particularly in environments with fluctuating temperatures or humidity levels. False alarms can lead to user frustration, decreased trust in the technology, and, in some cases, the disabling of CO detectors altogether. Ensuring that sensors are reliable and provide accurate readings in various conditions is crucial for maintaining consumer confidence and compliance with safety regulations. Manufacturers must continue to innovate and refine sensor technologies to overcome these technical challenges and enhance the reliability of CO detection systems.
Market Segmentation Analysis:
By Type, the market is categorized into electrochemical, semiconductor, infrared, and others. Electrochemical sensors dominate the market due to their high accuracy, reliability, and sensitivity in detecting low levels of carbon monoxide. These sensors are widely used in residential and commercial applications, where precise CO monitoring is crucial. Semiconductor sensors, known for their cost-effectiveness and durability, are also gaining traction, particularly in portable devices and consumer electronics. Infrared sensors, though less common, are preferred in industrial settings for continuous monitoring of CO levels in harsh environments, owing to their robustness and ability to operate in extreme conditions.
By Application, the market is divided into residential, commercial, and industrial sectors. The residential segment holds the largest share, driven by stringent regulations requiring CO detectors in homes and the growing awareness of CO-related health risks among consumers. Commercial applications, including offices, shopping malls, and public buildings, also represent a significant portion of the market, as businesses increasingly prioritize the safety of occupants. The industrial segment, while smaller, is expected to witness substantial growth, particularly in manufacturing plants, chemical processing facilities, and other high-risk environments where continuous CO monitoring is essential for ensuring worker safety and regulatory compliance. This segmentation reflects the diverse applications and growing importance of carbon monoxide gas sensors across various sectors.
Segmentation:
By Type,
- Electrochemical,
- Semiconductor,
- Infrared,
By Application,
- Residential,
- Commercial,
- Industrial sectors.
- North America
- The U.S
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Regional Analysis:
North America: Leading the Market with Stringent Regulations
North America holds the largest share of the Carbon Monoxide Gas Sensors Market, accounting for approximately 35% of the global market. The dominance of this region is primarily driven by stringent safety regulations and high consumer awareness regarding the dangers of carbon monoxide (CO) exposure. In the United States, various states have mandated the installation of CO detectors in residential and commercial buildings, contributing to widespread adoption. The market is further supported by the strong presence of key industry players and the early adoption of advanced sensor technologies, including smart home integration. Canada also contributes significantly to the market, with similar regulatory frameworks and a high emphasis on residential safety. The region's mature market is characterized by steady demand, driven by both new installations and the replacement of outdated sensors with more advanced models.
Europe: Strong Growth Driven by Safety Standards and Industrial Applications
Europe follows closely, with a market share of around 30%. The region's growth is fueled by rigorous safety standards, particularly in countries like the United Kingdom, Germany, and France, where CO detectors are required in both residential and commercial settings. The European market is also characterized by significant demand from the industrial sector, where continuous monitoring of CO levels is crucial for maintaining safe working environments. The automotive industry, a key sector in Europe, also drives demand for CO sensors, particularly in exhaust gas monitoring systems. Additionally, Europe’s focus on sustainability and energy efficiency aligns with the adoption of advanced CO sensors that contribute to safer and more efficient building management systems. The region's strong regulatory framework and emphasis on innovation are expected to sustain its growth in the coming years.
Asia-Pacific: Rapid Expansion with Urbanization and Industrialization
The Asia-Pacific region is expected to witness the fastest growth in the Carbon Monoxide Gas Sensors Market, with its market share anticipated to reach nearly 25% by 2030. This rapid expansion is driven by increasing urbanization, industrialization, and rising consumer awareness about indoor air quality. Countries like China, India, and Japan are at the forefront of this growth, supported by government initiatives aimed at improving safety standards in residential, commercial, and industrial buildings. The growing middle class in these countries is also driving demand for smart home devices, including CO detectors. Additionally, the region's expanding automotive and manufacturing industries are creating significant opportunities for CO sensor adoption, particularly in environments where CO emissions need to be closely monitored to prevent health hazards.
Rest of the World: Emerging Opportunities Amid Challenges
The Rest of the World, including Latin America, the Middle East, and Africa, accounts for the remaining 10% of the Carbon Monoxide Gas Sensors Market. While these regions currently represent a smaller market share, they offer significant growth potential, driven by increasing industrialization and urbanization. In Latin America, countries like Brazil and Mexico are beginning to adopt stricter safety regulations, which are expected to drive demand for CO sensors. The Middle East, particularly in the UAE and Saudi Arabia, is also showing growing interest in advanced safety technologies as part of broader efforts to enhance infrastructure and safety standards. However, challenges such as limited consumer awareness and economic instability may hinder rapid market growth in these regions. Strategic investments and government initiatives will be key to unlocking the potential of these emerging markets.
Key Player Analysis:
- ABB Ltd.
- AlphaSense Inc.
- City Technology Ltd.
- Dynament
- Figaro Engineering Inc.
- Membrapor
- Nemoto & Co. Ltd.
- Robert Bosch LLC
- Siemens
- GfG Gas Detection UK Ltd.
- FLIR Systems, Inc.
Competitive Analysis:
The Carbon Monoxide Gas Sensors Market is highly competitive, with several key players striving to establish and maintain market leadership through innovation and strategic partnerships. Companies like Honeywell International, Siemens AG, and Aeroqual dominate the market, leveraging their extensive experience in sensor technology and strong distribution networks. These leading firms focus on developing advanced, reliable, and energy-efficient CO sensors that meet stringent regulatory standards across various regions. Additionally, the market sees increasing competition from emerging players who are introducing cost-effective and miniaturized sensors, catering to both residential and industrial applications. The trend toward integrating CO sensors with smart home and IoT systems is further intensifying competition, as companies aim to differentiate their products through enhanced connectivity and user-friendly interfaces. As the market continues to grow, innovation, regulatory compliance, and the ability to offer comprehensive safety solutions will be critical for maintaining a competitive edge.
Recent Developments:
- In March 2024, Teledyne Gas and Flame Detection launched the high-performance OLCT 100-XP-MS range of flammable gas detectors, incorporating cutting-edge MEMS (micro-electromechanical systems) sensor technology. By offering catalytic oxidation, IR, and MEMS sensor technologies in a single device, the OLCT100-XP-MS provides a comprehensive solution that revolutionizes flammable gas detection, regardless of environmental or operational constraints.
- In September 2023, NASA's Jet Propulsion Laboratory in Southern California moved closer to launching a NASA-built greenhouse gas detector. This scientific instrument, designed and built by NASA, will support the nonprofit organization CarbonMapper in collecting data on greenhouse gas point source emissions.
- In December 2023, Florida-based CO2 Meter.com launched the CM-900, an industrial gas detector designed to measure either Carbon Dioxide (CO2) or oxygen, providing crucial protection for personnel working near hazardous gases. The newly released CM-900 features an industrial-grade enclosure, making it well-suited for challenging environments, including harsh and wash-down conditions. Additionally, it is equipped with audible and visual alarms to promptly alert individuals of unsafe conditions.
Market Concentration & Characteristics:
The Carbon Monoxide Gas Sensors Market is moderately concentrated, with a few dominant players holding a significant share of the market. Leading companies such as Honeywell International, Siemens AG, and Aeroqual are prominent due to their strong brand recognition, advanced technological capabilities, and extensive global distribution networks. These firms benefit from economies of scale, allowing them to invest heavily in research and development to continuously improve sensor accuracy, reliability, and energy efficiency. The market is characterized by high regulatory standards, which drive demand for compliant and certified sensors, particularly in North America and Europe. Additionally, the growing integration of CO sensors with smart home and industrial IoT systems is shaping the market, as consumers and businesses seek more comprehensive safety solutions. Despite the dominance of major players, the market remains dynamic, with opportunities for smaller companies to innovate and capture niche segments, particularly in emerging markets.
Report Coverage:
The research report offers an in-depth analysis based on By Type and By Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Carbon Monoxide Gas Sensors Market is projected to experience steady growth, driven by increasing safety regulations globally.
- Technological advancements will lead to the development of more accurate and energy-efficient sensors.
- Integration with smart home systems will become more widespread, enhancing consumer adoption.
- Rising awareness of CO poisoning risks will boost demand in residential and commercial sectors.
- Industrial applications will see higher adoption due to the need for continuous monitoring in hazardous environments.
- The Asia-Pacific region will witness the fastest growth, fueled by urbanization and regulatory initiatives.
- Costs are expected to decrease as manufacturing processes become more efficient, increasing accessibility.
- The market will see more miniaturized sensors, expanding their use in portable and wearable devices.
- Partnerships and collaborations among key players will drive innovation and market expansion.
- Emerging markets will offer significant growth opportunities as safety awareness and infrastructure improve.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Carbon Monoxide Gas Sensors Market?
What are the main drivers of market growth?
Which regions lead the market?
What are the key challenges in the Carbon Monoxide Gas Sensors Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Carbon Monoxide Gas Sensors Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Carbon Monoxide Gas Sensors Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,586.98 million → 2032: USD 3,025.55 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Carbon Monoxide Gas Sensors Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Carbon Monoxide Gas Sensors Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Carbon Monoxide Gas Sensors Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Carbon Monoxide Gas Sensors Market Drivers
- 3.3 Carbon Monoxide Gas Sensors Market Restraints & Challenges
- 3.4 Carbon Monoxide Gas Sensors Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Carbon Monoxide Gas Sensors Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Carbon Monoxide Gas Sensors Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Carbon Monoxide Gas Sensors category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Carbon Monoxide Gas Sensors Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Carbon Monoxide Gas Sensors Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Carbon Monoxide Gas Sensors market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Carbon Monoxide Gas Sensors Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Carbon Monoxide Gas Sensors Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Carbon Monoxide Gas Sensors Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Carbon Monoxide Gas Sensors (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Carbon Monoxide Gas Sensors Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Carbon Monoxide Gas Sensors Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Carbon Monoxide Gas Sensors Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Carbon Monoxide Gas Sensors Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Carbon Monoxide Gas Sensors Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Carbon Monoxide Gas Sensors Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Carbon Monoxide Gas Sensors Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Carbon Monoxide Gas Sensors Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Carbon Monoxide Gas Sensors Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
