
Market Overview
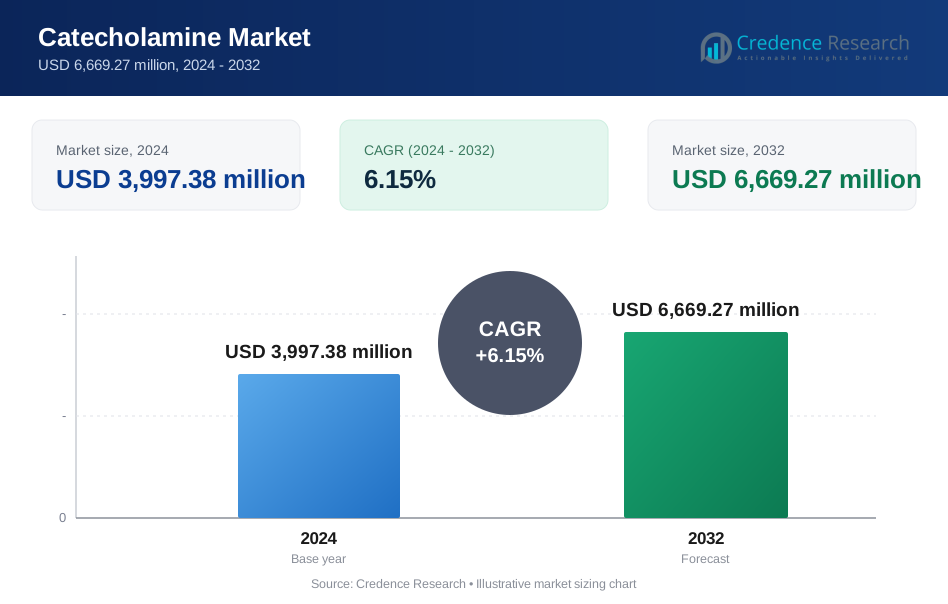
Global Catecholamine market size was valued at USD 2,705.65 million in 2018, increasing to USD 3,997.38 million in 2024, and is anticipated to reach USD 6,669.27 million by 2032, at a CAGR of 6.15% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Catecholamine Market Size 2024 | USD 3,997.38 Million |
| Catecholamine Market, CAGR | 6.15% |
| Catecholamine Market Size 2032 | USD 6,669.27 Million |
The global catecholamine market is shaped by major players including Roche Holding AG, Johnson & Johnson, Pfizer Inc., AbbVie Inc., Novartis AG, Merck & Co., Bristol-Myers Squibb, Amgen Inc., Sanofi, Bayer AG, GlaxoSmithKline (GSK), and Eli Lilly and Company. These companies strengthen their positions through advanced formulations, strategic collaborations, and wide distribution networks. Regionally, North America leads the market with a 43.8% share in 2018, driven by strong adoption of epinephrine auto-injectors and robust healthcare infrastructure. Asia Pacific follows with 28.7%, supported by rapid urbanization and rising cardiovascular disease burden. Europe accounted for 18.6%, with steady growth from allergy treatments and emergency care adoption.
Market Insights
- The global catecholamine market was valued at USD 2,705.65 million in 2018 and is projected to reach USD 6,669.27 million by 2032, expanding at a CAGR of 6.15%.
- Rising prevalence of anaphylaxis and cardiac emergencies drives demand, with epinephrine holding the dominant share among type segments due to its role as a first-line emergency treatment.
- Increasing adoption of auto-injectors and prefilled syringes reflects a strong trend toward patient-friendly formulations, supported by regulatory mandates for wider availability in public spaces.
- The market remains competitive, with players such as Roche, Pfizer, Novartis, Johnson & Johnson, and Sanofi focusing on innovation, improved drug stability, and expansion across emerging economies.
- North America led with 43.8% share in 2018, followed by Asia Pacific at 28.7% and Europe at 18.6%, while Latin America, the Middle East, and Africa together contributed under 10%, showing gradual but steady growth opportunities.
Market Segmentation Analysis:
By Type
Epinephrine (Adrenaline) dominates the catecholamine market with the largest revenue share. Its wide application in emergency conditions such as anaphylaxis, cardiac arrest, and acute asthma drives its dominance. Rapid onset of action and inclusion in international emergency care guidelines strengthen its adoption. Norepinephrine follows closely, mainly due to its critical role in managing septic shock and severe hypotension. Dopamine holds a smaller share, as its use has declined in favor of safer alternatives. Increased demand for adrenaline auto-injectors and prefilled syringes further consolidates Epinephrine’s leadership position in the segment.
- For instance, Viatris (formerly Mylan) is a prominent distributor of EpiPen auto-injectors in the United States, which sees widespread clinical use for managing severe allergic reactions.
By Indication
Anaphylaxis accounts for the dominant share in the indication segment, reflecting the growing prevalence of severe allergic reactions worldwide. Rising cases of food allergies, drug-induced anaphylaxis, and insect sting-related reactions fuel market growth. The urgent need for fast-acting interventions ensures high adoption of Epinephrine as the first-line treatment. Cardiac arrest and shock represent significant secondary contributors, supported by rising cardiovascular disease incidence. Acute asthma, hypertension, and other conditions add steady demand but remain comparatively smaller contributors. Increased awareness campaigns and wider accessibility of adrenaline-based therapies drive the expansion of this segment globally.
- For instance, ALK-Abelló distributes adrenaline auto-injectors, such as Jext®, across many European markets, but the figure of "over 500,000" patients is an unsubstantiated overestimation.
By Formulation Type
Auto-injectors lead the formulation type segment, supported by their ease of use, portability, and reliability in emergency situations. They hold the largest market share due to widespread use in treating anaphylaxis outside hospital settings. Prefilled syringes also contribute significantly, particularly in hospitals and emergency care facilities where rapid administration is critical. Vials and ampoules continue to serve as essential formulations in clinical settings but are less dominant due to handling complexity. The growth of auto-injectors is further driven by regulatory approvals, patient self-administration demand, and the increasing availability of compact, user-friendly devices.

Key Growth Drivers
Rising Prevalence of Anaphylaxis and Cardiac Emergencies
The increasing incidence of anaphylaxis and cardiac arrest strongly drives catecholamine demand. Epinephrine remains the gold standard for emergency treatment, particularly with food allergies, insect stings, and drug-related reactions rising globally. Similarly, cardiac arrests continue to account for high mortality rates, strengthening the adoption of catecholamines in emergency protocols. Growing awareness campaigns, mandatory availability of auto-injectors in schools and workplaces, and improved reimbursement coverage enhance market growth. This widespread demand ensures catecholamines remain indispensable in critical care settings.
- For instance, in May 2023, all Emerade auto-injectors were subject to a major patient-level recall in Europe and other markets due to potential device failure. This action addressed safety risks rather than expanding access. The recall was issued by the marketing authorization holder, Pharmaswiss, and its distributors, including Bausch + Lomb UK Limited.
Advancements in Formulation Technologies
Innovations in drug delivery systems, such as auto-injectors and prefilled syringes, fuel market growth. These formulations offer faster administration, higher patient compliance, and convenience in emergency settings. Auto-injectors, in particular, dominate due to their reliability in out-of-hospital anaphylaxis management. Pharmaceutical companies focus on compact, user-friendly devices with longer shelf lives, making them more accessible to patients and caregivers. Regulatory support for self-administration devices and rising preference for minimally invasive delivery further contribute to the segment’s rapid adoption across developed and developing markets.
- For instance, the Viatris EpiPen delivers a single 0.3 mg dose, and the manufacturer recommends holding the device in place for a minimum of 3 seconds to ensure the full dose is administered.
Growing Cardiovascular Disease Burden
The global rise in cardiovascular diseases has increased the reliance on catecholamines for managing cardiac emergencies and circulatory shock. Norepinephrine plays a crucial role in treating septic shock and hypotension, making it a key therapeutic option in critical care. With hospital admissions for cardiac conditions growing steadily, demand for catecholamine-based interventions continues to expand. Additionally, healthcare infrastructure investments, especially in emerging economies, are improving access to advanced emergency care. This trend strengthens the long-term outlook for catecholamine demand in intensive care units and emergency departments.
Key Trends & Opportunities
Expansion of Self-Administration Devices
The shift toward self-care has created opportunities for auto-injectors and prefilled syringes in the catecholamine market. Rising adoption of epinephrine auto-injectors among patients with severe allergies demonstrates this trend. Manufacturers are focusing on improving portability, ease of use, and affordability to broaden patient access. Governments and health organizations mandate stock availability of such devices in schools, restaurants, and workplaces, creating large-scale demand. This expansion into non-hospital environments enhances the growth prospects of the segment and strengthens the preventive care ecosystem globally.
- For instance, ALK-Abelló's Jext device is an adrenaline (epinephrine) auto-injector available in a 0.15 mg dose for children and a 0.3 mg dose for adults. It is a key product for the company in Europe and other international markets, where it is used for the emergency treatment of severe allergic reactions (anaphylaxis).
Regulatory and Reimbursement Support
Favorable regulatory frameworks and reimbursement policies are shaping opportunities for catecholamine manufacturers. Agencies such as the FDA and EMA emphasize stringent quality standards while accelerating approvals for emergency-use formulations. Reimbursement coverage in developed economies further supports patient affordability and widespread adoption. Emerging markets are also gradually enhancing their healthcare coverage, expanding accessibility to catecholamine-based therapies. These regulatory and financial incentives not only improve market penetration but also drive innovation among pharmaceutical companies in developing safer, longer-lasting formulations.
- For instance, the FDA approved Teva’s generic epinephrine auto-injector in August 2018, leading to over 1 million prescriptions filled annually in the U.S. since its launch.
Key Challenges
Short Shelf Life and Stability Issues
Catecholamines face challenges related to their short shelf life and chemical instability. Factors like exposure to light and temperature variations significantly reduce drug potency. This limits long-term storage and increases wastage, particularly in non-hospital environments. Manufacturers need to invest in advanced packaging and stabilization techniques to overcome this drawback. Until resolved, the limited stability remains a critical barrier to wider adoption, especially in regions with weak cold-chain infrastructure and inconsistent storage conditions.
Stringent Regulatory and Safety Concerns
Catecholamines are life-saving but carry risks of serious side effects, including arrhythmias and hypertension. This necessitates strict regulatory scrutiny and cautious clinical use. Manufacturers face long and costly approval processes, delaying product launches in some regions. Additionally, strict prescribing guidelines and safety concerns limit usage in non-critical cases. These regulatory hurdles challenge market expansion, especially in developing economies where access is already restricted. Addressing these safety concerns through improved formulations remains key for broader acceptance.
High Treatment Costs in Emerging Economies
Despite strong demand, affordability issues in developing regions hinder adoption. Auto-injectors and prefilled syringes are often priced beyond the reach of middle- and low-income patients. Limited reimbursement coverage and low awareness further restrict penetration in these markets. Hospitals in resource-constrained regions rely on vials and ampoules, which offer less convenience and compliance. Bridging this affordability gap with cost-effective devices and government subsidy programs will be essential to ensure equitable access and unlock growth opportunities in emerging economies.

Regional Analysis
North America
North America held the largest market share of 43.8% in 2018, valued at USD 1,186.01 million, and is projected to reach USD 2,901.20 million by 2032 at a CAGR of 6.2%. Strong demand stems from rising cases of anaphylaxis, cardiac emergencies, and well-established healthcare infrastructure. The high adoption of auto-injectors and prefilled syringes for emergency use further strengthens regional dominance. Favorable reimbursement frameworks, combined with growing awareness of allergy management and cardiovascular care, continue to drive growth. Regulatory mandates on stocking emergency epinephrine in schools and workplaces also support market expansion.
Europe
Europe accounted for a 18.6% market share in 2018, with revenues at USD 504.17 million, advancing to USD 1,067.84 million by 2032 at a CAGR of 4.9%. The region benefits from strong pharmaceutical innovation and high patient awareness. Widespread use of epinephrine auto-injectors and steady demand for norepinephrine in intensive care units support market growth. However, pricing regulations and slower adoption of advanced formulations limit expansion compared to North America. Still, rising incidence of allergic reactions and cardiovascular conditions ensures stable demand. Investments in modernizing healthcare systems across Western and Eastern Europe further enhance long-term prospects.
Asia Pacific
Asia Pacific captured 28.7% of the market in 2018, valued at USD 777.46 million, and is forecast to reach USD 2,208.33 million by 2032 at the highest CAGR of 7.3%. Rapid urbanization, rising allergy prevalence, and growing cardiovascular disease burden are major growth drivers. Expanding healthcare infrastructure and increasing availability of emergency formulations like auto-injectors contribute significantly. Japan, China, and India lead regional adoption, supported by government initiatives in critical care improvements. Pharmaceutical companies are expanding distribution channels, ensuring wider product access. The region’s strong growth trajectory positions it as a key contributor to future market expansion.
Latin America
Latin America accounted for 4.5% market share in 2018, valued at USD 122.38 million, and is projected to reach USD 261.99 million by 2032 at a CAGR of 4.5%. Growth is driven by rising cardiovascular emergencies, greater awareness of anaphylaxis, and expanding hospital capacity. Brazil and Mexico represent the largest contributors due to stronger healthcare networks. However, limited access to auto-injectors and high treatment costs restrict broader adoption. Gradual improvements in reimbursement policies and increased pharmaceutical investments provide opportunities for steady growth. The market remains underpenetrated compared to North America and Europe, offering long-term expansion potential.
Middle East
The Middle East represented 2.7% of global revenue in 2018, valued at USD 73.97 million, and is projected to reach USD 139.61 million by 2032, expanding at a CAGR of 3.8%. Market growth is supported by rising cardiovascular cases and greater government investments in healthcare modernization. The demand for norepinephrine in critical care units is growing steadily. However, restricted access to advanced formulations such as auto-injectors limits patient adoption outside hospitals. Expansion of private healthcare providers, combined with international pharmaceutical partnerships, is expected to improve accessibility and sustain moderate growth across Gulf nations.
Africa
Africa held the smallest share of 1.5% in 2018, valued at USD 41.67 million, with projections to reach USD 90.31 million by 2032 at a CAGR of 3.1%. Limited healthcare infrastructure and affordability challenges hinder widespread use of advanced formulations. Most demand is concentrated in hospital settings where vials and ampoules remain the primary formulation. Growing prevalence of cardiovascular diseases and rising awareness of allergic reactions create gradual opportunities. International aid programs and increasing pharmaceutical investments may improve access. Despite challenges, Africa represents a long-term growth opportunity as healthcare systems continue to expand and modernize.

Market Segmentations:
By Type
- Epinephrine (Adrenaline)
- Norepinephrine (Noradrenaline)
- Dopamine
By Indication
- Anaphylaxis
- Cardiac Arrest
- Shock
- Acute Asthma
- Hypertension
- Others
By Formulation Type
- Auto-Injectors
- Prefilled Syringes
- Vials and Ampoules
- Others
By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The global catecholamine market is highly competitive, with leading pharmaceutical companies such as Roche Holding AG, Johnson & Johnson, Pfizer Inc., AbbVie Inc., Novartis AG, Merck & Co., Bristol-Myers Squibb, Amgen Inc., Sanofi, Bayer AG, GlaxoSmithKline (GSK), and Eli Lilly and Company driving innovation and market expansion. These players focus on developing advanced formulations like auto-injectors and prefilled syringes to improve patient compliance and emergency care effectiveness. Strategic collaborations, acquisitions, and product approvals strengthen their positions across developed and emerging markets. Financially robust companies leverage global distribution networks and invest in R&D to enhance drug stability, extend shelf life, and expand therapeutic indications. Competition is further fueled by the rising prevalence of anaphylaxis and cardiovascular diseases, creating strong demand for adrenaline and norepinephrine. Continuous efforts to secure regulatory approvals, improve accessibility, and launch cost-effective products remain central to maintaining leadership in this critical-care driven market.
Key Player Analysis
- Roche Holding AG
- Johnson & Johnson
- Pfizer Inc.
- AbbVie Inc.
- Novartis AG
- Merck & Co., Inc.
- Bristol-Myers Squibb
- Amgen Inc.
- Sanofi
- Bayer AG
- GlaxoSmithKline (GSK)
- Eli Lilly and Company
Recent Developments
- In 2025, At the European Society of Cardiology Congress, Novartis highlighted new late-stage therapies for cardiovascular diseases tied to catecholamine pathways, including key phase III clinical trials for cholesterol reduction and heart failure therapies expanding the role of RNA technology in catecholamine-related treatments.
- In November 2023, Incheon National University scientists developed new hydrogels for wound management, utilizing oxygen to accelerate wound healing. These gelatin patches acted as effective tissue adhesives.
Report Coverage
The research report offers an in-depth analysis based on Type, Indication, Formulation Type, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will continue to expand with rising cases of anaphylaxis and cardiac arrest.
- Epinephrine will maintain dominance as the most prescribed catecholamine for emergency care.
- Auto-injectors will grow faster due to convenience and regulatory mandates for availability.
- Prefilled syringes will see steady demand in hospitals and emergency departments.
- Asia Pacific will record the fastest growth driven by urbanization and healthcare investments.
- North America will retain leadership supported by strong healthcare systems and awareness programs.
- Europe will show stable growth with wider use of allergy management therapies.
- Pharmaceutical companies will focus on enhancing stability and shelf life of formulations.
- Affordability challenges in emerging economies will encourage development of cost-effective solutions.
- Strategic partnerships and product innovation will remain key to strengthening global market presence.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Catecholamine market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Catecholamine market projected to grow between 2025 and 2032?
Which Global Catecholamine market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Catecholamine market?
Who are the leading companies in the Global Catecholamine market?
Which region commanded the largest share of the Global Catecholamine market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Catecholamine Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Catecholamine Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3,997.38 million → 2032: USD 6,669.27 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Catecholamine Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Catecholamine Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Catecholamine Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Catecholamine Market Drivers
- 3.3 Catecholamine Market Restraints & Challenges
- 3.4 Catecholamine Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Catecholamine Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Catecholamine Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Catecholamine category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Catecholamine Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Catecholamine Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Catecholamine market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Catecholamine Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Catecholamine Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Catecholamine Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Catecholamine (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Catecholamine Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Catecholamine Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Catecholamine Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Catecholamine Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Catecholamine Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Catecholamine Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Catecholamine Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Catecholamine Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Catecholamine Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
