
Cell Sorting Market Overview:
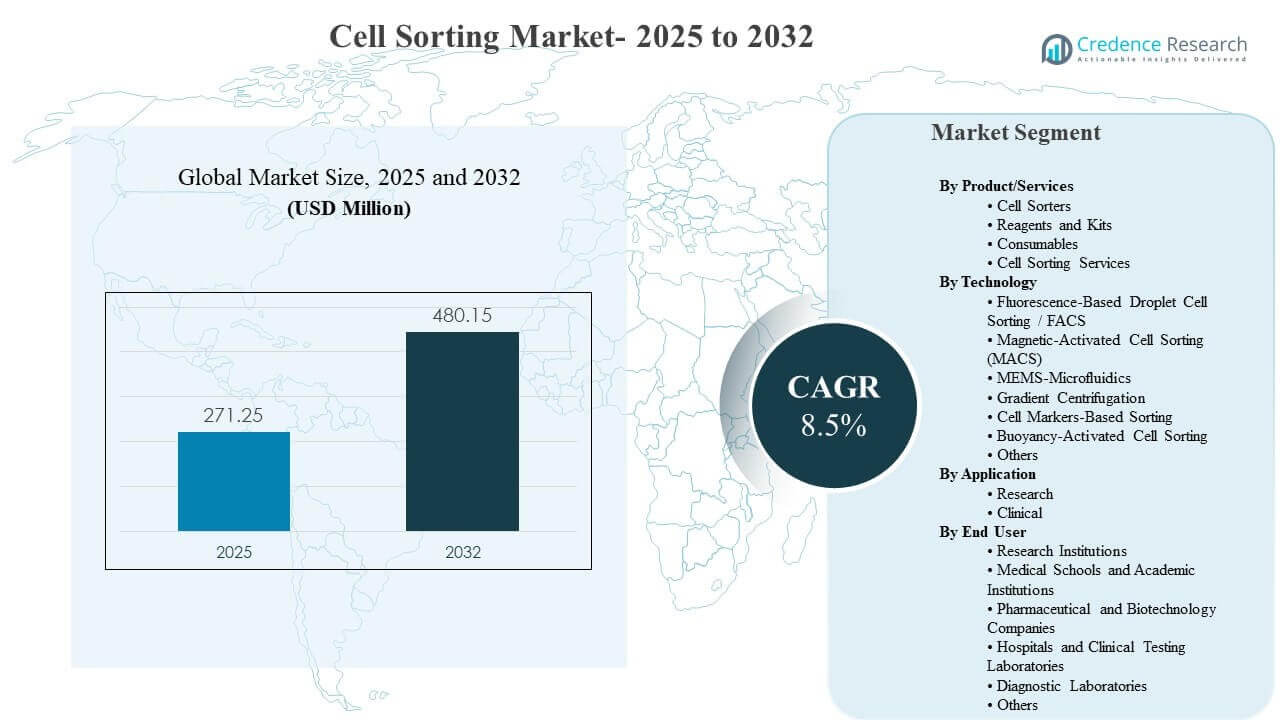
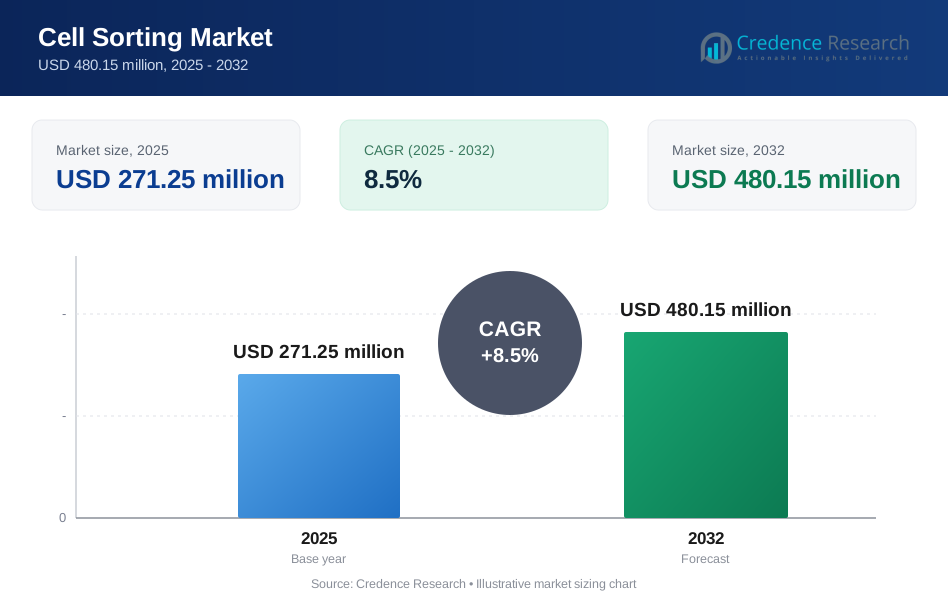
The global Cell Sorting Market size was estimated at USD 271.25 million in 2025 and is expected to reach USD 480.15 million by 2032, growing at a CAGR of 8.5% from 2025 to 2032. Growth is primarily driven by rising adoption of high-resolution cell isolation in immunology, oncology, and single-cell workflows, where improved sensitivity and throughput increase daily instrument utilization and recurring reagent pull-through. Asia Pacific expansion in research infrastructure and biopharma activity further strengthens demand for modern sorting platforms across academic cores and industry labs.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Cell Sorting Market Size 2025 | USD 271.25 million |
| Cell Sorting Market, CAGR | 8.5% |
| Cell Sorting Market Size 2032 | USD 480.15 million |
Key Market Trends & Insights
- The Cell Sorting Market is projected to expand from USD 271.25 million (2025) to USD 480.15 million (2032), reflecting an 8.5% CAGR (2025–2032).
- Reagents and consumables accounted for the largest product/service share of 58.5% in 2025, supported by recurring assay and panel requirements.
- Fluorescence-based droplet cell sorting / FACS held a 36.9% share in 2025, reflecting continued preference for multiparameter resolution and high-purity sorting.
- Research applications represented 56.4% in 2025, driven by sustained demand from immune profiling, stem cell research, and high-throughput discovery workflows.
- North America led with 36.2% share in 2025, reflecting a strong installed base and broad adoption across core facilities and biopharma laboratories.
Segment Analysis
Cell Sorting Market demand is anchored by recurring workflow consumption and the need for high-quality cell isolation across discovery and translational pipelines. Reagents, kits, and consumables sustain a large revenue base because antibody panels, dyes, beads, buffers, and single-use components are repeatedly purchased across experiments and projects. Instrument upgrades are influenced by throughput, sort purity, viability, and compatibility with downstream genomics and multiomics workflows. Service-based sorting demand is increasing where internal capacity is constrained or specialized expertise is required.
Technology choices depend on resolution needs, operating complexity, and workflow scale. FACS remains central in high-parameter phenotyping and rare-population sorting where multiparameter gating supports confident separation. Magnetic-based approaches gain adoption where rapid enrichment, simplified operation, or scalable sample preparation is required. Application pull remains research-led, with clinical use expanding as laboratories increase standardized workflows and build capabilities for regulated testing and advanced-therapy-related activities.
By Product/Services Insights
Reagents and Kits and Consumables accounted for the largest share of 58.5% in 2025. The Cell Sorting Market benefits from repeat purchasing cycles driven by routine staining, labeling, and enrichment steps. High-content panels and multi-color workflows increase per-sample reagent usage and encourage standardized purchasing across labs. Core facilities and multi-user environments sustain consistent consumable demand due to high daily instrument utilization.
By Technology Insights
Fluorescence-Based Droplet Cell Sorting / FACS accounted for the largest share of 36.9% in 2025. The Cell Sorting Market continues to rely on FACS for high-purity separation and multiparameter discrimination needed in immune profiling and rare-cell analysis. High-throughput sorting enables large experimental designs and accelerates discovery programs. System enhancements that improve stability, automation, and configuration flexibility support broader adoption across diverse lab sizes.
By Application Insights
Research accounted for the largest share of 56.4% in 2025. The Cell Sorting Market sees strong pull from single-cell studies, immuno-oncology research, and stem cell biology, where sorted populations improve downstream assay fidelity. Large research ecosystems prioritize versatile platforms that handle complex panels and rare events. Growing integration of sorting with genomics and proteomics workflows reinforces sustained research usage across institutions and biopharma labs.
By End User Insights
Research Institutions accounted for the largest share of 34.1% in 2025. The Cell Sorting Market is supported by centralized core facilities that concentrate expertise, maximize instrument utilization, and serve multiple research groups. Shared infrastructure models favor high-end systems with flexible configurations and consistent consumable demand. Collaboration-heavy environments increase sample volumes and promote adoption of standardized workflows for repeatability and cross-site comparability.
Cell Sorting Market Drivers
Expansion Of Single-Cell And Multiomics Research
Cell Sorting Market growth is supported by increasing use of single-cell genomics and multiomics workflows that require high-purity and viable cell populations. Research programs demand precise separation to reduce noise in downstream sequencing and functional assays. Core facilities prioritize platforms that can process diverse sample types and maintain stable performance across long runs. Higher sample throughput enables larger study designs, strengthening ongoing demand for instruments and recurring consumables.
Rising Immunology And Oncology Research Activity
Cell Sorting Market adoption increases as immunology and oncology programs expand cell phenotyping, immune monitoring, and functional assays. Rare immune subsets and tumor microenvironment studies require multiparameter discrimination and high-resolution sorting. Academic and biopharma labs allocate budgets toward systems that improve sort purity, viability, and workflow productivity. The shift toward complex panel design raises reagent pull-through and increases repeat purchasing across sustained research cycles.
- For instance, BD reports that the FACSymphony S6 is configurable for up to 50 detection parameters, can sort up to 6 resolved populations simultaneously, and can be customized with up to 9 spatially separated lasers, while its high-parameter cascade arrays support up to 20 parameters on a single laser line.
Growth In Biopharma R&D And Translational Pipelines
Cell Sorting Market demand benefits from growing biopharma R&D activity where cell isolation supports target discovery, screening, and assay development. Translational programs require consistent workflows to bridge early research and later-stage validation. Platforms that integrate automation and workflow standardization reduce operational variability across teams. Increasing reliance on specialized sorting for characterization and quality workflows expands instrument placements and strengthens recurring revenue from consumables and service support.
Technology Upgrades And Workflow Automation
Cell Sorting Market suppliers drive adoption through improvements in usability, automation, and configuration flexibility that broaden the addressable lab base. Automated startup, cleaning, and guided workflows reduce operator burden and increase daily utilization. Expanded configurations allow labs to match instrument capability to budget and assay complexity. Workflow integration with analysis tools and standardized consumables reduces friction, supporting upgrade cycles across academic cores and industry laboratories.
- For instance, Sony states that the MA900 supports 12 fluorescence parameters and 4-way sorting, automates startup, aseptic cleaning, QC, and sort setup, and with a 70 micrometer sorting chip at 52 kHz can achieve purity above 98% and recovery above 80% at a threshold rate of 12,000 events per second.
Cell Sorting Market Challenges
Cell Sorting Market expansion faces constraints from high capital cost, ongoing maintenance requirements, and the need for trained operators for advanced multiparameter workflows. Complex panel design and instrument optimization can increase setup time and introduce variability across sites. Procurement cycles can be prolonged in budget-constrained institutions, delaying replacement or upgrade decisions. Standardization needs in regulated environments add validation and documentation burden, increasing time-to-deployment for new workflows.
Cell Sorting Market participants also manage challenges linked to sample quality variability, throughput bottlenecks, and consumable supply dependency for high-frequency workflows. Sensitive samples can reduce viability during processing, affecting downstream assay performance and limiting adoption in some use cases. Data interpretation complexity increases with higher-dimensional panels, increasing reliance on specialized expertise and analytics. Competition across technology approaches can complicate purchasing decisions when multiple methods appear viable for enrichment workflows.
- For instance, Miltenyi Biotec’s MACSQuant Tyto Cell Sorter uses a fully closed single-use cartridge and operates at less than 3 psi, while delivering up to 55,000 cells per second, up to 30,000 valve actuations per second, greater than 99% purity, and greater than 99% viability for lymphocytes, showing how vendors are improving gentle sorting performance even as routine use remains dependent on cartridge-based consumables.
Cell Sorting Market Trends and Opportunities
Cell Sorting Market innovation is increasingly centered on higher-parameter analysis, improved sensitivity, and integration of real-time imaging or advanced detection capabilities. Platform differentiation is shifting toward workflow productivity, reduced contamination risk, and easier onboarding for new operators. Demand for flexible configurations supports broader adoption by smaller labs that require capability scaling without overspending. Integrated ecosystems that connect instruments, consumables, and software strengthen vendor stickiness and long-term account growth.
- For instance, BD Biosciences’ FACSDiscover S8 combines spectral flow cytometry with sort-capable real-time imaging through 5 lasers, 78 fluorescence detectors, 3 dedicated imaging detectors, and 12 derived image metrics for each imaging parameter, showing how vendors are raising both analytical depth and sort confidence in advanced cell characterization workflows.
Cell Sorting Market opportunity is expanding in service-based models as organizations outsource specialized sorting to reduce internal staffing pressure and improve turnaround times. Growth in translational research encourages adoption of standardized workflows that bridge discovery to applied settings. Asia Pacific investment in research infrastructure increases placement potential for modern systems and expands recurring reagent demand. Partnerships across workflow providers can accelerate adoption by bundling sample prep, sorting, and downstream analytics into cohesive solutions.
Regional Insights
North America
Cell Sorting Market leadership in North America is supported by a strong installed base across core facilities, large biopharma presence, and sustained research funding. North America represented 36.2% share in 2025, reflecting broad adoption of multiparameter sorting for immune profiling and high-throughput workflows. Demand is reinforced by frequent technology upgrades and strong recurring reagent usage in multi-user environments. Competitive intensity remains high as suppliers position differentiated platforms for complex research and translational needs.
Europe
Cell Sorting Market activity in Europe is shaped by established academic networks, collaborative research programs, and robust life science infrastructure. Europe held 21.4% share in 2025, supported by steady instrument utilization in centralized research cores and university-linked institutes. Focus on reproducibility and standard operating procedures sustains demand for standardized consumables and validated workflows. Supplier competition emphasizes reliability, service quality, and configuration flexibility for diverse research portfolios.
Asia Pacific
Cell Sorting Market momentum in Asia Pacific is reinforced by expanding research capacity, growing biopharma pipelines, and rising adoption of advanced cell analysis workflows. Asia Pacific reached 29.8% share in 2025, reflecting increasing placements and higher utilization across major research hubs. Growth is supported by investments in translational infrastructure and broader access to modern systems through flexible configurations. Expanding trained workforce and core facility development strengthens the region’s long-term demand profile.
Latin America
Cell Sorting Market development in Latin America continues as academic research activity broadens and specialized laboratories expand capabilities. Latin America accounted for 7.9% share in 2025, reflecting a smaller installed base compared with mature markets. Demand is concentrated in leading research centers where shared core facilities enable higher utilization. Gradual expansion of biopharma research and improved access to service support can strengthen adoption across priority countries.
Middle East & Africa
Cell Sorting Market adoption in the Middle East & Africa is driven by select research hubs and healthcare-linked laboratory development. Middle East & Africa represented 4.7% share in 2025, reflecting early-stage scaling in many countries. Growth is supported by targeted investments in biomedical research, talent development, and laboratory infrastructure modernization. Service-based access models and centralized facilities can accelerate adoption by reducing upfront cost barriers.
Competitive Landscape
Cell Sorting Market competition is shaped by continuous innovation in multiparameter capability, workflow automation, and integrated instrument–consumable ecosystems. Suppliers differentiate through performance in purity, viability, throughput, and stability, alongside software enhancements that improve usability and panel design support. Commercial strategies often combine system placements with recurring consumable pull-through and service contracts that strengthen lifetime value. Partnerships and workflow bundling further expand adoption by reducing complexity in end-to-end laboratory processes.
Becton, Dickinson and Company (BD) maintains a strong position in the Cell Sorting Market through broad cytometry workflow coverage and emphasis on expanding accessibility of advanced capabilities. BD platform development focuses on improving workflow productivity and enabling richer phenotyping through modern analysis approaches. Configuration breadth supports adoption across different lab sizes and budget levels. Strong service infrastructure and compatibility with recurring reagent workflows reinforce long-term customer retention and utilization intensity.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Becton, Dickinson and Company (BD)
- Bio-Rad Laboratories, Inc.
- Miltenyi Biotec
- Beckman Coulter, Inc.
- Sony Biotechnology
- Thermo Fisher Scientific Inc.
- Cytek Biosciences
- NanoCellect Biomedical
- Cytonome/ST
- Sysmex Corporation
- STEMCELL Technologies
- Merck KGaA
- On-Chip Biotechnologies
- Union Biometrica, Inc.
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Developments
| Report Attribute | Details |
| Market size value in 2025 | USD 271.25 million |
| Revenue forecast in 2032 | USD 480.15 million |
| Growth rate (CAGR) | 8.5% (2025–2032) |
| Base year | 2025 |
| Forecast period | 2026-2032 |
| Quantitative units | USD million |
| Segments covered | By Product/Services Outlook: Cell Sorters, Reagents and Kits, Consumables, Cell Sorting Services; By Technology Outlook: Fluorescence-Based Droplet Cell Sorting / FACS, Magnetic-Activated Cell Sorting (MACS), MEMS-Microfluidics, Gradient Centrifugation, Cell Markers-Based Sorting, Buoyancy-Activated Cell Sorting, Others; By Application Outlook: Research, Clinical; By End User Outlook: Research Institutions, Medical Schools and Academic Institutions, Pharmaceutical and Biotechnology Companies, Hospitals and Clinical Testing Laboratories, Diagnostic Laboratories, Others |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Key companies profiled | Becton, Dickinson and Company (BD); Bio-Rad Laboratories, Inc.; Miltenyi Biotec; Beckman Coulter, Inc.; Sony Biotechnology; Thermo Fisher Scientific Inc.; Cytek Biosciences; NanoCellect Biomedical; Cytonome/ST; Sysmex Corporation; STEMCELL Technologies; Merck KGaA; On-Chip Biotechnologies; Union Biometrica, Inc. |
| No.of Pages | 334 |
Segmentation
By Product/Services
- Cell Sorters
- Reagents and Kits
- Consumables
- Cell Sorting Services
By Technology
- Fluorescence-Based Droplet Cell Sorting / FACS
- Magnetic-Activated Cell Sorting (MACS)
- MEMS-Microfluidics
- Gradient Centrifugation
- Cell Markers-Based Sorting
- Buoyancy-Activated Cell Sorting
- Others
By Application
- Research
- Clinical
By End User
- Research Institutions
- Medical Schools and Academic Institutions
- Pharmaceutical and Biotechnology Companies
- Hospitals and Clinical Testing Laboratories
- Diagnostic Laboratories
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size and forecast for the Cell Sorting Market?
What is the CAGR for the Cell Sorting Market during 2025–2032?
Which segment holds the largest share in the Cell Sorting Market?
What are the main factors driving growth in the Cell Sorting Market?
Which companies are leading in the Cell Sorting Market?
Which region leads the Cell Sorting Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 271.25 million → 2032: USD 480.15 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2025
- 2.6.2 Forecast Period: 2025-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Cell Sorting Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Cell Sorting Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2025-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2025-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Cell Sorting Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2025-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Cell Sorting Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Cell Sorting Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Cell Sorting Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Cell Sorting Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Cell Sorting Market Outlook, 2025-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 271.25 million → 2032: USD 480.15 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Cell Sorting Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Cell Sorting Geographic Market Outlook, 2025-2032
- 13.1 Regional Market Size and Share, 2025
- 13.2 Regional Market Forecast, 2025-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Cell Sorting Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Cell Sorting Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

