
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Cement Market Size 2023 | USD 405,631.23 Million |
| Cement Market, CAGR | 4.50% |
| Cement Market Size 2032 | USD 602,806.60 Million |
Market Overview
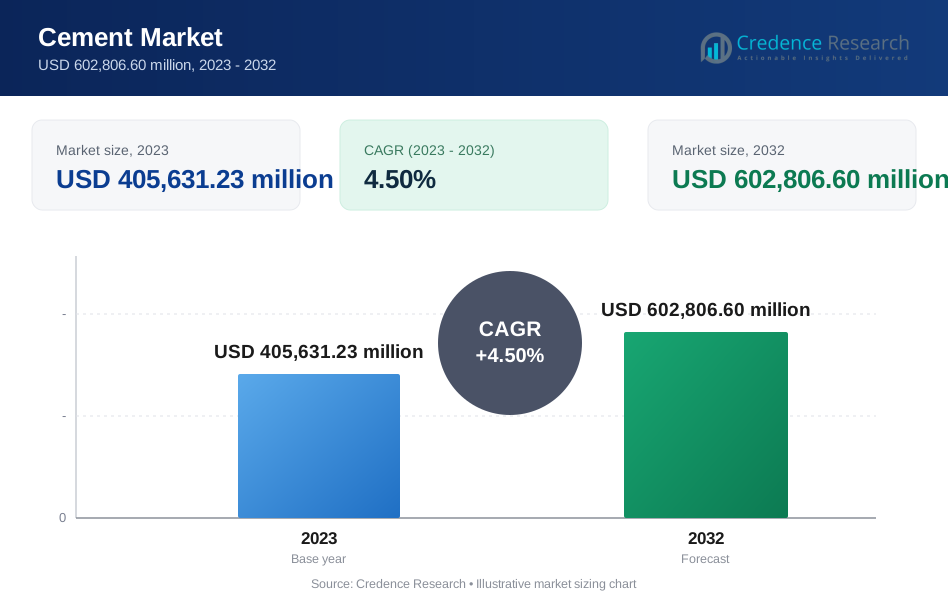
The global Cement Market is projected to grow from USD 405,631.23 million in 2023 to an estimated USD 602,806.60 million by 2032, with a compound annual growth rate (CAGR) of 4.50% from 2024 to 2032. This growth reflects the ongoing demand for cement in both residential and commercial construction sectors worldwide.
Several key drivers are propelling the global cement market's growth, including rising infrastructure investments, government initiatives for affordable housing, and the growing construction activities in both developing and developed regions. The demand for low-carbon and energy-efficient cement, driven by global sustainability goals, is a notable trend that is reshaping the industry. Additionally, innovations such as green cement and alternative raw materials are gaining traction, aligning with environmental mandates and consumer preferences for sustainable building solutions.
Geographically, the Asia-Pacific region dominates the cement market due to rapid urbanization and industrialization, especially in countries like China and India. North America and Europe are also experiencing steady growth, primarily driven by increasing investments in infrastructure modernization and sustainable construction practices. Key players in the market include LafargeHolcim, Anhui Conch Cement, HeidelbergCement AG, and China National Building Material Company, who continue to focus on expanding production capacities, investing in R&D, and adopting innovative materials to maintain a competitive edge.
Market Drivers
Rapid Urbanization and Infrastructure Development:
The global cement market is significantly driven by the rapid urbanization and infrastructure development witnessed across various regions, especially in emerging economies. As people continue to migrate from rural to urban areas, the demand for housing, commercial spaces, and improved public infrastructure increases correspondingly. Developing countries, in particular, are experiencing a construction boom, requiring vast quantities of cement for roads, bridges, schools, hospitals, and residential complexes. For instance, according to the United Nations, the number of megacities (cities with over 10 million inhabitants) is projected to increase from 33 in 2018 to 43 by 2030, with most of this growth occurring in developing regions. This rapid urbanization is driving massive demand for cement and concrete to build the necessary infrastructure and housing. Urbanization not only necessitates housing but also extends to supporting infrastructure such as transportation, utilities, and waste management systems, all of which rely heavily on cement as a foundational material. The trend towards smart cities and urban redevelopment projects further strengthens demand, encouraging market growth as governments and private sectors invest in sustainable, long-lasting construction.
Government Initiatives and Investments in Affordable Housing:
Government initiatives focused on affordable housing and infrastructure development play a crucial role in driving the global cement market. In regions like Asia-Pacific, Africa, and parts of Latin America, governments are actively promoting large-scale housing programs aimed at improving living standards and accommodating growing populations. These initiatives often encompass affordable housing schemes, rural development projects, and low-cost housing programs. In India, for instance, the "Pradhan Mantri Awas Yojana" aims to provide housing for all by 2022, creating a substantial demand for cement. Similar programs are found in many countries where governments partner with private sectors to meet housing needs. Such initiatives directly boost cement demand, especially when governments allocate funding for new housing developments, infrastructure upgrades, and rural revitalization. This driver is especially relevant in countries where affordable housing is prioritized as a means of supporting economic growth and social welfare.
Increased Focus on Sustainable Construction Practices:
The rising emphasis on sustainability within the construction industry is another critical driver for the cement market. As global awareness of environmental concerns grows, more countries and companies are adopting sustainable practices and eco-friendly construction materials. Cement production is traditionally a high-carbon process, but recent advancements have introduced low-carbon cement, alternative fuels, and energy-efficient production techniques. The demand for green cement, in particular, is rising as construction companies aim to reduce their carbon footprint and adhere to environmental regulations. Innovations such as carbon capture and storage (CCS) technologies, the use of waste materials as alternative raw ingredients, and clinker substitution are gradually transforming cement manufacturing processes. Consumers and governments alike are pushing for stricter environmental standards, and cement manufacturers are responding with sustainable options. This shift toward green cement not only meets regulatory requirements but also aligns with consumer demand for more responsible construction materials, reinforcing the long-term growth of the market.
Growing Construction Activities in Developing Regions: Developing regions, especially in Asia-Pacific, the Middle East, and Africa, are seeing a surge in construction activity, which is a key driver for cement demand. Rapid industrialization in these areas is leading to the construction of factories, warehouses, office buildings, and related infrastructure, creating a heightened demand for cement. Additionally, these regions are focusing on improving public infrastructure, including transportation networks, power generation facilities, and water management systems. The Belt and Road Initiative (BRI) in China, for example, is a multi-country infrastructure development project that has fueled massive cement demand, as China builds roads, ports, and railways in partner nations. Similarly, infrastructure projects in Africa, backed by both public and private investments, have intensified cement consumption. With industrialization being an economic priority for developing regions, investments in manufacturing and infrastructure have created significant opportunities for cement producers.
Market Trends
Shift Towards Green Cement and Sustainable Practices
A major trend in the global cement market is the increasing adoption of green cement and sustainable manufacturing practices. Cement production has historically been a significant source of carbon emissions, prompting the industry to explore environmentally friendly alternatives. Companies are investing in innovations that reduce carbon footprint, including carbon capture and storage (CCS) technologies, alternative fuels, and low-carbon production methods. The shift toward green cement—produced using lower energy consumption and alternative raw materials—is becoming more prevalent as construction firms strive to align with global sustainability goals and meet stringent environmental regulations. This trend is further driven by government policies encouraging green construction and by growing consumer preference for eco-friendly buildings. Additionally, the adoption of circular economy practices, such as recycling construction waste and utilizing industrial by-products as raw materials in cement production, is gaining traction. The commitment to sustainable development is pushing cement manufacturers to prioritize green cement in their product portfolios, making it a prominent growth area in the market.
Increased Technological Advancements and Digital Transformation
Technological advancements are reshaping the global cement industry, with companies increasingly integrating digital tools and automation in production and operational processes. Digital transformation, including the use of data analytics, artificial intelligence, and the Internet of Things (IoT), is enhancing process optimization, reducing operational costs, and improving efficiency in cement plants. Real-time monitoring and predictive maintenance systems are helping manufacturers prevent equipment downtime and extend machinery life, ultimately boosting productivity. For instance, a major cement manufacturer implemented an AI-driven predictive maintenance system that reduced unplanned downtime by 30%, saving approximately 720 hours of production time annually. Additionally, automation in cement production has enabled more precise control over raw material mixing, reducing energy consumption and minimizing waste. Industry players are also adopting blockchain technology for enhanced transparency in supply chains, improving traceability, and ensuring quality consistency. The implementation of digital solutions not only supports sustainability by reducing emissions but also allows companies to respond dynamically to market demands, making them more competitive. This trend toward digitalization reflects the cement industry's focus on increasing operational efficiency and adapting to the demands of a modern, environmentally conscious market.
Market Restraints and Challenges
High Carbon Emissions and Environmental Regulations
One of the primary challenges facing the global cement market is the high level of carbon emissions associated with cement production. The process of manufacturing cement, especially the calcination of limestone, generates significant CO₂ emissions, making it one of the most carbon-intensive industries. As climate change concerns rise, governments worldwide are implementing stringent environmental regulations to reduce industrial emissions. Compliance with these regulations requires cement manufacturers to adopt costly technologies and modify production processes, which can increase operational expenses. The pressure to meet carbon reduction targets while maintaining profitability has created substantial challenges for the industry. Furthermore, the demand for sustainable alternatives, such as green cement, while promising, also necessitates considerable R&D investment and shifts in manufacturing practices, posing a restraint for smaller companies with limited resources.
Volatility in Raw Material Prices and Supply Chain Disruptions
The global cement market faces ongoing challenges related to the volatility of raw material prices and disruptions in supply chains. Cement production relies heavily on raw materials such as limestone, clay, and gypsum, whose prices can fluctuate due to geopolitical tensions, trade restrictions, or shifts in energy costs. Price volatility directly impacts production costs, making it challenging for companies to maintain stable profit margins. Additionally, global supply chain disruptions, as witnessed during recent events like the COVID-19 pandemic, can hinder the timely procurement of raw materials and distribution of finished products. Transportation costs, logistical bottlenecks, and shortages of essential inputs can further disrupt production schedules. As cement is a low-margin, high-volume product, these fluctuations and delays in the supply chain create substantial financial strain for producers, impacting both their operational efficiency and ability to meet market demand consistently.
Market Segmentation Analysis
By Type
Portland cement is the most widely used type in the global cement market due to its versatility, durability, and strength, making it ideal for general construction, including buildings, bridges, and pavements. It holds a significant market share, especially in developing regions experiencing rapid infrastructure growth. Blended cement, combining Portland cement with supplementary materials like fly ash, slag, and silica fume, is gaining traction for its sustainable properties and lower carbon footprint. It is increasingly favored in regions with stringent environmental regulations, offering enhanced workability and durability for long-lasting infrastructure projects. Specialty cements, including white, masonry, and rapid-setting cement, cater to niche applications like decorative work, restorations, and specific architectural needs. Though a smaller market segment, specialty cements are steadily growing due to demand from unique construction projects and high-end architectural designs.
By Application
The global cement market is driven by both residential and non-residential applications, with the residential segment leading due to the growth in housing demand, particularly in rapidly urbanizing regions like Asia-Pacific and Africa. Government initiatives supporting affordable housing and rural development further boost residential cement consumption, prompting manufacturers to cater to diverse housing needs, from low-cost housing to luxury projects. In the non-residential segment, cement demand remains strong due to its essential role in infrastructure projects like roads, bridges, airports, and power plants. Public and private sector investments, particularly in emerging economies, are also fueling growth in non-residential construction, alongside the expansion of commercial and industrial facilities, which continues to strengthen the market.
Segments
Based on Type
- Portland Cement
- Blended Cement
- Others
Based on Application
- Residential
- Non-Residential
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
Asia-Pacific (60%)
Asia-Pacific holds the largest share of the global cement market, accounting for approximately 60% of total demand. This dominance is driven by rapid urbanization, strong economic growth, and robust infrastructure development in countries like China and India. China, the largest producer and consumer of cement, accounts for a substantial portion of regional demand, supported by extensive construction activities across residential, commercial, and infrastructural sectors. India, too, is experiencing a construction boom fueled by government-led housing initiatives, urbanization, and industrial expansion. Additionally, countries in Southeast Asia, including Vietnam, Indonesia, and the Philippines, are investing heavily in infrastructure projects, further boosting regional demand. The high population density, ongoing urban migration, and the push for improved infrastructure collectively support sustained growth in cement consumption within Asia-Pacific.
North America (15%)
North America, holding around 15% of the global cement market share, experiences steady demand primarily driven by infrastructure modernization and the growth of the non-residential construction sector. In the United States, aging infrastructure requires significant refurbishment and maintenance, which is propelling demand for cement, especially for roads, bridges, and public buildings. Additionally, sustainability trends are gaining momentum in North America, where the adoption of green and blended cements is increasing in response to strict environmental regulations. Canada also contributes to regional demand, with a focus on sustainable construction practices and investments in public infrastructure. While growth in North America is relatively stable compared to emerging markets, it remains significant due to the focus on infrastructure upgrades and environmental sustainability.
Key players
- CEMEX S.A.B. de C.V.
- Heidelberg Cement
- InterCement Participações S.A.
- Holcim Ltd.
- CRH plc
- Titan Cement Company S.A.
- UltraTech Cement Limited
- Votorantim Cimentos
- Buzzi Unicem S.p.A.
- Mitsubishi Materials Corporation
- Argos USA LLC
- China National Building Material Co., Ltd.
- Taiheiyo Cement Corporation
- Drake Cement LLC
Competitive Analysis
The global cement market is highly competitive, dominated by established players with extensive geographic reach and strong production capabilities. Key players such as CEMEX, Heidelberg Cement, and Holcim Ltd. leverage their scale, diverse product portfolios, and innovation in sustainable products to maintain market leadership. Companies are increasingly focusing on eco-friendly solutions, incorporating low-carbon and green cement to meet environmental standards. UltraTech Cement, CRH plc, and Votorantim Cimentos have also expanded their operations through strategic mergers and acquisitions, boosting their market presence in emerging regions. China National Building Material Co. Ltd. and Taiheiyo Cement Corporation benefit from strong regional dominance in Asia, which drives demand in fast-growing markets. This competitive landscape is characterized by a blend of large multinational corporations and regional players, each seeking to differentiate through innovation, product diversity, and sustainability initiatives.
Recent Developments
- In July 2024, Heidelberg Materials announced the acquisition of Highway Materials, Inc., along with two other companies in Texas, expanding its footprint in the U.S. aggregates and asphalt markets.
- As of June 2024, InterCement received non-binding acquisition offers for its assets in Brazil and Argentina from several companies, including CSN and Huaxin Cement.
- In the first quarter of 2024, CRH completed eight acquisitions totaling $2.2 billion, including a significant acquisition of cement and concrete assets in Texas from Martin Marietta Materials.
- On April 20, 2024, UltraTech Cement announced the acquisition of a grinding unit from India Cements in Maharashtra for ₹315 crore to strengthen its presence in the Maharashtra market.
- In early 2024, Votorantim Cimentos announced a R$200 million investment to expand its Pecém plant in Ceará, Brazil, increasing its cement grinding capacity significantly.
- In October 2024, CNBM signed a five-year Cooperation Framework Agreement with Aramco to explore opportunities in advanced materials and industrial development.
- In October 2024, Taiheiyo Cement Philippines launched a new US$220 million production line at its San Fernando plant in Cebu to support national cement production.
Market Concentration and Characteristics
The global cement market is moderately concentrated, with several large multinational corporations dominating a significant share alongside numerous regional and local players. Key characteristics of this market include high capital requirements, significant barriers to entry, and economies of scale that favor established players. Leading companies such as CEMEX, Heidelberg Cement, and Holcim Ltd. have substantial production capacities, extensive distribution networks, and robust financial resources, allowing them to maintain competitive advantage and influence market pricing. Additionally, the industry is capital-intensive and energy-intensive, with strict environmental regulations that drive innovation in sustainable products, such as green and low-carbon cement. As the industry responds to increasing sustainability demands and regional infrastructure needs, market consolidation through mergers and acquisitions continues to be a common trend among top players, enhancing both geographic reach and product diversity.
Report Coverage
The research report offers an in-depth analysis based on Type, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Emerging economies, particularly in Asia-Pacific and Africa, will continue to drive market growth due to rapid urbanization, population growth, and industrial expansion.
- Environmental concerns will accelerate the adoption of sustainable cement alternatives, including green and low-carbon options, as companies aim to reduce their carbon footprints.
- Digital transformation in cement production, including automation and AI-driven process optimization, will enhance productivity and reduce operational costs across the industry.
- Ongoing and new infrastructure projects, especially in developing regions, will bolster cement demand, particularly for large-scale constructions like roads, bridges, and airports.
- Government initiatives focused on affordable housing in emerging markets will support stable demand for cement in the residential construction sector.
- Manufacturers will continue to adopt waste recycling practices and alternative raw materials to improve sustainability and comply with environmental regulations.
- Leading players are likely to engage in mergers and acquisitions to expand their market reach, strengthen supply chains, and enhance production capacities.
- Blended cement, known for its sustainability benefits and durability, will witness increased demand, particularly in regions with strict environmental standards.
- The Asia-Pacific region will remain the largest and fastest-growing market, driven by rapid construction activity in countries like China, India, and Indonesia.
- Cement companies will increasingly invest in digital supply chain solutions, enabling them to improve logistics, reduce costs, and enhance customer satisfaction by ensuring timely delivery.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the global cement market in 2023 and 2032, and what is the CAGR?
What factors are driving growth in the global cement market?
How are sustainability trends affecting the cement market?
Which regions dominate the global cement market?
Who are the key players in the global cement market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Cement Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Cement Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 405,631.23 million → 2032: USD 602,806.60 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Cement Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Cement Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Cement Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Cement Market Drivers
- 3.3 Cement Market Restraints & Challenges
- 3.4 Cement Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Cement Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Cement Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Cement category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Cement Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Cement Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Cement market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Cement Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Cement Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Cement Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Cement (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Cement Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Cement Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Cement Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Cement Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Cement Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Cement Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Cement Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Cement Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Cement Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
