
Market Overview:
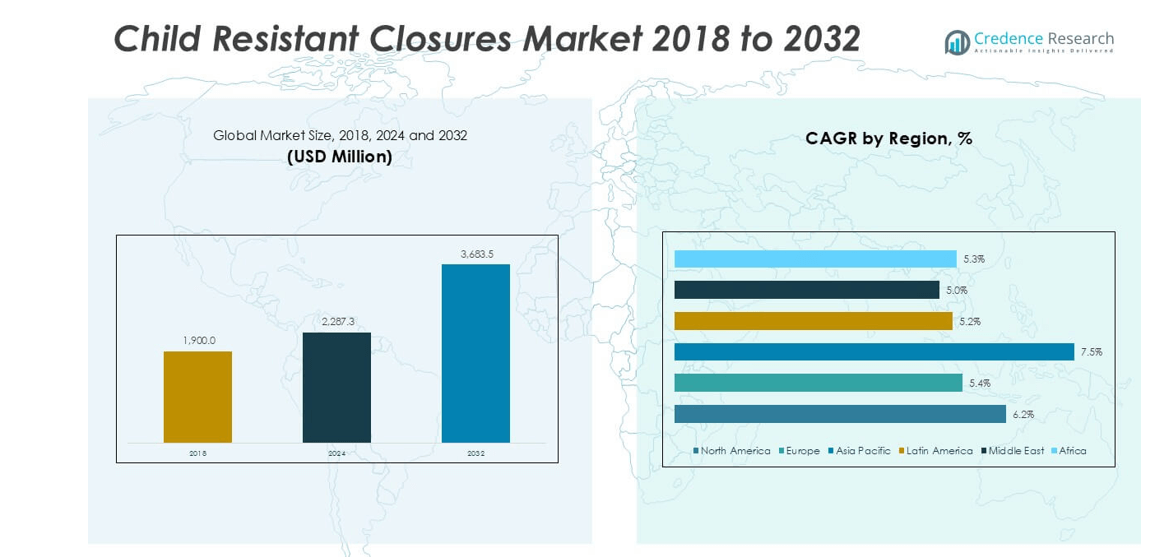
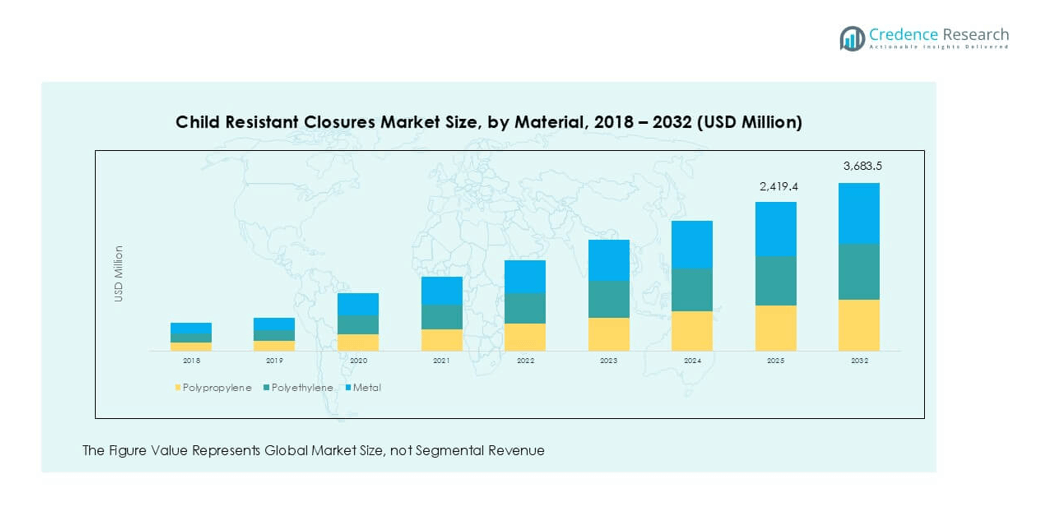
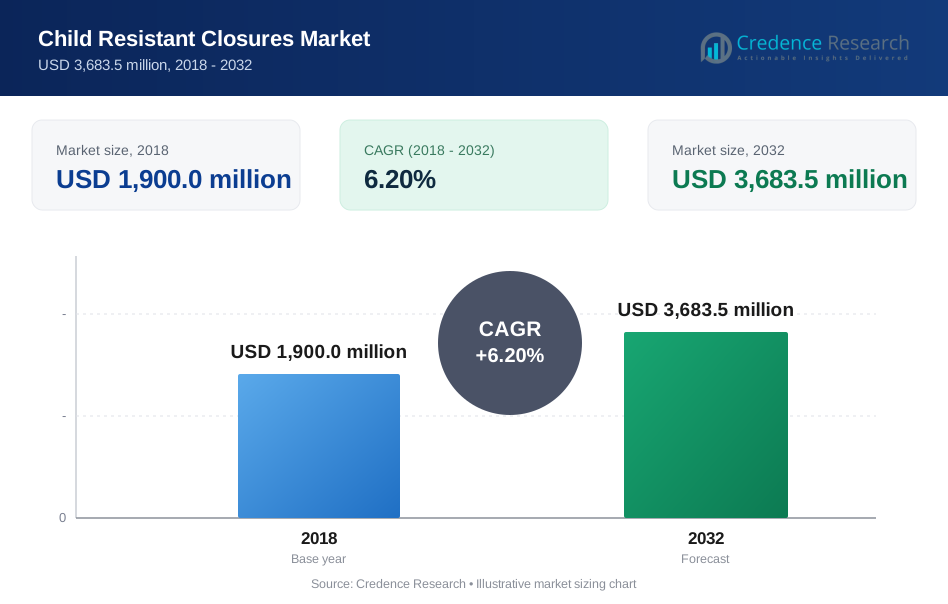
The Global Child Resistant Closures Market size was valued at USD 1,900.0 million in 2018 to USD 2,287.3 million in 2024 and is anticipated to reach USD 3,683.5 million by 2032, at a CAGR of 6.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Child Resistant Closures Market Size 2024 | USD 2,287.3 million |
| Child Resistant Closures Market, CAGR | 6.2% |
| Child Resistant Closures Market Size 2032 | USD 3,683.5 million |
Key drivers of market expansion include rising concerns over child safety, stringent regulations regarding packaging for hazardous substances, and the growing adoption of child-resistant packaging solutions in the pharmaceutical and consumer goods sectors. The increasing awareness of the importance of packaging safety for preventing accidental poisoning, particularly among children, has accelerated the adoption of these closures. Furthermore, innovations in design, such as tamper-evident and easy-to-use mechanisms, are boosting demand. The development of eco-friendly and sustainable child-resistant packaging options is also contributing to the market's growth.
Regionally, North America holds the largest market share, driven by strict regulations in the United States, which require child-resistant packaging for certain products. Europe also holds a significant share, fueled by regulatory frameworks across the region. The Asia-Pacific region is expected to witness the highest growth rate, supported by rapid industrialization, increasing regulatory enforcement, and rising awareness about child safety in emerging economies like China and India.
Market Insights:
- The global child-resistant closures market was valued at USD 1,900.0 million in 2018 and is projected to reach USD 3,683.5 million by 2032.
- Key market drivers include rising concerns over child safety, stringent regulations, and growing adoption across various sectors.
- Innovations in tamper-evident and user-friendly mechanisms are driving demand for child-resistant closures.
- The market is increasingly influenced by the development of sustainable, eco-friendly packaging solutions.
- North America holds the largest market share, driven by strict regulations in the U.S. and Canada.
- Asia-Pacific is expected to experience the highest growth rate, supported by industrialization and increasing awareness of child safety.
- Latin America, the Middle East, and Africa are experiencing steady growth, driven by regulatory developments and rising consumer awareness.
Market Drivers:
Increasing Focus on Child Safety and Prevention of Accidental Poisoning
The global child-resistant closures market is primarily driven by the increasing focus on child safety. Parents and caregivers are becoming more aware of the dangers of accidental poisoning, leading to higher demand for secure packaging solutions. These closures are essential in preventing young children from accessing harmful substances, particularly in households with medications, household chemicals, and cleaning agents. The growing concern over child safety continues to propel the adoption of these closures across various industries.
Stringent Regulatory Standards for Packaging Safety
Regulatory requirements play a crucial role in shaping the growth of the global child-resistant closures market. Countries worldwide have introduced strict guidelines for packaging hazardous substances to reduce the risk of child exposure. The U.S. and European markets, in particular, have implemented robust legislation that mandates child-resistant packaging for products like pharmaceuticals, pesticides, and over-the-counter medications. These regulations are expected to remain stringent, supporting continued market growth in the coming years.
- For instance, JohnsByrne developed its EPIK LOK® packaging, which is a tested and certified solution that meets the U.S. 16 C.F.R. Part 1700 protocol, ensuring compliance with federal standards designed to prevent child access to potentially harmful products.
Demand for Innovative and User-Friendly Packaging Solutions
Another driver of market growth is the demand for innovative packaging solutions that maintain child resistance while offering convenience for adults. Consumers and manufacturers are increasingly seeking closures that are not only child-resistant but also easy for adults to use. The development of advanced packaging designs, such as push-and-turn mechanisms or closures with dual resistance features, is helping meet these needs. This innovation is boosting market expansion by addressing both safety and practicality.
Rising Awareness of Environmental Sustainability
Environmental sustainability is becoming a significant driver in the global child-resistant closures market. As consumers and businesses prioritize eco-friendly solutions, there is a growing push toward recyclable and biodegradable materials in packaging. Manufacturers are responding by designing closures that meet both safety and sustainability requirements. This shift toward eco-friendly packaging options is gaining traction and is expected to fuel the market’s growth, especially in regions with stringent environmental regulations.
- For instance, Keystone has addressed this with its Ecoslide-RX®, a paperboard-based blister package made from recyclable materials, which meets the F=1 child-resistant standard while eliminating the need for secondary plastic locking components.
Market Trends:
Shift Toward Sustainable and Eco-Friendly Packaging Solutions
The global child-resistant closures market is witnessing a significant trend toward sustainable packaging solutions. Growing environmental concerns and consumer demand for eco-friendly products have pushed manufacturers to develop closures using recyclable or biodegradable materials. This shift is particularly important as companies seek to reduce their carbon footprint and comply with increasingly stringent environmental regulations. Packaging solutions that combine child resistance with sustainability are gaining traction, especially in industries such as pharmaceuticals and consumer goods. As consumers become more conscious of the environmental impact of their purchases, it is likely that demand for these sustainable alternatives will continue to rise. This trend is contributing to the growth of the child-resistant closures market, aligning safety with environmental responsibility.
- For instance, Amcor's Hector Child Resistant Closure achieves a reduction in plastic of 6.75 tonnes for every one million units ordered when compared to conventional closures.
Technological Advancements Enhancing Packaging Functionality and Design
Another important trend in the global child-resistant closures market is the integration of advanced technologies into packaging design. Manufacturers are incorporating features such as tamper-evident systems and smart packaging elements, enhancing both safety and functionality. These innovations provide consumers with greater confidence in the reliability of packaging solutions. User-friendly designs are also gaining popularity, with adult-friendly mechanisms that do not compromise child resistance. Automation and smart packaging technologies, such as QR codes for tracking, are also being integrated into child-resistant closures. These advancements are shaping the future of packaging by combining enhanced safety features with modern technology, making it easier to track and verify the integrity of products. This evolution is expected to continue driving market growth in the coming years.
- For instance, Amcor's technologically advanced Hector closure features a directional nozzle and is designed to be compatible with a 38mm bottle neck, enhancing its functional design for precise product application.
Market Challenges Analysis:
High Manufacturing Costs and Complexity
One of the key challenges in the global child-resistant closures market is the high cost associated with manufacturing these specialized packaging solutions. The complexity of designing closures that effectively prevent access by children while remaining user-friendly for adults increases production costs. Manufacturers must invest in advanced materials and technologies to meet safety standards and regulatory requirements. These added expenses can make child-resistant closures more expensive than conventional packaging, which could limit their adoption, particularly among cost-sensitive industries. Balancing affordability with safety and functionality remains a significant challenge for market players.
Regulatory Compliance and Standardization Issues
Another challenge in the global child-resistant closures market is navigating the complex regulatory landscape. Different regions have varying safety standards and requirements for child-resistant packaging, making it difficult for manufacturers to maintain consistent compliance across multiple markets. The lack of standardization can lead to increased operational costs and delays in bringing products to market. Companies must invest in legal expertise and stay updated on evolving regulations to ensure their products meet all necessary standards. Failure to comply with these regulations can result in product recalls, legal liabilities, and damage to a company's reputation.
Market Opportunities:
Expansion of Regulatory Frameworks in Emerging Economies
The global child-resistant closures market has significant growth opportunities in emerging economies. As these regions, particularly in Asia-Pacific and Latin America, continue to industrialize, the demand for child-resistant packaging is expected to rise. Governments are increasingly focusing on child safety and implementing stricter regulations for packaging, especially in the pharmaceutical, chemical, and consumer goods sectors. Manufacturers that can tailor their solutions to meet these evolving regulatory standards will benefit from expanded market presence. This trend presents an opportunity for companies to tap into underserved markets, where awareness and enforcement of safety regulations are gaining momentum.
Rising Consumer Demand for Eco-Friendly Packaging Solutions
Sustainability has become a major driver in the global child-resistant closures market. Consumers and businesses alike are seeking packaging solutions that prioritize both safety and environmental responsibility. The growing preference for eco-friendly packaging, including recyclable and biodegradable materials, creates a competitive advantage for manufacturers that can innovate in these areas. The market presents an opportunity for companies to integrate sustainable practices into their product offerings, catering to the increasing demand for green solutions. Businesses that invest in sustainable child-resistant closures can position themselves as leaders in a market driven by environmental consciousness.
Market Segmentation Analysis:
By Material
The global child-resistant closures market is segmented into polypropylene, polyethylene, metal, and other materials. Polypropylene leads the market due to its cost-effectiveness, durability, and resistance to environmental factors. Polyethylene is gaining traction, expected to register the highest CAGR, driven by its flexibility and recyclability. Metal closures offer enhanced tamper resistance and are preferred in premium packaging applications. Other materials, including biodegradable options, are emerging in response to growing environmental concerns. This diversification in materials caters to varying industry needs, balancing safety, cost, and sustainability.
By Closure Type
Closure types in the child-resistant closures market include push and turn, squeeze and turn, and others. Push and turn closures dominate, favored for their user-friendly design and compliance with safety standards. Squeeze and turn closures are gaining popularity, particularly in pharmaceutical applications, for their ease of use and effectiveness. Other types, such as snap-on and friction-fit closures, are utilized in specific applications where traditional mechanisms may not be suitable. The market's evolution reflects a shift towards closures that enhance safety without compromising convenience.
- For instance, Comar offers the QuarterLoc®, a one-piece push-and-turn child-resistant closure available in a 53 mm size that provides a secure closure with just a quarter turn.
By End-Use
The child-resistant closures market serves various end-use industries, including pharmaceuticals, household products, cosmetics and personal care, chemicals and fertilizers, and food and beverages. Pharmaceuticals hold the largest share, driven by stringent regulations and the need to prevent accidental ingestion of medications. Household products are witnessing increased adoption of child-resistant packaging, addressing safety concerns related to cleaning agents and other hazardous substances. The cosmetics and personal care sector is incorporating child-resistant closures to enhance product safety. Chemicals and fertilizers require secure packaging to prevent exposure, while the food and beverage industry is exploring child-resistant solutions for products like cannabis-infused edibles. Each sector's growth is propelled by regulatory requirements and heightened consumer safety awareness.
- For instance, BERICAP's SK 38/14 CR closure for the pharmaceutical sector is certified under ISO 8317 and is applicable for a 38 mm standard neck finish.
Segmentations:
By Material- Polypropylene
- Polyethylene
- Metal
- Others
- Push and Turn
- Squeeze and Turn
- Others
- Pharmaceutical
- Household Product
- Cosmetic and Personal Care
- Chemicals and Fertilizer
- Food and Beverage
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America
The North America child-resistant closures market size was valued at USD 697.3 million in 2018, growing to USD 829.4 million in 2024, and is anticipated to reach USD 1,333.5 million by 2032, at a CAGR of 6.2% during the forecast period. North America holds the largest market share, driven by strict regulatory requirements in the United States and Canada. The demand for child-resistant closures is primarily propelled by the growing focus on child safety and increasing consumer awareness about preventing accidental poisonings. Strong government policies regarding child-resistant packaging in pharmaceuticals, household chemicals, and other potentially hazardous products are key factors contributing to market expansion. The region's significant market share is supported by a robust healthcare infrastructure and high spending power, further driving the adoption of these closures in various industries. Additionally, the growing trend toward sustainability and eco-friendly packaging solutions is adding to the regional growth. The North American market is expected to maintain its dominance due to consistent regulatory reinforcement and innovation in packaging solutions.
Europe
The Europe child-resistant closures market size was valued at USD 461.7 million in 2018, increasing to USD 532.4 million in 2024, and is projected to reach USD 805.8 million by 2032, at a CAGR of 5.4%. Europe holds a significant share of the global market, fueled by strong regulatory frameworks and a focus on safety and sustainability. Countries such as the UK, Germany, and France have stringent packaging laws, which further promote the adoption of child-resistant closures across various sectors. The demand in Europe is also driven by the growing awareness of child safety, especially in the pharmaceutical industry. In addition to regulatory requirements, consumers’ preference for eco-friendly packaging solutions is pushing manufacturers to integrate sustainable practices into their product offerings. Innovations in packaging technology, such as easy-to-use mechanisms and recyclable materials, are contributing to market growth. Europe’s market share is projected to grow steadily, supported by these evolving trends and continued regulatory development.
Asia Pacific
The Asia Pacific child-resistant closures market size was valued at USD 452.2 million in 2018, reaching USD 569.2 million in 2024, and is expected to grow to USD 1,010.9 million by 2032, at a CAGR of 7.5%. This region is anticipated to experience the fastest growth due to rapid industrialization and rising awareness about child safety. Increasing regulatory enforcement in countries such as China, India, and Japan is driving the demand for child-resistant packaging solutions, particularly in pharmaceuticals and household chemicals. The growing middle-class population, along with improving healthcare systems, is creating opportunities for market expansion. As the region's regulatory standards evolve, companies are also expected to introduce cost-effective and user-friendly packaging solutions. The rise in consumer awareness about the dangers of accidental poisoning, particularly in emerging markets, further supports the market’s growth trajectory. Asia Pacific’s market share is anticipated to increase significantly, with innovation and regulatory changes playing a key role.
Latin America
The Latin America child-resistant closures market size was valued at USD 117.8 million in 2018, increasing to USD 140.4 million in 2024, and is projected to reach USD 209.5 million by 2032, growing at a CAGR of 5.2%. The market in Latin America is expanding steadily, driven by increasing awareness of child safety and growing regulations related to child-resistant packaging. While regulatory standards are still evolving in some countries, there is a noticeable shift toward stricter packaging laws, particularly for pharmaceuticals and household chemicals. Brazil, Mexico, and Argentina are leading the charge in adopting these safety standards, further boosting demand. The region’s growth is also driven by expanding industrial sectors and improving consumer safety awareness. The rising adoption of eco-friendly packaging materials is another key factor contributing to the region’s market expansion. Latin America’s market share is set to grow gradually, supported by these trends and expanding regulatory frameworks.
Middle East
The Middle East child-resistant closures market size was valued at USD 77.9 million in 2018, growing to USD 88.3 million in 2024, and is anticipated to reach USD 129.3 million by 2032, at a CAGR of 5.0%. The Middle East market is experiencing steady growth, driven by increasing regulations and rising demand for child-safe packaging. Countries in the region are introducing more stringent safety laws, particularly for products like pharmaceuticals and chemicals, which is expected to accelerate the demand for child-resistant closures. As consumer awareness of child safety increases, the demand for secure packaging solutions continues to rise. Moreover, the region’s market is expanding due to improvements in packaging technology and a shift towards sustainable packaging options. The adoption of child-resistant closures is particularly strong in the UAE and Saudi Arabia, where regulatory frameworks are evolving rapidly. The Middle East market share is expected to expand, although at a slower pace compared to other regions.
Africa
The Africa child-resistant closures market size was valued at USD 93.1 million in 2018, reaching USD 127.6 million in 2024, and is projected to grow to USD 194.5 million by 2032, at a CAGR of 5.3%. Africa’s market is witnessing steady growth, supported by increasing consumer awareness about child safety and expanding regulations. As governments in countries like South Africa, Nigeria, and Kenya introduce stricter safety standards for packaging, the demand for child-resistant closures is expected to rise. In addition, the growing middle-class population and improved healthcare infrastructure in these countries are further propelling market growth. There is also a rising focus on sustainable packaging solutions, which is contributing to the market's expansion. Despite the relatively smaller market share, Africa's child-resistant closures market is positioned for steady growth as regulatory frameworks strengthen and consumer demand for safety packaging increases.
Key Player Analysis:
- Berry Global Inc.
- BERICAP
- AptarGroup, Inc.
- BERK
- CL Smith
- Georg MENSHEN GmbH and Co. KG
- Tecnocap S.p.A.
- UNITED CAPS
- Van Blarcom Closures Inc.
Competitive Analysis:
The global child-resistant closures market is competitive, with several key players holding significant market shares. Companies such as Berry Global, AptarGroup, and Gerresheimer are leading the industry. These companies invest extensively in research and development to introduce innovative packaging solutions that meet strict safety standards. For example, Berry Global offers various child-resistant closures, such as the 400 PP Child Resistant Closure, known for its enhanced safety and ease of use. AptarGroup provides closure solutions like push and turn mechanisms, catering to diverse packaging needs across industries. Gerresheimer focuses on producing high-quality closures, especially for the pharmaceutical sector, ensuring compliance with regulatory standards. The market also includes other notable players like Silgan Plastics and BERICAP, who continue to innovate and expand their presence. This competitive environment fosters continuous advancements in closure technologies, driving improvements in safety and functionality for end-users.
Recent Developments:
- In March 2025, Berry Global launched a comprehensive E-Book to guide businesses in selecting the most suitable flexible plastic tube solutions.
- In August 2025, BERICAP announced the industrial launch of its easyconnect cap, a closed transfer system designed for the European agricultural industry.
Report Coverage:
The research report offers an in-depth analysis based on Material, Closure Type, End-Use and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The global child-resistant closures market will continue to see growth driven by increasing safety regulations in various industries, particularly pharmaceuticals and household products.
- Manufacturers will increasingly focus on incorporating eco-friendly materials into their packaging to meet rising consumer demand for sustainable solutions.
- Technological advancements in closure mechanisms will enhance both safety and convenience, with innovations like push-and-turn and squeeze-and-turn closures becoming more prevalent.
- The demand for child-resistant closures in emerging markets will increase as governments tighten packaging regulations and consumers become more safety-conscious.
- Evolving packaging designs that combine child resistance with ease of use for adults will capture a larger share of the market.
- The pharmaceutical sector will remain the largest end-user of child-resistant closures, driven by stringent regulations and the need to prevent accidental poisoning.
- Other industries, including cosmetics, personal care, and food and beverages, will adopt child-resistant packaging solutions as safety concerns rise among consumers.
- The adoption of smart packaging technologies will provide additional opportunities for child-resistant closures, including tamper-evident features and traceability.
- Rising urbanization and increasing disposable income in developing regions will contribute to greater demand for secure packaging solutions.
- The market will witness consolidation as major players acquire smaller companies to expand their product portfolios and strengthen their market position.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Child Resistant Closures Market?
What factors are driving the growth of the Child Resistant Closures Market?
What are some challenges faced by the Child Resistant Closures Market?
Who are the major players in the Child Resistant Closures Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Child Resistant Closures Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2018; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Child Resistant Closures Market Snapshot
- 2.1.1 Market Size – Historical (2018) & Forecast (2018-2032) (2018: USD 1,900.0 million → 2032: USD 3,683.5 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Child Resistant Closures Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2018 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2018
- 2.3.2 Top 10 Players by Volume Share – 2018 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Child Resistant Closures Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Child Resistant Closures Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Child Resistant Closures Market Drivers
- 3.3 Child Resistant Closures Market Restraints & Challenges
- 3.4 Child Resistant Closures Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Child Resistant Closures Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Child Resistant Closures Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Child Resistant Closures category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Child Resistant Closures Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Child Resistant Closures Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2018)
- 5.1.2 Global Export Volume by Country (2018) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2018)
- 5.1.4 Global Import Volume by Country (2018) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2018)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2018)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Child Resistant Closures. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Child Resistant Closures Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2018
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Child Resistant Closures Market Share Analysis – 2018
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2018)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Child Resistant Closures Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Child Resistant Closures (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Child Resistant Closures
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Child Resistant Closures Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2018 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2018-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Child Resistant Closures Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Child Resistant Closures Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Child Resistant Closures Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Child Resistant Closures Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Child Resistant Closures Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Child Resistant Closures Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Child Resistant Closures Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
