
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| China Human Insulin Market Size 2023 | USD 2,550.64 million |
| China Human Insulin Market, CGR | 6.43% |
| China Human Insulin Market Size 2032 | UUSD 4,472.55 million |
Market Overview
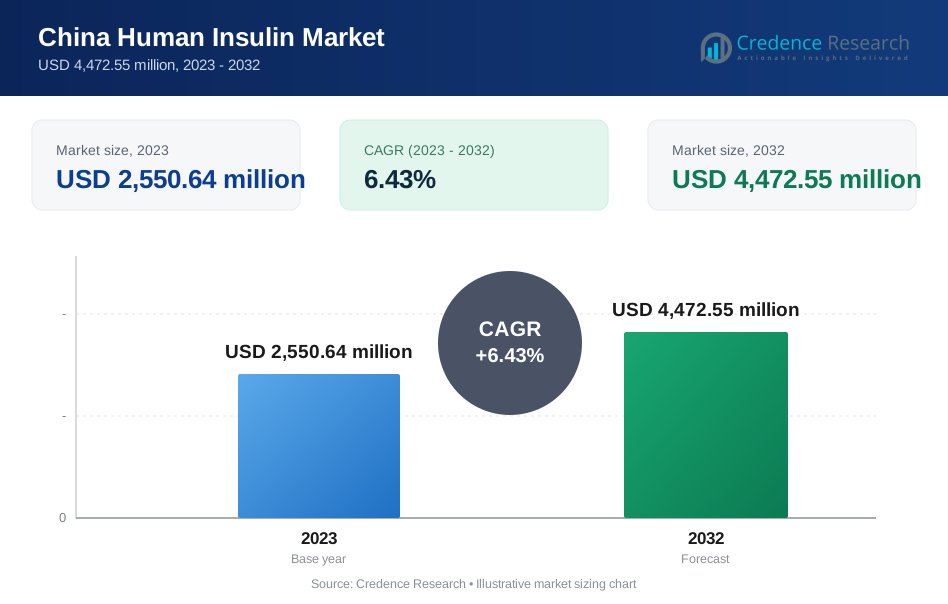
China Human Insulin market size was valued at USD 2,550.64 million in 2023 and is anticipated to reach USD 4,472.55 million by 2032, at a CAGR of 6.43% during the forecast period (2023-2032).
The market for human insulin in China is driven by the increasing prevalence of diabetes, a rapidly aging population, and growing healthcare awareness. As the country continues to urbanize, lifestyle changes have led to a rise in the number of diabetes cases, creating a strong demand for insulin. Additionally, advancements in insulin delivery technologies and the expansion of healthcare infrastructure are fueling market growth. The Chinese government's support through policies aimed at improving diabetes care, along with rising health insurance coverage, further contributes to market expansion. With a focus on improving accessibility and affordability, both local and international pharmaceutical companies are increasingly investing in China, driving competition and innovation. Moreover, the adoption of biosimilars and the shift towards personalized medicine are expected to significantly impact the market, offering new treatment options for diabetes patients. These trends position the Chinese human insulin market for continued growth and development.
Geographically, the human insulin market in China is driven by key regions such as Beijing, Shanghai, Guangzhou, and Shenzhen, each experiencing significant growth due to factors like urbanization, rising diabetes prevalence, and improvements in healthcare infrastructure. These cities are central to the demand for advanced insulin delivery technologies, including insulin pens, pumps, and biosimilars. Key players in the Chinese human insulin market include global pharmaceutical giants like Novo Nordisk, Eli Lilly, and Pfizer, alongside prominent local companies such as Tonghua Dongbao Pharmaceutical and Gan & Lee Pharmaceuticals. These companies are increasingly focusing on expanding their product portfolios and distribution networks in China to tap into the growing demand for insulin. With the continued adoption of innovative insulin management solutions and a government push for better diabetes care, these key players are poised to benefit from the expanding market.
Market Insights
- The China human insulin market was valued at USD 2,550.64 million in 2023 and is expected to reach USD 4,472.55 million by 2032, growing at a CAGR of 6.43% during the forecast period (2023-2032).
- The global human insulin market was valued at USD 21,000 million in 2023 and is projected to reach USD 31,208 million by 2032, growing at a CAGR of 4.50% from 2023 to 2032.
- Rising diabetes prevalence, especially due to urbanization and changing lifestyles, is a primary driver of insulin demand.
- Increasing healthcare awareness and government policies focused on diabetes management are propelling market growth.
- The adoption of biosimilars and innovative insulin delivery technologies, such as insulin pens and pumps, is a key market trend.
- Competitive players include Novo Nordisk, Eli Lilly, Pfizer, Gan & Lee Pharmaceuticals, and Tonghua Dongbao, intensifying market competition.
- The market faces pricing pressures, regulatory challenges, and the need for cost-effective solutions.
- Regions like Beijing, Shanghai, Guangzhou, and Shenzhen lead the market due to high urbanization, healthcare access, and rising diabetes cases.
Report Scope
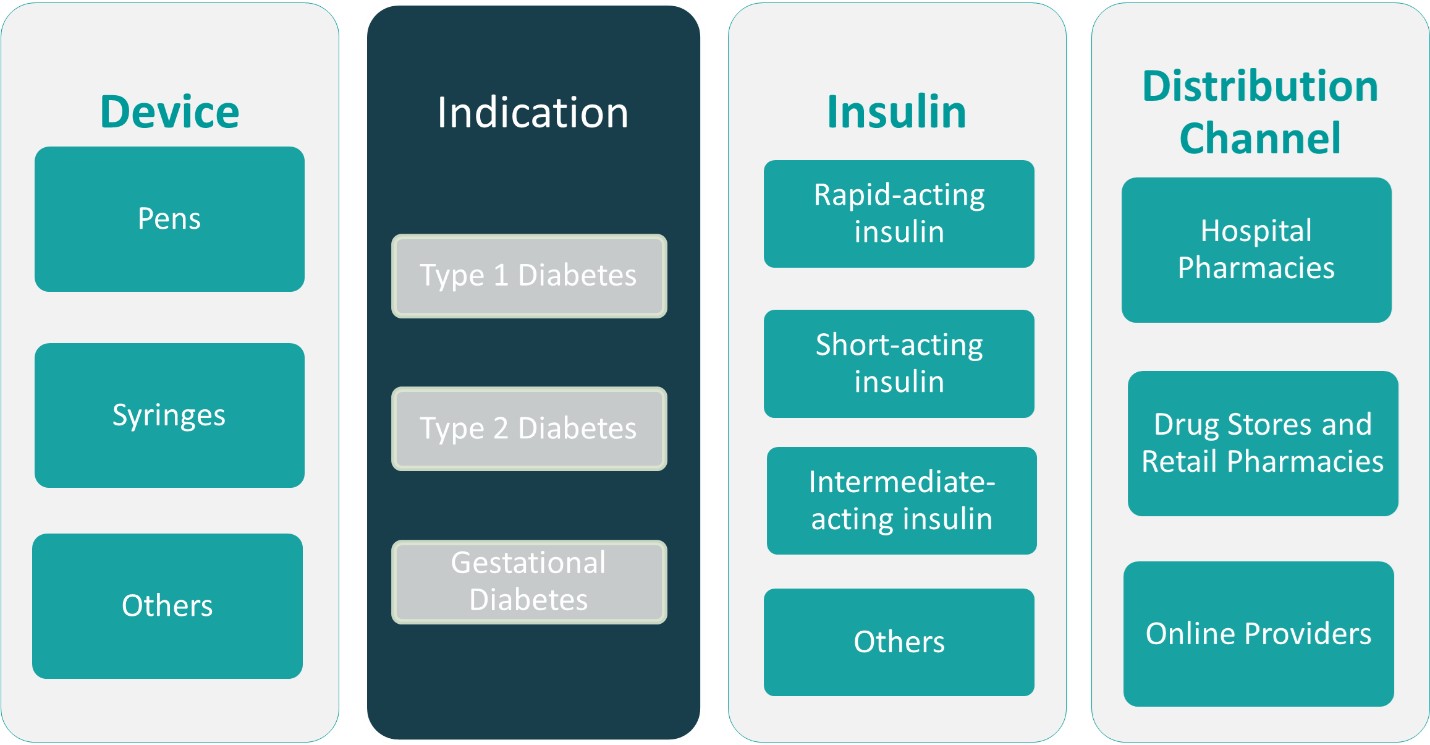
This report segments the China Human Insulin Market as follows:
Market Drivers
Rising Prevalence of Diabetes
The increasing prevalence of diabetes in China is one of the primary drivers of the human insulin market. For instance, China has the highest number of diabetics globally, with approximately 141 million people affected by the condition in 2021. As urbanization accelerates and lifestyle changes, such as poor diet and reduced physical activity, become more common, the incidence of type 2 diabetes is rising at an alarming rate. This growing patient pool significantly boosts the demand for diabetes treatments, especially insulin. As the prevalence of diabetes continues to rise, the need for effective insulin therapies becomes even more critical, leading to sustained market growth.
Aging Population
China's aging population is another key driver contributing to the growth of the human insulin market. For instance, the proportion of individuals aged 60 and above in China is steadily increasing, with demographic trends indicating a significant rise in elderly populations over the next decade. Older adults are more susceptible to developing chronic conditions like diabetes, which further exacerbates the demand for insulin. With many elderly individuals being diagnosed with both type 1 and type 2 diabetes, the market for human insulin is seeing a significant boost. The Chinese government’s recognition of this demographic shift has led to increased healthcare investments and policies aimed at improving the management of diabetes in elderly populations, thereby further driving market expansion.
Government Initiatives and Healthcare Improvements
Government initiatives and healthcare reforms play a crucial role in driving the growth of the human insulin market in China. The Chinese government has made significant strides in improving access to healthcare services, particularly for chronic conditions like diabetes. Policies that promote better diabetes management, subsidize insulin prices, and enhance healthcare infrastructure are directly supporting the insulin market. Additionally, the growing availability of health insurance coverage for diabetes treatment has made insulin more accessible to a larger portion of the population. With the government continuing to emphasize public health improvements, especially for individuals suffering from chronic diseases, the insulin market is poised for sustained growth.
Technological Advancements and Biosimilars
Technological advancements in insulin delivery systems and the rise of biosimilars are also playing a pivotal role in driving market growth. Innovations such as insulin pens, pumps, and continuous glucose monitoring devices are enhancing the patient experience by providing more efficient and less invasive methods of insulin administration. Additionally, the increasing availability of biosimilar insulin products is improving affordability and accessibility, particularly for patients who cannot afford branded insulin. As biosimilars enter the market, competition intensifies, leading to reduced prices and greater market penetration. The combination of these technological innovations and the growing adoption of biosimilars is expected to significantly impact the human insulin market in China, making diabetes management more effective and affordable for a broader segment of the population.
Market Trends
Technological Advancements in Insulin Delivery Systems
Technological advancements in insulin delivery systems are transforming diabetes care in China, making treatment more convenient and effective for patients. For instance, insulin pumps, continuous glucose monitors (CGMs), and insulin pens are transforming diabetes management in China. These innovations are enabling better glucose control and improved treatment adherence, as they provide greater accuracy, ease of use, and flexibility for patients. Insulin pens, for example, have replaced vials and syringes, offering a more discreet and precise way to administer insulin. Additionally, insulin pumps and CGM systems are becoming more widely used, particularly among patients who require intensive insulin therapy, such as those with type 1 diabetes. As these technologies become more affordable and accessible, they are expected to significantly enhance patient outcomes and drive further demand for insulin in the market. The ongoing development and adoption of these advanced insulin delivery systems are expected to remain a prominent trend in China’s insulin market in the coming years.
Strategic Investments by Global Pharmaceutical Companies
In response to the growing demand for insulin in China, global pharmaceutical companies are increasing their investments in the country’s insulin market. For instance, major players such as Sanofi, Novo Nordisk, and Eli Lilly are expanding their manufacturing capabilities and strengthening their market presence to tap into the vast potential of the Chinese healthcare market. For instance, Sanofi has made substantial investments in setting up advanced insulin production facilities in China, underscoring its commitment to increasing local production and meeting the country's demand for diabetes treatments. Similarly, other multinational companies are also focusing on research and development in the region, tailoring insulin therapies and delivery devices to local patient needs. These investments not only help meet the growing demand for insulin but also foster innovation in the diabetes treatment space, contributing to the market’s rapid expansion. With these companies positioning themselves as key players in China’s insulin market, increased competition is expected, leading to further advancements in treatment options and enhanced patient care.
Surge in Diabetes Prevalence
The rising prevalence of diabetes in China is one of the most significant market drivers for human insulin. As the country becomes more urbanized, lifestyle changes such as poor diet, physical inactivity, and increased stress have contributed to a sharp increase in the number of diabetes cases. China currently has the largest diabetic population in the world, with estimates of over 140 million people affected by the condition. This growing population is fueling the demand for insulin as a primary treatment for diabetes, both type 1 and type 2. The government has recognized the urgency of addressing the diabetes epidemic and has made substantial investments in healthcare initiatives like the Healthy China 2030 Plan, which aims to curb the rise of chronic diseases such as diabetes. Consequently, there has been an increasing focus on improving the accessibility and availability of essential diabetes management tools, including insulin, leading to significant market expansion. The prevalence trend is expected to continue, further boosting demand for insulin products in the coming years.
Expansion of Biosimilar Insulin
One of the key trends in China's human insulin market is the growing adoption of biosimilar insulins. Biosimilars are biologically similar to brand-name insulin products but are typically more affordable, offering an essential cost-effective option for patients, particularly in a large market like China where affordability remains a key concern. The Chinese government’s favorable regulatory policies have accelerated the approval and market entry of biosimilar insulin products. These products are now becoming increasingly popular, not only for their lower cost but also due to their ability to provide equivalent efficacy and safety to the original branded insulins. With the ongoing push for more affordable healthcare options, biosimilars are expected to play a crucial role in meeting the rising demand for insulin. This shift towards biosimilars is also expected to intensify competition among pharmaceutical companies, further driving innovation and price reductions in the insulin market. The uptake of biosimilars aligns with the government's broader goals of improving healthcare accessibility and reducing the overall burden of diabetes.
Market Challenges Analysis
Regulatory and Pricing Pressures
One of the significant challenges facing the China human insulin market is the regulatory environment and pricing pressures. Although the Chinese government has made strides in improving healthcare access and expanding insurance coverage, the regulatory process for insulin products can be complex and time-consuming. Obtaining approval for new insulin treatments, particularly biosimilars, involves navigating a rigorous approval process that can delay market entry. Additionally, the government's emphasis on reducing healthcare costs has led to stricter pricing controls, which can squeeze profit margins for pharmaceutical companies. The focus on affordability has encouraged the development of biosimilar insulin products, but the pricing pressures may limit the financial returns for manufacturers, especially multinational companies that rely on premium pricing strategies for branded products. This environment challenges companies to balance innovation, cost-efficiency, and compliance with regulatory requirements while ensuring competitive positioning within a highly price-sensitive market.
Competition and Market Fragmentation
Another challenge in the China human insulin market is the increasing competition and market fragmentation. For instance, with a large number of local and international players entering the market, there is significant pressure on established brands to maintain market share. Local companies often offer insulin products at lower prices, increasing competition for multinational pharmaceutical firms. Additionally, the market is fragmented with a variety of insulin delivery systems, from syringes to advanced insulin pumps, making it difficult for any single device or product type to dominate the market. Companies must navigate a competitive landscape that includes both high-quality branded insulins and affordable biosimilar options, which further complicates their ability to maintain pricing power and customer loyalty. The diverse and growing market segments-ranging from type 1 diabetes to gestational diabetes-also pose challenges in terms of targeted marketing and patient engagement, as companies must cater to varying needs and treatment preferences across different patient groups. These competitive pressures and market fragmentation require companies to continuously innovate while managing cost-effectiveness to remain successful in the rapidly evolving Chinese market.
Market Opportunities
The China human insulin market presents significant opportunities driven by the country’s growing diabetic population and evolving healthcare landscape. As urbanization continues and lifestyle-related diseases rise, the demand for diabetes management solutions, including insulin, is expanding rapidly. With over 140 million people affected by diabetes in China, the need for accessible and affordable insulin treatments is paramount. Additionally, the government’s commitment to improving healthcare infrastructure, particularly through initiatives like the Healthy China 2030 Plan, is creating a favorable environment for growth. There is also a rising demand for innovative insulin delivery devices, such as insulin pens and pumps, which offer patients more convenience and precision in managing their condition. This market trend presents a substantial opportunity for both global and local pharmaceutical companies to invest in and expand their presence in China.
Furthermore, the increasing adoption of biosimilar insulin products is another key opportunity in China’s insulin market. The government’s focus on reducing healthcare costs and improving the affordability of treatments has accelerated the approval and use of biosimilars. As patients seek more cost-effective alternatives to branded insulin, biosimilars are becoming increasingly popular due to their equivalent safety and efficacy profiles. Pharmaceutical companies that can offer high-quality biosimilars at competitive prices stand to benefit from the growing market share in this segment. Additionally, the ongoing advancements in digital health and insulin management technologies, such as continuous glucose monitoring and smart insulin pens, provide opportunities to enhance patient outcomes and improve adherence to treatment. These technological innovations, coupled with a robust regulatory framework, position China’s human insulin market as a highly promising sector for both new and existing players.
Market Segmentation Analysis:
By Device:
The China human insulin market is segmented by device into pens, syringes, and others. Among these, insulin pens dominate the market due to their convenience, ease of use, and accuracy. Insulin pens offer a more user-friendly and precise method of insulin delivery compared to traditional syringes. They are particularly popular among patients with type 1 diabetes and those who require regular insulin injections. The growth of insulin pens is further supported by technological advancements, such as pre-filled pens and smart insulin pens, which offer better dosage accuracy and ease of tracking insulin usage. Syringes, while still in use, are becoming less popular as insulin pens gain traction, but they remain essential in certain markets due to their low cost and availability. The "others" category includes insulin pumps and continuous glucose monitoring devices, which, although less widely used, are gaining traction among patients requiring intensive insulin therapy or advanced diabetes management solutions. As the adoption of advanced delivery devices continues to grow, the segment is expected to see sustained innovation and expansion.
By Indication:
The China human insulin market is also segmented by indication into type 1 diabetes, type 2 diabetes, and gestational diabetes. Type 2 diabetes holds the largest share of the market, primarily driven by lifestyle changes, such as poor diet, sedentary behavior, and urbanization, leading to a significant increase in the number of patients. Insulin is commonly used when oral medications become ineffective in controlling blood sugar levels in these patients. Type 1 diabetes, although less common than type 2, is also a significant market segment, as it requires lifelong insulin therapy. The increasing prevalence of type 1 diabetes in China is supporting steady growth in this segment. Gestational diabetes, typically diagnosed during pregnancy, represents a smaller but growing segment, driven by rising awareness and improved diagnostic capabilities. As China’s healthcare system continues to evolve, all three segments are expected to grow, with type 2 diabetes likely leading the expansion due to its higher prevalence in the population.
Segments:
Based on Device:
- Pens
- Syringes
- Others
Based on Indication:
- Type 1 Diabetes
- Type 2 Diabetes
- Gestational Diabetes
Based on Insulin:
- Rapid-acting insulin
- Short-acting insulin
- Intermediate-acting insulin
- Others
Based on Distribution Channel:
- Hospital Pharmacies
- Drug Stores and Retail Pharmacies
- Online Providers
Based on the Geography:
- Beijing
- Shanghai
- Guangzhou
- Shenzhen
Regional Analysis
Beijing
Beijing, the capital, holds a significant share of the market, accounting for approximately 25% of the total human insulin sales in China. This is due to the city’s large population, substantial healthcare infrastructure, and the high prevalence of diabetes in the region. As the political and economic hub of China, Beijing is also a focal point for government initiatives aimed at improving diabetes management and access to insulin. The city’s advanced healthcare system, along with a growing diabetic population, positions it as a dominant player in the human insulin market, driving both demand for innovative therapies and increasing adoption of advanced insulin delivery devices.
Shanghai
Shanghai, another major city, follows closely with a market share of around 22%. Known for its rapid economic growth and development, Shanghai has become a center for pharmaceutical investments and technological advancements. The region’s increasing awareness of diabetes and the prevalence of both type 1 and type 2 diabetes have contributed to a strong demand for insulin products. With a relatively higher number of healthcare facilities, international pharmaceutical companies, and health insurance coverage in place, Shanghai sees a substantial uptake of advanced insulin therapies, including biosimilars and insulin pens. Moreover, the city’s role as an international business hub means that both local and multinational companies are investing heavily in expanding their market presence in Shanghai, further stimulating growth in this region.
Guangzhou
Guangzhou, located in the southern part of China, represents another significant market for human insulin, holding approximately 18% of the national market share. The city benefits from its position as a trade and manufacturing center, with an extensive healthcare infrastructure supporting the growing demand for diabetes care. The rising number of diabetes cases in the region, coupled with a growing aging population, has created substantial demand for insulin therapies. Guangzhou’s increasing middle-class population, coupled with rising health awareness, is expected to continue driving growth in the human insulin market. The region’s expanding healthcare access and the introduction of new technologies are expected to increase the adoption of insulin management solutions in the coming years.
Shenzhen
Shenzhen, a rapidly growing city in Guangdong province, holds around 15% of China’s human insulin market share. Known for its technological advancements and proximity to Hong Kong, Shenzhen has witnessed significant economic growth, which has positively impacted the healthcare sector. The city has seen an influx of advanced diabetes care technologies, including continuous glucose monitors and insulin pumps, making it an important hub for insulin product adoption. Shenzhen’s progressive approach to healthcare, coupled with a growing middle class and increased awareness about diabetes, provides a conducive environment for insulin product growth. As the city continues to expand its healthcare services, it is expected to see a steady increase in demand for human insulin, particularly as the diabetic population continues to rise.
Key Player Analysis
- Novo Nordisk A/S
- MannKind Corporation
- Pfizer
- Wockhardt
- Biocon
- Lupin
- Eli Lilly and Company
- Gan & Lee Pharmaceuticals
- Tonghua Dongbao Pharmaceutical Co., Ltd
Competitive Analysis
The competitive landscape of China’s human insulin market is marked by the presence of both global pharmaceutical giants and strong local players. Leading international companies such as Novo Nordisk, Eli Lilly, Lupin, Biocon, MannKind Corporation, Tonghua Dongbao Pharmaceutical Co., Ltd and Pfizer dominate the market with their established brand presence and extensive distribution networks. These companies are recognized for their high-quality, innovative insulin products, including both traditional and advanced therapies, such as insulin pens, pumps, and biosimilars. The ability to offer reliable and efficient insulin treatments has positioned these global players as leaders in the sector. On the other hand, local players are gaining significant traction, particularly by focusing on cost-effective solutions that cater to China’s price-sensitive market. Many local companies are capitalizing on the growing demand for biosimilar insulin products, which are viewed as more affordable alternatives to branded insulins. These companies are also benefiting from government support, including regulatory advantages and increased access to the domestic healthcare market. Local manufacturers are making substantial investments in expanding their production capabilities and improving insulin delivery technologies to meet the rising demand for diabetes management solutions. As both local and international companies continue to innovate and compete, the Chinese human insulin market is expected to experience heightened competition, with pricing, product accessibility, and technological advancements playing critical roles in determining market success.
Recent Developments
- In April 2025, Novo Nordisk announced the discontinuation of Human Mixtard, India’s largest-selling human insulin brand, as part of a global strategy to prioritize newer, patented diabetes and weight loss therapies such as Ozempic and Wegovy. While vial forms of Mixtard, Actrapid, and Insulatard will remain available, pen devices (Penfills and FlexPens) are being phased out, which is expected to disrupt patient access and preference in India.
- In April 2025, Pfizer discontinued the development of danuglipron, its once-daily oral GLP-1 receptor agonist for obesity and type 2 diabetes, following a case of drug-induced liver injury and after reviewing clinical and regulatory feedback. This decision halts further clinical development for both obesity and diabetes indications.
- In March 2025, Biocon Biologics entered a strategic collaboration with Civica, Inc. to expand access to Insulin Aspart in the United States. Biocon will supply the drug substance, which Civica will formulate and commercialize after completing development and clinical trials.
- In December 2024, Lupin acquired the Huminsulin® portfolio in India from Eli Lilly and Company. The range includes Insulin Human (Huminsulin R, NPH, 50/50, and 30/70) and is indicated for type 1 and type 2 diabetes. Lupin had previously marketed these products under a distribution agreement, and the acquisition is aimed at strengthening its diabetes portfolio.
- In November 2024, MannKind’s Afrezza® (insulin human) Inhalation Powder received approval from India’s CDSCO. MannKind expects to ship product to its partner Cipla by the end of 2025.
- In October 2024, Wockhardt filed for approval of its fast-acting insulin analog, Aspart injection (ASPARAPID™), with the Drugs Controller General of India (DCGI). The product, developed indigenously, will be offered in cartridges, vials, and prefilled disposable pens. This expands Wockhardt’s diabetes biosimilars portfolio and addresses a market with limited competition.
Market Concentration & Characteristics
The market concentration of China’s human insulin sector is moderately concentrated, with a few dominant global players and strong local competitors. Large multinational pharmaceutical companies hold a significant share, primarily due to their well-established insulin products and extensive distribution networks. However, local manufacturers have been gaining ground, particularly with the increasing availability of affordable biosimilar insulin. These local players are contributing to market fragmentation by offering cost-effective alternatives and competing on price sensitivity, catering to a large population with varying economic capacities. The market is also characterized by rapid technological advancements in insulin delivery devices, such as insulin pens, pumps, and continuous glucose monitoring systems, driving innovation. Additionally, the Chinese government's policies favoring affordable diabetes care and expanding healthcare access have created a favorable environment for both multinational and local companies to thrive. As a result, while the market is dominated by a few key players, it remains dynamic and competitive, with increasing opportunities for innovation and growth.
Report Coverage
The research report offers an in-depth analysis based on Device, Indication, Insulin, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for human insulin in China is expected to continue growing, driven by the increasing prevalence of diabetes.
- The adoption of biosimilar insulin will rise, offering more affordable treatment options to a larger population.
- Advanced insulin delivery systems, such as smart insulin pens and pumps, will see higher adoption, improving treatment precision.
- The market will experience further government support through initiatives aimed at enhancing diabetes care and affordability.
- Innovation in insulin formulations, including longer-acting and faster-acting insulins, will improve treatment outcomes.
- Local manufacturers will continue to expand their market share by offering competitive, cost-effective insulin products.
- Regional healthcare access will improve, leading to increased insulin availability in both urban and rural areas.
- Increased awareness and education about diabetes management will encourage more people to seek insulin therapy.
- Technological advancements in continuous glucose monitoring will drive demand for more integrated diabetes management systems.
- Multinational companies will strengthen their presence through strategic investments and partnerships, further intensifying market competition.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Diabetes
China has the highest number of diabetics globally, with over 140 million people affected. Urbanization and lifestyle changes are increasing the incidence of type 2 diabetes, directly boosting demand for human insulin therapies.
Aging Population
The proportion of individuals aged 60 and above in China is steadily increasing, and older adults are more susceptible to diabetes. This demographic shift is expanding the patient pool requiring insulin treatment.
Government Initiatives and Healthcare Improvements
Chinese government policies are improving diabetes management, subsidizing insulin prices, and expanding health insurance coverage, making insulin more accessible and supporting market growth.
Technological Advancements and Biosimilars
Innovations in insulin delivery systems (such as pens and pumps) and the growing adoption of biosimilar insulins are making diabetes management more convenient and affordable, driving wider adoption and market expansion.
Expansion of Healthcare Infrastructure in Urban Centers
Major cities like Beijing, Shanghai, Guangzhou, and Shenzhen are experiencing rapid healthcare infrastructure development, leading to increased diagnosis, treatment, and demand for advanced insulin products.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the China Human Insulin?
What factors are driving the growth of the China Human Insulin?
What are the key segments within the China Human Insulin?
Who are the major players in the China Human Insulin?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Device
- 1.2.1 Pens
- 1.2.2 Syringes
- 1.2.3 Others (Pumps, CGMs)
- 1.3 By Indication
- 1.3.1 Type 1 Diabetes
- 1.3.2 Type 2 Diabetes
- 1.3.3 Gestational Diabetes
- 1.4 By Insulin Type
- 1.4.1 Rapid-acting insulin
- 1.4.2 Short-acting insulin
- 1.4.3 Intermediate-acting insulin
- 1.4.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 2,550.64 million → 2032: USD 4,472.55 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 China Human Insulin Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 China Human Insulin Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 China Human Insulin Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 China Human Insulin Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 China Human Insulin Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 China Human Insulin Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 China Human Insulin Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 China Human Insulin Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 2,550.64 million → 2032: USD 4,472.55 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 China Human Insulin Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Device - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Pens
- 12.3.7.2 Syringes
- 12.3.7.3 Others (Pumps, CGMs)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Indication - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Type 1 Diabetes
- 12.4.7.2 Type 2 Diabetes
- 12.4.7.3 Gestational Diabetes
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Insulin Type - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Rapid-acting insulin
- 12.5.7.2 Short-acting insulin
- 12.5.7.3 Intermediate-acting insulin
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 China Human Insulin Geographic Market Outlook, 2023-2032
- 13.1 Domestic Market Distribution and Demand Clusters
- 13.2 State- or Province-Wise Market Size and Forecast, 2023-2032
- 13.3 City and Metropolitan Market Outlook
- 13.4 Industrial, Manufacturing and Commercial Clusters
- 13.5 Geographic Concentration of Key End Users
- 13.6 Local Pricing and Purchasing Differences
- 13.7 Domestic Production Facilities and Capacity Map
- 13.8 Local Infrastructure and Project Pipeline
- 13.9 State-Level Policy and Incentive Differences
- 13.10 Subnational Investment Hotspots and Opportunities
- 13.11 Distribution and Logistics Networks
- 13.12 Domestic Competitive Footprint
Chapter 14 China Human Insulin Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2023-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 China Human Insulin Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2023
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2023-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Novo Nordisk A/S
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Eli Lilly and Company
- 17.4 Pfizer
- 17.5 Gan & Lee Pharmaceuticals
- 17.6 Tonghua Dongbao Pharmaceutical Co., Ltd
- 17.7 Sanofi
- 17.8 Biocon
- 17.9 Wockhardt
- 17.10 Lupin
- 17.11 MannKind Corporation
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

