
Chronic Pain Treatment Market Overview:
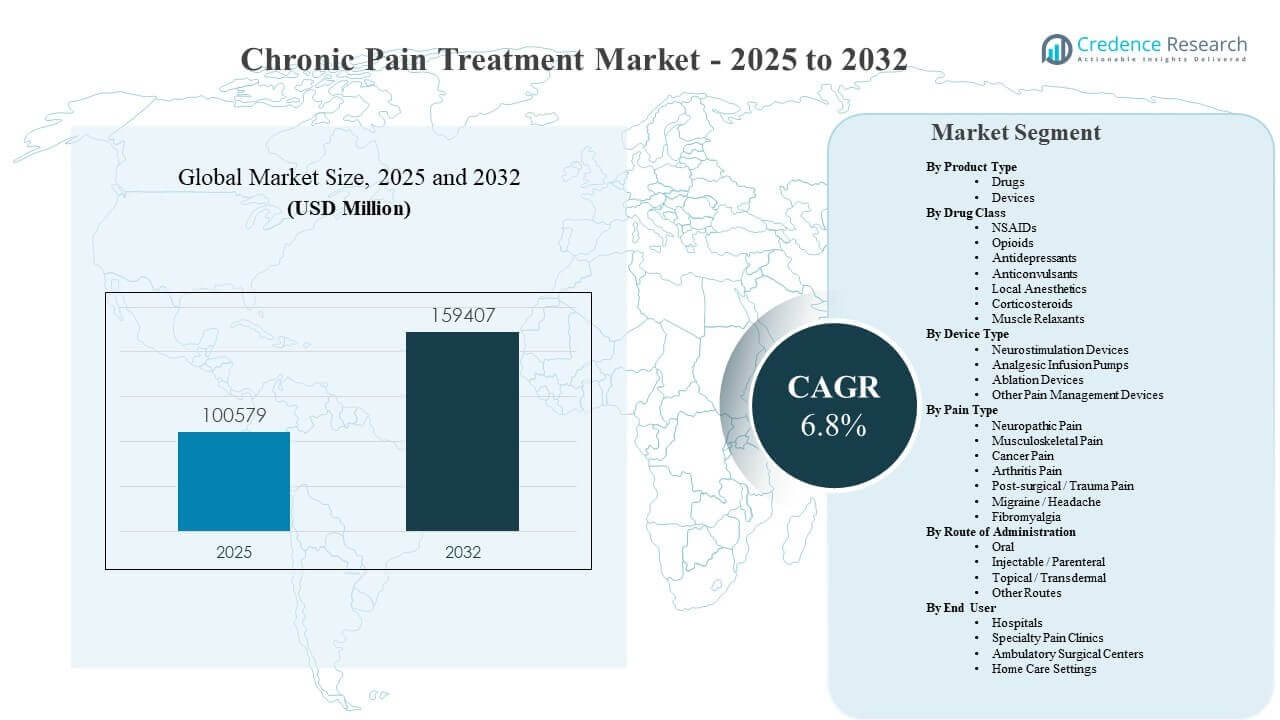
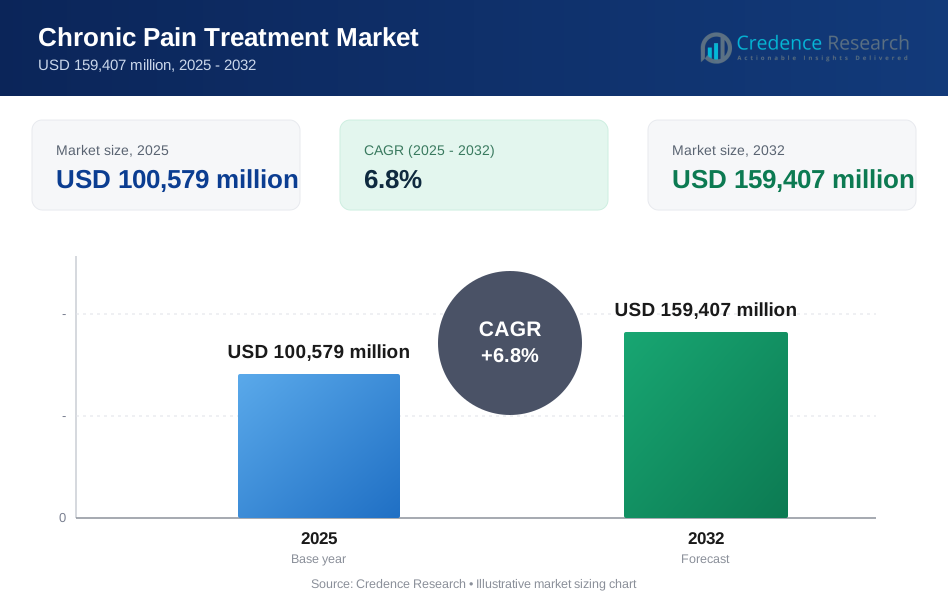
The global Chronic Pain Treatment Market size was estimated at USD 100,579 million in 2025 and is expected to reach USD 159,407 million by 2032, growing at a CAGR of 6.8% from 2025 to 2032. Demand is being driven by the rising prevalence of long-duration musculoskeletal, neuropathic, arthritis, migraine, cancer-related, and post-surgical pain conditions that require sustained symptom control and periodic escalation to specialist care. Increasing preference for opioid-sparing regimens and wider availability of interventional options is also expanding treatment pathways across hospitals, specialty pain clinics, and ambulatory settings.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Chronic Pain Treatment Market Size 2025 | USD 100,579 million |
| Chronic Pain Treatment Market, CAGR | 6.8% |
| Chronic Pain Treatment Market Size 2032 | USD 159,407 million |
Key Market Trends & Insights
- The Chronic Pain Treatment Market is projected to expand at a CAGR of 6.8% from 2025–2032, reflecting sustained therapy demand across chronic pain indications.
- Devices accounted for the largest product-type share of 51.3% in 2025, indicating stronger uptake of procedure-led pain management for refractory patients.
- Neuropathic pain led pain-type contribution at 32.2% in 2025, supported by high volumes in diabetes-linked neuropathy and nerve injury-related pain.
- Hospitals represented 38.9% share in 2025, reflecting continued concentration of advanced pain procedures and complex case management in institutional settings.
- North America accounted for 39.8% of revenue in 2025, supported by higher treatment intensity and access to advanced interventional pain technologies.
Segment Analysis
Chronic pain management is typically delivered through a combination of pharmacological therapy and device-led interventions, with care escalation driven by symptom severity, functional impact, and response to first-line regimens. A growing portion of long-duration patients moves toward interventional pathways when oral and topical options provide incomplete relief, which reinforces demand for neurostimulation, infusion-based approaches, and ablation therapies. The shift toward multimodal pain protocols also increases the combined utilization of non-opioid drug classes, targeted local therapies, and procedure-based solutions across specialist settings.
Treatment selection also differs by care setting and disease burden. Hospitals and specialty pain clinics manage higher-acuity patients, including neuropathic pain, cancer pain, and post-surgical or trauma-associated pain requiring procedural intervention and closer monitoring. Ambulatory surgical centers continue to take on a larger role in outpatient procedures where patient throughput and cost control are priorities. Home care settings are increasingly relevant for long-term therapy continuation, adherence support, and follow-up management for stable patients.
By Product Type Insights
Devices accounted for the largest share of 51.3% in 2025. Device leadership is reinforced by growing clinical acceptance of interventional pain pathways for patients with inadequate response to first-line pharmacotherapy. Expanding physician familiarity with neuromodulation and minimally invasive techniques improves referral volumes from primary and specialty care. Broader payer focus on functional outcomes and opioid-sparing strategies increases the relevance of device-led approaches in chronic pain care.
By Drug Class Insights
NSAIDs, opioids, antidepressants, anticonvulsants, local anesthetics, corticosteroids, muscle relaxants, and other drug classes remain essential to chronic pain therapy selection. NSAIDs maintain wide use across arthritis pain and musculoskeletal pain due to established clinical familiarity and accessibility. Antidepressants and anticonvulsants are increasingly positioned for neuropathic pain management as part of multimodal regimens. Local anesthetics and topical or transdermal products are utilized to limit systemic exposure in long-duration therapy, especially in localized pain conditions.
By Device Type Insights
Neurostimulation devices remain the most strategically important device category within chronic pain management devices. Adoption is strengthened by improvements in programming approaches, therapy personalization, and clinical confidence in managing refractory chronic pain conditions. Analgesic infusion pumps retain relevance in complex pain cases that require controlled delivery workflows and ongoing monitoring. Ablation devices support interventional pain strategies for selected etiologies, particularly where procedural pain relief pathways align with specialist practice patterns.
By Pain Type Insights
Neuropathic Pain accounted for the largest share of 32.2% in 2025. High patient volumes in diabetes-associated neuropathy and other nerve-related pain conditions sustain consistent demand for adjuvant drug classes and specialist-led intervention. Neuropathic pain often requires titration and combination therapy, supporting steady utilization across multiple treatment classes. Referral to pain clinics also increases for refractory neuropathic pain, strengthening the role of device-based options in advanced care pathways.
By Route of Administration Insights
Oral, injectable or parenteral, topical or transdermal, and other routes coexist in chronic pain management based on treatment duration, safety considerations, and patient adherence needs. Oral therapy remains central for long-term outpatient management due to convenience and routine dosing practices. Injectable approaches are used in acute flares, procedure-linked protocols, and specialist care scenarios that require rapid symptom control. Topical and transdermal routes support localized pain relief and are often preferred when minimizing systemic exposure is clinically important.
By End User Insights
Hospitals accounted for the largest share of 38.9% in 2025. Hospitals lead due to access to multidisciplinary specialists, diagnostic capability, and procedural infrastructure for advanced pain interventions. Complex chronic pain cases requiring escalation, monitoring, and combination therapy are more frequently managed in hospital-linked settings. Hospitals also serve as referral hubs for interventional pain management, supporting higher procedure volumes relative to other end-user settings.
Chronic Pain Treatment Market Drivers
Rising chronic disease burden and aging populations
Chronic pain prevalence increases with aging demographics and higher incidence of arthritis, musculoskeletal degeneration, neuropathic disorders, and cancer survivorship. These conditions often require long-duration treatment planning that blends symptom control with functional improvement goals. Recurrent flare cycles sustain repeat utilization across oral, topical, and injectable therapies. Aging also increases comorbidity complexity, pushing more patients into specialist pathways that include procedure-based pain management solutions.
Opioid-sparing care pathways and multimodal therapy protocols
Health systems are strengthening opioid stewardship and emphasizing opioid-sparing strategies for chronic pain. This accelerates adoption of non-opioid regimens including NSAIDs, antidepressants, anticonvulsants, and local anesthetic approaches. Multimodal protocols combine pharmacotherapy with physical rehabilitation, behavioral support, and targeted interventions based on pain phenotype. The result is broader use of complementary treatment classes and greater clinical openness to device-led escalation when outcomes are insufficient.
- For instance, Boston Scientific reported that in a FAST therapy clinical evaluation, 29 of 33 patients, or 88%, responded well and experienced highly significant pain relief, supporting the role of device-based therapy within opioid-sparing multimodal care pathways.
Expansion of interventional pain management capacity
Growth in interventional pain practices increases the availability of neurostimulation, infusion-based delivery, and ablation procedures. Broader specialist coverage improves referral rates for refractory neuropathic and musculoskeletal pain. Procedure settings are also diversifying as ambulatory surgical centers increase outpatient capacity for selected interventions. Better patient selection tools and standardized care pathways support consistent utilization and strengthen the role of devices in chronic pain treatment.
Technology innovation in neuromodulation and procedure platforms
Device innovation is improving therapy personalization, programming efficiency, and long-term management in chronic pain intervention. Advances in stimulation algorithms and treatment optimization support stronger clinical confidence and patient acceptance. Miniaturization and workflow improvements can reduce procedural complexity and expand eligible patient populations. These technology factors help shift a portion of chronic pain management from repeated medication escalation to longer-duration interventional solutions when appropriate.
- For instance, Medtronic’s FDA-approved Inceptiv closed-loop spinal cord stimulator senses the body’s response to stimulation 50 times per second and automatically adjusts output in real time, while also supporting both 1.5T and 3T full-body MRI compatibility under specified conditions, demonstrating measurable progress in therapy personalization and long-term management capabilities.
Chronic Pain Treatment Market Challenges
Chronic pain treatment remains constrained by variability in diagnosis, pain phenotype classification, and response to therapy. Many patients cycle through multiple drug classes before achieving acceptable control, which increases discontinuation risk and reduces consistency of outcomes. Safety concerns and tolerance issues can limit long-term adherence, especially in polypharmacy scenarios. Uneven access to specialist care and interventional procedures also slows adoption in markets with limited pain management infrastructure.
Reimbursement complexity and cost sensitivity continue to influence therapy selection, especially for device-led interventions and repeated procedures. Payer policies may require step therapy and prolonged documentation before approving advanced neuromodulation or specialized interventions. Provider training requirements and procedural capacity constraints can create access bottlenecks for eligible patients. Regional variation in healthcare funding and referral pathways also leads to unequal adoption across hospitals, clinics, and ambulatory settings.
- For instance, Aetna’s spinal cord stimulation policy requires patients to have failed at least 6 months of conservative pain management, completed at least 6 weeks of formal in-person physical therapy within the past year, and then demonstrate at least 50% pain reduction during a 3- to 7-day percutaneous trial before permanent implantation is covered, illustrating how payer criteria can delay access to advanced pain procedures.
Chronic Pain Treatment Market Trends and Opportunities
Increasing integration of personalized pain management pathways is improving treatment targeting and long-term outcomes. Clinicians are aligning therapy choice with pain phenotype, comorbidity profile, and functional goals, which strengthens multimodal care models. This supports higher use of adjuvant drug classes for neuropathic pain and targeted local therapies for localized pain. As care becomes more structured, specialist referral timing can improve and accelerate appropriate escalation to interventional options.
- For instance, Abbott's Proclaim™ Dorsal Root Ganglion (DRG) stimulation system, evaluated through the ACCURATE study the largest randomized, head-to-head controlled neuromodulation trial for focal chronic pain demonstrated an 81.4% average reduction in pain scores at 12 months, with over 80% of patients achieving significant pain relief.
Outpatient procedure growth is creating opportunities for interventional device utilization beyond hospital settings. Ambulatory surgical centers are expanding capacity for selected pain procedures where safety profiles and recovery pathways align with outpatient delivery. Broader patient awareness and clinician confidence in neuromodulation can expand adoption for refractory chronic pain subgroups. Home care monitoring and follow-up models can also improve long-term therapy continuity and adherence after interventions.
Regional Insights
North America
North America led the Chronic Pain Treatment Market with 39.8% share in 2025. High treatment intensity, deeper specialist availability, and stronger access to interventional pain procedures support revenue concentration. Hospitals and specialty pain clinics drive procedural volumes for complex neuropathic, musculoskeletal, and post-surgical pain cases. Continued focus on opioid stewardship reinforces demand for non-opioid regimens and device-led escalation where clinically appropriate.
Europe
Europe accounted for 25.6% share in 2025. Large chronic disease burden and aging populations support sustained pharmacological demand across arthritis, neuropathic pain, and musculoskeletal pain. Adoption of interventional approaches varies by country due to differences in reimbursement pathways and specialist capacity. Hospitals and structured care systems sustain steady utilization of pain therapies and support gradual expansion of advanced interventions.
Asia Pacific
Asia Pacific represented 23.4% share in 2025. Large patient volumes and expanding access to care support rising treatment demand across common chronic pain indications. Growth is reinforced by improving hospital infrastructure and broader availability of specialist services in major urban markets. Device adoption is increasing, but base-year intensity is moderated by affordability, uneven referral pathways, and variable access to interventional pain management outside leading centers.
Latin America
Latin America held 6.6% share in 2025. Demand is supported by chronic musculoskeletal conditions, arthritis pain, and migraine management, with strong reliance on pharmacological therapy. Access to advanced interventional options remains more limited due to reimbursement constraints and uneven specialist coverage. Growth opportunities are linked to improving healthcare access, expanding private-sector specialty care, and gradual procedural capacity build-out.
Middle East & Africa
Middle East & Africa accounted for 4.6% share in 2025. Revenue is concentrated in markets with stronger healthcare funding and specialist availability, particularly in select Gulf countries and South Africa. Broader regional adoption is constrained by access limitations, affordability challenges, and limited interventional pain infrastructure. Demand remains primarily anchored in drug therapy, with gradual expansion of specialist services in higher-investment markets.
Competitive Landscape
Competition in chronic pain treatment spans large pharmaceutical portfolios, diversified medtech platforms, and specialized neuromodulation-focused players. Market positioning is shaped by breadth of indication coverage, safety and tolerability profiles, physician familiarity, and the ability to support integrated pain care pathways. Device competition increasingly emphasizes therapy personalization, workflow efficiency, and evidence-backed outcomes that support payer coverage. Companies also compete through specialist engagement, training programs, and ecosystem offerings that connect devices with follow-up management.
Pfizer Inc. maintains relevance in chronic pain treatment through broad therapeutic capabilities and commercialization strength across prescription medicines that are used in chronic disease management environments. Pfizer Inc. benefits from scale in clinical development, global market access, and established relationships across hospital and outpatient care settings. The company’s positioning is strengthened by the ability to support multimodal care approaches where pain therapy is managed alongside chronic comorbidities. Pfizer Inc. also competes through lifecycle strategies and channel reach across major regions.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Pfizer Inc.
- Eli Lilly and Company
- Johnson & Johnson
- Novartis AG
- Sanofi
- Teva Pharmaceutical Industries Ltd.
- Merck & Co., Inc.
- Abbott Laboratories
- Baxter International Inc.
- Boston Scientific Corporation
- Medtronic plc
- Abbott Neuromodulation
- Nevro Corp.
- Stryker Corporation
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Developments
- In March 2026, Grünenthal entered into a definitive agreement with BCWorld Pharm Co., Ltd., granting BCWorld exclusive South Korean rights to Qutenza, a topical, non-systemic, non-opioid patch treatment. Qutenza is indicated in Europe for the management of peripheral neuropathic pain, making this a notable partnership in the broader chronic pain treatment space.
- In February 2026, Grünenthal and Clinect Pty Ltd announced a definitive agreement under which Clinect received exclusive Australian rights to Qutenza. This partnership expands the geographic reach of Grünenthal’s non-opioid pain treatment portfolio in peripheral neuropathic pain management.
- In May 2025, electroCore Inc. acquired NeuroMetrix Inc. to strengthen its position in the non-invasive bioelectronic therapy market. Through this acquisition, electroCore added NeuroMetrix’s Quell platform, which is focused on chronic pain and wellness applications, including use cases tied to fibromyalgia and veterans’ care.
- In February 2025, Globus Medical acquired Nevro in a deal valued at USD 250 million, combining orthopedic hardware capabilities with neuromodulation technologies. The transaction was highlighted as a strategic move to build more integrated spinal repair and pain-relief solutions within the chronic pain treatment market
Report Scope
| Report Attribute | Details |
| Market size value in 2025 | USD 100,579 million |
| Revenue forecast in 2032 | USD 159,407 million |
| Growth rate (CAGR) | 6.8% (2025–2032) |
| Base year | 2025 |
| Forecast period | 2026-2032 |
| Quantitative units | USD million |
| Segments covered | By Product Type Outlook: Drugs, Devices; By Drug Class Outlook: NSAIDs, Opioids, Antidepressants, Anticonvulsants, Local Anesthetics, Corticosteroids, Muscle Relaxants, Other Drug Classes; By Device Type Outlook: Neurostimulation Devices, Analgesic Infusion Pumps, Ablation Devices, Other Pain Management Devices; By Pain Type Outlook: Neuropathic Pain, Musculoskeletal Pain, Cancer Pain, Arthritis Pain, Post-surgical / Trauma Pain, Migraine / Headache, Fibromyalgia, Other Chronic Pain Conditions; By Route of Administration Outlook: Oral, Injectable / Parenteral, Topical / Transdermal, Other Routes; By End User Outlook: Hospitals, Specialty Pain Clinics, Ambulatory Surgical Centers, Home Care Settings |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Key companies profiled | Pfizer Inc.; Eli Lilly and Company; Johnson & Johnson; Novartis AG; Sanofi; Teva Pharmaceutical Industries Ltd.; Merck & Co., Inc.; Abbott Laboratories; Baxter International Inc.; Boston Scientific Corporation; Medtronic plc; Abbott Neuromodulation; Nevro Corp.; Stryker Corporation |
| No.of Pages | 342 |
Segmentation
BY PRODUCT TYPE
- Drugs
- Devices
BY DRUG CLASS
- NSAIDs
- Opioids
- Antidepressants
- Anticonvulsants
- Local Anesthetics
- Corticosteroids
- Muscle Relaxants
- Other Drug Classes
BY DEVICE TYPE
- Neurostimulation Devices
- Analgesic Infusion Pumps
- Ablation Devices
- Other Pain Management Devices
BY PAIN TYPE
- Neuropathic Pain
- Musculoskeletal Pain
- Cancer Pain
- Arthritis Pain
- Post-surgical / Trauma Pain
- Migraine / Headache
- Fibromyalgia
- Other Chronic Pain Conditions
BY ROUTE OF ADMINISTRATION
- Oral
- Injectable / Parenteral
- Topical / Transdermal
- Other Routes
BY END USER
- Hospitals
- Specialty Pain Clinics
- Ambulatory Surgical Centers
- Home Care Settings
BY REGION
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Chronic Disease Burden and Aging Populations
The increasing prevalence of chronic conditions such as arthritis, neuropathic disorders, and cancer, particularly among aging populations, is driving sustained demand for long-term pain management solutions and escalating the need for both pharmacological and device-based therapies.
Opioid-Sparing Care Pathways and Multimodal Therapy Protocols
Healthcare systems are prioritizing opioid stewardship, leading to greater adoption of non-opioid regimens and multimodal protocols that combine drugs, devices, and rehabilitation, thereby expanding the market for alternative chronic pain treatments.
Expansion of Interventional Pain Management Capacity
Growth in interventional pain practices and broader specialist coverage are increasing the availability and utilization of neurostimulation, infusion-based, and ablation procedures, especially for patients with refractory pain, thus boosting device segment growth.
Technology Innovation in Neuromodulation and Procedure Platforms
Advancements in device technology, such as improved neurostimulation algorithms and miniaturized, personalized therapy platforms, are enhancing clinical outcomes and patient acceptance, supporting a shift from repeated medication escalation to longer-duration interventional solutions.
Increasing Integration of Personalized Pain Management Pathways
Clinicians are increasingly aligning therapy choices with individual pain phenotypes and comorbidity profiles, which supports higher use of adjuvant drug classes and targeted interventions, improving long-term outcomes and driving market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size and forecast for the Chronic Pain Treatment Market?
What is the CAGR of the Chronic Pain Treatment Market?
What is the largest segment in the Chronic Pain Treatment Market?
What factors are driving growth in the Chronic Pain Treatment Market?
Who are the leading companies in the Chronic Pain Treatment Market?
Which region leads the Chronic Pain Treatment Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Hospitals
- 1.2.2 Specialty Pain Clinics
- 1.2.3 Ambulatory Surgical Centers
- 1.2.4 Home Care Settings
- 1.3 By Pain Type
- 1.3.1 Neuropathic Pain
- 1.3.2 Musculoskeletal Pain
- 1.3.3 Cancer Pain
- 1.3.4 Arthritis Pain
- 1.3.5 Post-surgical / Trauma Pain
- 1.3.6 Migraine / Headache
- 1.3.7 Fibromyalgia
- 1.3.8 Other Chronic Pain Conditions
- 1.4 By Product Type
- 1.4.1 Drugs
- 1.4.2 Devices
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 100,579 million → 2032: USD 159,407 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2025
- 2.6.2 Forecast Period: 2025-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Chronic Pain Treatment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Chronic Pain Treatment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2025-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2025-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Chronic Pain Treatment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2025-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Chronic Pain Treatment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Chronic Pain Treatment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Chronic Pain Treatment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Chronic Pain Treatment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Chronic Pain Treatment Market Outlook, 2025-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 100,579 million → 2032: USD 159,407 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Chronic Pain Treatment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2025-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2025-2032
- 12.3.4 Volume Forecast, 2025-2032
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Specialty Pain Clinics
- 12.3.7.3 Ambulatory Surgical Centers
- 12.3.7.4 Home Care Settings
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Pain Type - Market Size and Forecast, 2025-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2025-2032
- 12.4.4 Volume Forecast, 2025-2032
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Neuropathic Pain
- 12.4.7.2 Musculoskeletal Pain
- 12.4.7.3 Cancer Pain
- 12.4.7.4 Arthritis Pain
- 12.4.7.5 Post-surgical / Trauma Pain
- 12.4.7.6 Migraine / Headache
- 12.4.7.7 Fibromyalgia
- 12.4.7.8 Other Chronic Pain Conditions
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2025-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2025-2032
- 12.5.4 Volume Forecast, 2025-2032
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Drugs
- 12.5.7.2 Devices
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Chronic Pain Treatment End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Chronic Pain Treatment Geographic Market Outlook, 2025-2032
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Chronic Pain Treatment Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Chronic Pain Treatment Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Pfizer Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Eli Lilly and Company
- 18.4 Johnson & Johnson
- 18.5 Novartis AG
- 18.6 Sanofi
- 18.7 Teva Pharmaceutical Industries Ltd.
- 18.8 Merck & Co., Inc.
- 18.9 Abbott Laboratories
- 18.10 Boston Scientific Corporation
- 18.11 Medtronic plc
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

