
Market Overview:
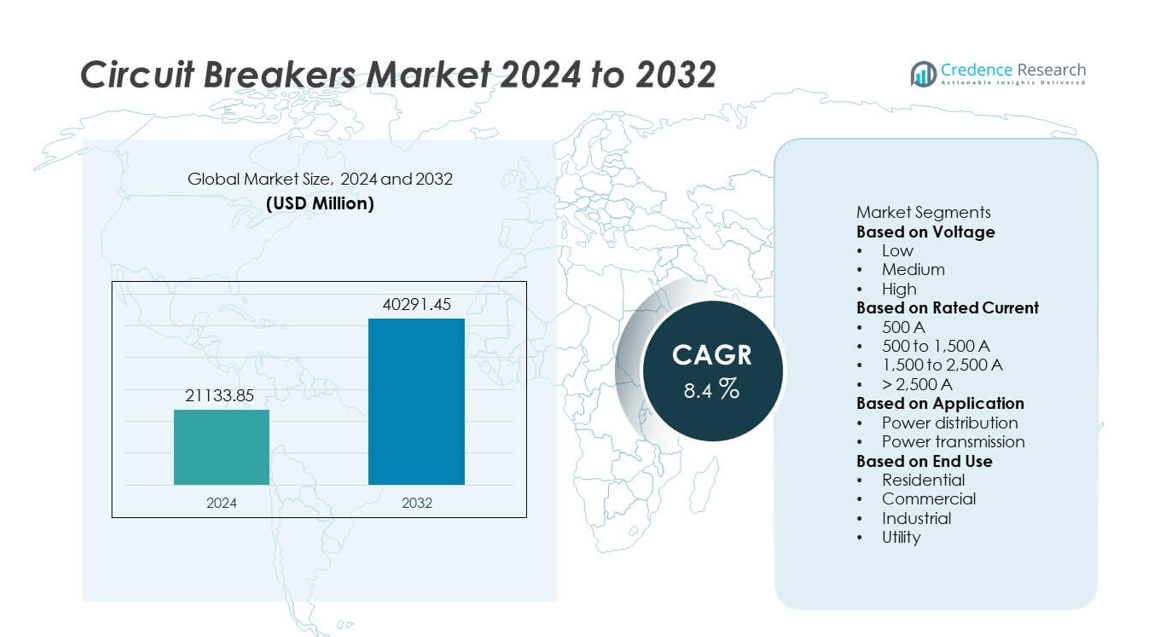
The global circuit breakers market was valued at USD 21,133.85 million in 2024 and is projected to reach USD 40,291.45 million by 2032, expanding at a compound annual growth rate (CAGR) of 8.4% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Circuit Breakers Market Size 2024 | USD 21,133.85 million |
| Circuit Breakers Market, CAGR | 8.4% |
| Circuit Breakers Market Size 2032 | USD 40,291.45 million |
The circuit breakers market is led by major players including ABB, Eaton, Mitsubishi Electric, General Electric, HD Hyundai Electric, LS Electric, CG Power, Powell Industries, Kirloskar Electric, and Alfanar Group. These companies dominate through advanced technologies, smart grid integration, and expansion into sustainable, SF₆-free solutions. Asia-Pacific emerged as the leading region with a 34.8% market share in 2024, driven by rapid industrialization, urbanization, and renewable energy projects. North America followed with 27.6%, supported by grid modernization and digital infrastructure upgrades. Europe held 25.3%, propelled by energy transition goals and adoption of environmentally compliant circuit protection systems.
Market Insights
- The global circuit breakers market was valued at USD 21,133.85 million in 2024 and is projected to reach USD 40,291.45 million by 2032, growing at a CAGR of 8.4%.
- Key drivers include rising investments in power infrastructure, growing renewable energy integration, and increased emphasis on electrical safety and smart grid modernization.
- Major trends involve the adoption of IoT-enabled breakers, digital monitoring systems, and a shift toward SF₆-free eco-friendly solutions in line with sustainability targets.
- The market is highly competitive with leading companies such as ABB, Eaton, Mitsubishi Electric, General Electric, and HD Hyundai Electric focusing on product innovation and smart technologies.
- Asia-Pacific held the largest regional share of 34.8% in 2024, followed by North America with 27.6% and Europe with 25.3%, while the low-voltage segment dominated the market with a 52.4% share due to high demand in commercial and residential sectors.
Market Segmentation Analysis:
By Voltage
Low-voltage circuit breakers dominated the market with a 52.4% share in 2024. Their widespread use in residential, commercial, and light industrial applications drives this dominance. These breakers ensure protection against overload and short circuits in low-voltage systems up to 1 kV. The segment benefits from rapid urbanization, smart grid integration, and renewable power expansion. Increasing investments in building automation and compact breaker technologies further strengthen growth. Medium- and high-voltage segments are expanding steadily due to rising utility and transmission infrastructure development across developing economies.
- For instance, ABB introduced the SACE Emax 3 air circuit breaker featuring integrated sensors and digital trip units capable of managing up to 6,300 A and interrupting fault currents of 150 kA. This model enhances reliability in smart grids and industrial low-voltage applications through built-in communication and predictive maintenance functions.
By Rated Current
The 500 to 1,500 A rated current segment held the largest share of 41.8% in 2024. This range is widely preferred for medium-scale industrial and commercial power systems, offering a balance of performance, reliability, and cost efficiency. Growing installation of backup power systems and renewable energy inverters contributes to segment expansion. Circuit breakers within this current range are increasingly integrated with digital monitoring and arc fault detection systems. Meanwhile, breakers above 2,500 A are gaining attention in heavy industrial and grid-scale installations requiring higher fault tolerance and operational safety.
- For instance, Eaton launched its Power Defense MCCB series supporting rated currents up to 1,600 A, equipped with PXR trip units and embedded communication modules. These breakers feature onboard energy metering with ±1% accuracy and fault diagnostics, improving protection reliability in distributed power networks.
By Application
Power distribution accounted for the dominant share of 56.7% in 2024, driven by large-scale adoption in residential, commercial, and industrial facilities. The growing need for stable and secure power delivery across decentralized networks supports this segment’s leadership. Smart distribution networks, automation, and IoT-based fault management systems further enhance breaker deployment. Rising electrification in developing regions and infrastructure modernization projects are also propelling demand. Power transmission applications are expanding as utilities focus on grid reliability and high-voltage network upgrades to accommodate renewable energy integration.
Key Growth Drivers
Rising Investments in Power Infrastructure
Global expansion of power generation and distribution networks is a major growth catalyst for circuit breakers. Governments are modernizing aging grids and developing high-voltage transmission lines to meet rising electricity demand. Rapid urbanization and industrialization in Asia-Pacific and the Middle East further boost installations of low- and medium-voltage breakers. The shift toward renewable energy integration, such as solar and wind farms, also increases the need for reliable protection systems, ensuring uninterrupted operation and grid stability across diverse power networks.
- For instance, HD Hyundai Electric supplied over 200 high-voltage gas-insulated switchgear units rated up to 245 kV for grid expansion projects in Saudi Arabia. These breakers were designed to withstand fault currents of 40 kA and improve the reliability of large-scale solar and wind power interconnections.
Growing Emphasis on Safety and Reliability
The increasing focus on electrical safety and operational reliability is driving circuit breaker adoption in both commercial and industrial sectors. These devices prevent equipment damage and electrical hazards caused by overloads or short circuits. Advanced features such as arc fault detection, remote monitoring, and automatic fault isolation are gaining traction. Manufacturers are incorporating digital protection systems and predictive maintenance capabilities to reduce downtime and enhance performance, aligning with global safety regulations and standards in energy-intensive industries.
- For instance, Schneider Electric developed its PremSet medium-voltage switchgear equipped with vacuum circuit breakers rated at up to 12 kV (or up to 15 kV/17.5 kV in some versions) and embedded sensors for real-time temperature and partial discharge monitoring.
Expansion of Smart Grids and Renewable Integration
The rise of smart grid infrastructure and renewable power integration is significantly boosting demand for intelligent circuit breakers. These breakers facilitate real-time monitoring, load balancing, and fault detection across distributed energy systems. Increasing deployment of solar, wind, and microgrid projects requires adaptive protection solutions capable of handling variable loads. The growing use of IoT-enabled and AI-assisted breakers enhances energy efficiency and operational flexibility, supporting global sustainability goals and promoting the transition to a decentralized energy ecosystem.
Key Trends & Opportunities
Adoption of Digital and IoT-Enabled Circuit Breakers
The integration of IoT and digital communication technologies is transforming circuit breaker functionality. Smart breakers equipped with sensors enable real-time fault diagnostics and predictive maintenance, reducing energy losses and downtime. Utilities and industries are adopting these systems to improve efficiency and compliance with energy management standards. This trend supports the development of intelligent power systems, offering lucrative opportunities for manufacturers developing compact, software-integrated circuit protection solutions for advanced industrial and commercial applications.
- For instance, Schneider Electric introduced its Masterpact MTZ air circuit breaker featuring embedded Ethernet and Class 1 energy metering accuracy. The breaker supports up to 6,300 A rated current and integrates with EcoStruxure IoT platform, allowing cloud-based monitoring, fault analytics, and remote firmware updates for predictive maintenance.
Shift Toward Eco-Friendly and SF₆-Free Solutions
Growing environmental concerns are driving the shift from sulfur hexafluoride (SF₆)-based breakers to eco-friendly alternatives. Manufacturers are developing vacuum and gas-insulated designs using sustainable dielectric materials to minimize greenhouse gas emissions. Regulatory frameworks promoting carbon neutrality in power infrastructure are accelerating this transition. The trend opens significant growth opportunities for companies innovating in green circuit breaker technologies that maintain high insulation performance while meeting international environmental standards and supporting clean energy infrastructure.
- For instance, Mitsubishi Electric launched its 72.5 kV vacuum circuit breaker using dry air insulation technology, achieving interruption capability up to 31.5 kA without SF₆ gas. This design reduces greenhouse gas emissions by nearly 99% compared to conventional models while ensuring reliable performance in high-voltage transmission systems.
Key Challenges
High Initial Costs and Maintenance Complexity
Despite their benefits, advanced circuit breakers involve high installation and maintenance costs, particularly for high-voltage applications. The need for specialized components, insulation systems, and skilled labor increases project expenditure. Small and medium-scale utilities often delay upgrades due to budget constraints, limiting market penetration. Additionally, maintaining complex electronic and hybrid systems demands regular monitoring and technical expertise, posing operational challenges in developing regions with limited access to skilled technicians.
Supply Chain Disruptions and Raw Material Volatility
Fluctuating prices of essential materials such as copper, aluminum, and insulating gases affect manufacturing costs for circuit breakers. Global supply chain disruptions caused by geopolitical tensions and logistical delays further impact timely production and delivery. Manufacturers face challenges in balancing inventory, cost control, and meeting growing demand. Dependence on specific material sources and limited local production capabilities in emerging economies increase vulnerability, prompting companies to diversify suppliers and enhance regional manufacturing resilience.
Regional Analysis
North America
North America held a 27.6% share of the global circuit breakers market in 2024, driven by modernization of aging electrical grids and the expansion of renewable energy projects. The United States leads the regional market with strong investments in smart grid infrastructure and industrial automation. Growing adoption of digital and IoT-enabled circuit breakers enhances energy efficiency and safety compliance. Canada’s increasing renewable capacity and demand for medium-voltage breakers in utilities further strengthen growth. Supportive government policies for energy reliability and sustainable infrastructure continue to encourage market expansion across industrial and residential applications.
Europe
Europe accounted for 25.3% of the global circuit breakers market in 2024, supported by rapid transition toward carbon-neutral power systems and grid modernization. Countries such as Germany, France, and the United Kingdom are investing heavily in renewable integration and electric mobility infrastructure. The growing deployment of SF₆-free circuit breakers aligns with the EU’s environmental regulations. Industrial automation, energy-efficient buildings, and smart substations also drive demand. Continuous digital transformation in power distribution systems, coupled with stringent safety standards, reinforces Europe’s position as a leading hub for advanced circuit protection technologies.
Asia-Pacific
Asia-Pacific dominated the global market with a 34.8% share in 2024, driven by large-scale industrialization, urban expansion, and rising electricity consumption. China, India, and Japan are major contributors due to investments in transmission networks and renewable projects. Government initiatives for rural electrification and grid reliability are boosting low- and medium-voltage circuit breaker installations. The growing manufacturing sector and expanding data center infrastructure further elevate demand. Adoption of smart grid systems and eco-friendly breaker technologies positions the region as the fastest-growing market globally, with substantial opportunities in emerging economies.
Latin America
Latin America captured an 8.1% share of the global circuit breakers market in 2024, driven by growing energy demand and infrastructure development across Brazil, Mexico, and Chile. Expanding renewable energy generation and industrialization are key growth enablers. The rise in construction of transmission and distribution networks enhances the adoption of medium- and high-voltage breakers. Governments are prioritizing grid reliability and safety compliance, leading to modernization of existing systems. The growing emphasis on energy-efficient technologies and local manufacturing is further contributing to steady regional growth.
Middle East & Africa
The Middle East and Africa accounted for 4.2% of the global market share in 2024, supported by strong investments in power generation and utility upgrades. The Gulf countries are leading with large-scale renewable and smart city projects that require reliable protection equipment. In Africa, rural electrification initiatives and expanding industrial zones are driving demand for low- and medium-voltage breakers. Increasing grid interconnections and oil and gas infrastructure development further support market growth. Government-backed energy diversification programs and regional manufacturing expansion continue to strengthen the market outlook.
Market Segmentations:
By Voltage
- Low
- Medium
- High
By Rated Current
- 500 A
- 500 to 1,500 A
- 1,500 to 2,500 A
- > 2,500 A
By Application
- Power distribution
- Power transmission
By End Use
- Residential
- Commercial
- Industrial
- Utility
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The circuit breakers market features strong competition among leading manufacturers such as ABB, Eaton, Mitsubishi Electric, General Electric, HD Hyundai Electric, LS Electric, CG Power, Powell Industries, Kirloskar Electric, and Alfanar Group. These companies focus on product innovation, digital integration, and expansion of eco-friendly technologies to strengthen their market presence. The competition is shaped by advancements in smart grid infrastructure, renewable energy integration, and automation-driven industrial demand. Players are investing in IoT-enabled and SF₆-free circuit breaker technologies to meet sustainability goals and regulatory standards. Strategic collaborations, mergers, and regional manufacturing expansions are key tactics to enhance distribution networks and customer reach. Additionally, continuous development of medium- and high-voltage breakers for industrial and utility applications reinforces the leadership of top players while encouraging smaller manufacturers to adopt digital protection systems to remain competitive in the evolving power infrastructure landscape.
Key Player Analysis
- Powell Industries
- Kirloskar Electric
- LS Electric
- Eaton
- General Electric
- HD Hyundai Electric
- ABB
- Mitsubishi Electric
- CG Power
- Alfanar Group
Recent Developments
- In July 2025, ABB unveiled its new air circuit breaker SACE Emax 3, which incorporates built-in real-time power sensors, a touchscreen interface, and complies with IEC 62443 Security Level 2 certification.
- In July 2025, a credit rating rationale update for Kirloskar Electric Company Limited (KECL) was published by CRISIL, noting that the company had been classified as "non-cooperative" by a previous credit rating agency, CARE Ratings Limited, as of March 19, 2025, due to a non-furnishing of information for monitoring of ratings.
- In February 2025, LS Electric participated in the ELECS Korea 2025 (Electric Energy Conference & Show) and the co-located Korea Smart Grid Expo 2025 exhibitions, held from February 12 to 14 in Seoul.
Report Coverage
The research report offers an in-depth analysis based on Voltage, Rated Current, Application, End Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will experience steady growth driven by global power infrastructure modernization.
- Smart grid expansion will accelerate demand for intelligent and IoT-enabled circuit breakers.
- Increasing renewable energy integration will strengthen the need for advanced protection systems.
- Manufacturers will focus on developing SF₆-free and eco-friendly breaker technologies.
- Rising industrial automation will boost adoption of digital and high-performance circuit breakers.
- Emerging economies will invest heavily in power distribution and electrification projects.
- Technological innovation will enhance remote monitoring and predictive maintenance capabilities.
- Strategic collaborations and mergers will support global market expansion.
- Regulatory emphasis on energy efficiency and safety compliance will shape product design.
- Asia-Pacific will remain the dominant regional market, supported by strong manufacturing and infrastructure growth.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Investments in Power Infrastructure
Governments and utilities are modernizing aging grids and expanding transmission lines to meet growing electricity demand, especially in rapidly urbanizing and industrializing regions. This drives significant demand for circuit breakers to ensure reliable and safe power distribution.
Growing Emphasis on Safety and Reliability
Increasing focus on electrical safety and operational reliability in commercial and industrial sectors is boosting adoption of advanced circuit breakers. Features such as arc fault detection, remote monitoring, and predictive maintenance are becoming standard to comply with global safety regulations.
Expansion of Smart Grids and Renewable Integration
The proliferation of smart grid infrastructure and renewable energy projects requires intelligent circuit breakers capable of real-time monitoring, load balancing, and adaptive protection. This trend is accelerating the deployment of IoT-enabled and AI-assisted breakers.
Shift Toward Eco-Friendly and SF₆-Free Solutions
Environmental regulations and sustainability goals are prompting manufacturers to develop SF₆-free and eco-friendly circuit breakers. Adoption of vacuum and gas-insulated designs using sustainable materials is opening new market opportunities and supporting the transition to greener power systems.
Technological Innovation and Digitalization
Advancements in digital monitoring, IoT integration, and predictive maintenance are transforming circuit breaker functionality. Utilities and industries are investing in smart breakers to enhance energy efficiency, reduce downtime, and support the development of intelligent power systems.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Circuit Breakers market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Circuit Breakers market projected to grow between 2025 and 2032?
Which Circuit Breakers market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Circuit Breakers market?
Who are the leading companies in the Circuit Breakers market?
Which region commanded the largest share of the Circuit Breakers market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 Residential
- 1.2.2 Commercial
- 1.2.3 Industrial
- 1.2.4 Utility
- 1.3 By Voltage
- 1.3.1 Low
- 1.3.2 Medium
- 1.3.3 High
- 1.4 By Application
- 1.4.1 Power distribution
- 1.4.2 Power transmission
- 1.5 By Rated Current
- 1.5.1 500 A
- 1.5.2 500 to 1,500 A
- 1.5.3 1,500 to 2,500 A
- 1.5.4 > 2,500 A
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 21,133.85 million → 2032: USD 40,291.45 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Circuit Breakers Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Circuit Breakers Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Circuit Breakers Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Circuit Breakers Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Circuit Breakers Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Circuit Breakers Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Circuit Breakers Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Circuit Breakers Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 21,133.85 million → 2032: USD 40,291.45 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Circuit Breakers Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Residential
- 12.3.7.2 Commercial
- 12.3.7.3 Industrial
- 12.3.7.4 Utility
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Voltage - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Low
- 12.4.7.2 Medium
- 12.4.7.3 High
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Power distribution
- 12.5.7.2 Power transmission
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Rated Current - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 500 A
- 12.6.7.2 500 to 1,500 A
- 12.6.7.3 1,500 to 2,500 A
- 12.6.7.4 > 2,500 A
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Circuit Breakers End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Circuit Breakers Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Circuit Breakers Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Circuit Breakers Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 ABB
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Eaton
- 18.4 Mitsubishi Electric
- 18.5 General Electric
- 18.6 HD Hyundai Electric
- 18.7 LS Electric
- 18.8 CG Power
- 18.9 Powell Industries
- 18.10 Kirloskar Electric
- 18.11 Alfanar Group
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

