
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Clean Label Starch Market Size 2024 | USD 1,710 Million |
| Clean Label Starch Market, CAGR | 5.4% |
| Clean Label Starch Market Size 2032 | USD 2,604.47 Million |
Market Overview:
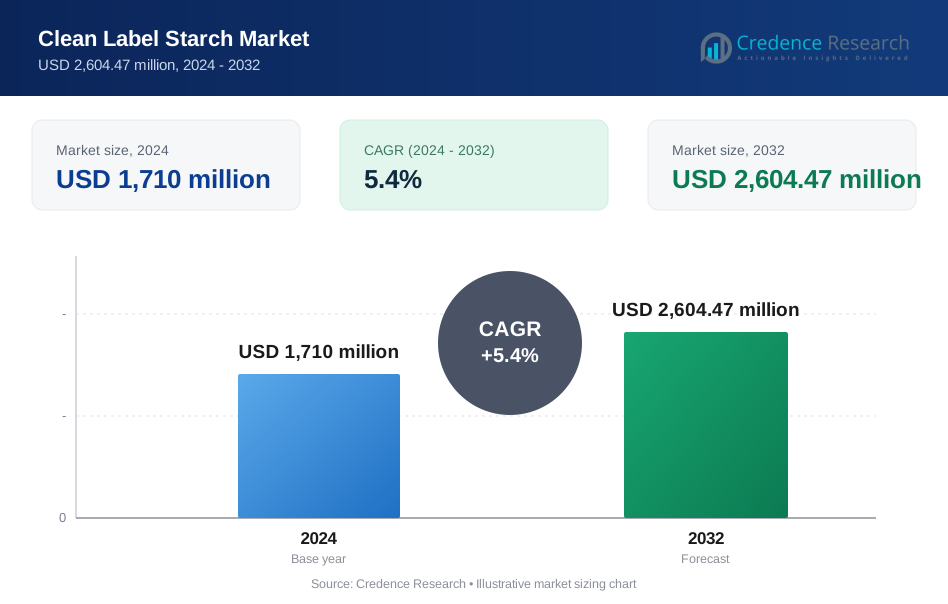
The global Clean Label Starch Market is projected to grow from USD 1,710 million in 2024 to USD 2,604.47 million by 2032, marking a compound annual growth rate (CAGR) of 5.4% during the forecast period. Clean label starches, derived from natural sources such as corn, wheat, and potatoes, offer an appealing alternative to modified starches, aligning with consumers' rising demand for transparency in ingredient labelling. The market's steady expansion reflects the increasing preference for minimally processed, label-friendly ingredients across food and beverage sectors, as well as in personal care and cosmetics.
Several factors drive the growth of the clean label starch market, with consumer demand for natural and healthy food ingredients at the forefront. Health-conscious consumers are increasingly scrutinizing ingredient lists, avoiding artificial additives, and seeking products with natural and recognizable ingredients. Clean label starches offer desirable properties, such as texture improvement and stability, without compromising on natural integrity. Additionally, advancements in food processing technologies have enhanced the functional properties of clean label starches, making them suitable for a wider range of applications. Food manufacturers are leveraging these ingredients to differentiate products and meet evolving consumer expectations, further boosting market growth.
Regionally, North America leads the clean label starch market, fueled by the strong presence of major food processing companies and growing consumer awareness around clean labels. Europe follows closely, with stringent food regulations and high demand for organic and natural food ingredients driving adoption. The Asia-Pacific region is expected to experience the fastest growth due to rising health awareness, urbanization, and the expansion of middle-class income levels, which are increasing demand for premium and natural food products. This regional growth highlights the global shift towards transparency in food labelling, with clean label starches poised to play a critical role in meeting both regulatory standards and consumer expectations across diverse markets.
Market Drivers:
Rising Consumer Demand for Transparency:
A key driver of the clean label starch market is the increasing consumer demand for transparency in food ingredients. As health-conscious consumers become more aware of the ingredients in their products, they are actively seeking out clean label options. According to a survey conducted by Label Insight, 94% of consumers are more likely to be loyal to a brand that offers complete transparency regarding its ingredients. This trend encourages food manufacturers to adopt clean label starches that are naturally derived and minimally processed, thereby appealing to a growing segment of the market.
Health and Wellness Trends:
The growing focus on health and wellness is significantly influencing the clean label starch market. Consumers are increasingly prioritizing diets that are free from artificial additives and preservatives, which drives the demand for clean label products. For instance, a report from the International Food Information Council indicated that 70% of consumers consider the presence of artificial ingredients a major concern when purchasing food products. This shift has prompted manufacturers to reformulate their offerings, incorporating clean label starches that align with consumer preferences for healthier options.
Regulatory Support for Clean Label Initiatives:
Regulatory frameworks promoting transparency and labelling standards are also driving the clean label starch market. Governments worldwide are advocating for clearer labelling practices to inform consumers about food ingredients. For example, the U.S. Food and Drug Administration (FDA) has implemented guidelines that encourage manufacturers to disclose ingredient sourcing and processing methods. Approximately 65% of food manufacturers surveyed by the FDA reported plans to enhance their labelling practices in response to these regulations, further fostering the clean label movement.
Innovation in Starch Production:
Innovation in starch production techniques is a significant factor contributing to the growth of the clean label starch market. Advances in technology have enabled manufacturers to produce clean label starches that maintain functional properties while minimizing processing. Companies like Tate & Lyle have reported significant investments in research and development to create innovative, clean label starch solutions that meet the evolving needs of food producers. This focus on innovation not only enhances product offerings but also ensures that clean label starches can effectively substitute traditional starches without compromising on quality.
Market Trends:
Increasing Adoption of Natural Ingredients:
A prominent trend in the clean label starch market is the increasing adoption of natural ingredients in food formulations. Consumers are seeking products that contain fewer synthetic additives, which has led manufacturers to focus on sourcing starches from natural, non-GMO sources. For instance, a study by the Food and Beverage Industry Association found that 75% of consumers prefer food products made with natural ingredients. This inclination towards natural components has prompted many food producers to reformulate their products, emphasizing clean label starches that align with consumer expectations.
Growth of Plant-Based Products:
The rise of plant-based diets is significantly influencing the clean label starch market. With more consumers adopting vegetarian and vegan lifestyles, there is a growing demand for plant-derived food ingredients, including starches. For instance, according to a report from the Plant Based Foods Association, sales of plant-based foods increased by 27% over the past year, reaching $7 billion in sales. This trend not only boosts the demand for clean label starches derived from plants but also encourages innovation in product development to cater to this expanding market segment.
Focus on Functional Properties:
Another current trend is the emphasis on the functional properties of clean label starches. Manufacturers are increasingly interested in how these starches can enhance food texture, stability, and shelf life without compromising their clean label status. A survey by the Institute of Food Technologists revealed that 68% of food scientists are exploring the use of clean label starches to improve product formulations. This focus on functionality encourages the development of versatile starches that can serve multiple roles in food applications, thereby driving market growth.
Digital Transparency and Consumer Engagement:
Digital transparency is becoming an essential aspect of the clean label starch market, as consumers demand more information about the products they consume. Companies are increasingly utilizing digital platforms to provide detailed information about ingredient sourcing, processing methods, and nutritional benefits. A report by the Grocery Manufacturers Association found that 63% of consumers actively seek this information online before making purchasing decisions. This trend towards digital transparency not only enhances consumer trust but also encourages brands to adopt clean label starches that can be effectively communicated through their marketing channels.
Market Challenges Analysis:
High Production Costs:
The Clean Label Starch Market faces a significant restraint in the form of elevated production costs. Clean label starches require natural and minimally processed ingredients, often sourced sustainably, which can be substantially more expensive than conventional alternatives. This cost disparity increases the price of clean label products, potentially limiting their adoption, particularly in price-sensitive markets. Balancing consumer demand for clean label options with their willingness to pay premium prices presents a considerable challenge for manufacturers, potentially slowing market growth.
Regulatory Compliance Complexity:
A fragmented regulatory landscape adds further challenges to the Clean Label Starch Market. Different regions uphold varying definitions and standards for “clean label” products, often resulting in complex and region-specific compliance requirements. For instance, the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) have different guidelines regarding ingredient transparency and processing limitations. This lack of standardization creates obstacles for companies attempting to establish uniform clean label products across multiple regions, increasing compliance costs and limiting international expansion.
Limited Functional Properties:
Compared to conventional modified starches, clean label starches may offer limited functional properties, such as reduced stability and thickening abilities. This poses a challenge for manufacturers aiming to replicate the performance of traditional starches without compromising product quality. As a result, clean label starches may not fully meet the technical requirements for various food applications, restricting their usage in certain processed food categories. Overcoming these technical limitations remains crucial for broader market adoption and innovation in clean label starch formulations.
Market Segmentation Analysis:
By Type
The market is segmented into categories such as corn, potato, tapioca, and wheat starch. Corn starch holds a significant share due to its wide availability and cost-effectiveness, particularly in North America. Meanwhile, tapioca starch is increasingly popular in regions focused on gluten-free and allergen-free products, making it a preferred choice for health-conscious consumers.
By Technology
Clean label starch production utilizes various processing technologies, including physical modifications, enzymatic processing, and fermentation. Physical modifications dominate due to their minimal chemical involvement, aligning with consumer preferences for naturally processed ingredients. Enzymatic processing also gains traction, particularly in premium products, as it provides cleaner labelling while enhancing the functional properties of starch, appealing to both manufacturers and consumers aiming for higher product transparency.
By End User
The end-user segment primarily includes food and beverage, pharmaceutical, and personal care industries. The food and beverage sector, encompassing bakery, confectionery, dairy, and processed foods, holds the largest market share as clean label starch meets consumer demand for natural and minimally processed ingredients. The pharmaceutical and personal care industries are also notable adopters, as clean label starch serves as a binder and stabilizer in tablets and personal care products, aligning with the growing consumer preference for clean label and sustainable products across multiple sectors.
Segmentations:
By Source- Wheat
- Corn
- Potato
- Tapioca
- Rice & Pea
- Food Industry
-
-
- Bakery & Confectionery
- Dairy & Desserts
- Soups, Sauces & Dressings
- Savory Snacks
- Others
-
- Animal Feed Industry
- Pharmaceutical Industry
- Others
By Regions
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds a prominent share in the clean label starch market, driven by strong consumer demand for transparency in food ingredients and a well-established food processing industry. With the U.S. as a major contributor, the region commands approximately 30% of the global market share. Regulatory standards from the U.S. Food and Drug Administration (FDA) support clean label trends by encouraging ingredient transparency, which has led many manufacturers to prioritize clean label alternatives. Additionally, the growing awareness of health and wellness among consumers and the demand for minimally processed, non-GMO ingredients are expected to sustain North America’s market position.
Europe
Europe follows closely with around 25% of the global market share, influenced by stringent regulations from the European Food Safety Authority (EFSA) and high consumer awareness regarding clean label products. Germany, France, and the United Kingdom are key contributors, with an increasing preference for organic, allergen-free, and gluten-free options. The European market is driven by regulatory pressure to reduce artificial additives, which has encouraged food manufacturers to adopt clean label starches. This trend is further supported by the region's proactive approach to sustainable and transparent ingredient sourcing, a value highly regarded by European consumers.
Asia-Pacific
Asia-Pacific holds approximately 20% of the global clean label starch market share, exhibiting the highest growth potential among all regions. Rising consumer demand for healthy, natural, and clean label foods, particularly in China, India, Japan, and Australia, is a significant growth driver. The expanding middle-class population, coupled with increasing disposable income, has led to a growing inclination toward premium food products with clean label attributes. Regulatory support for clean label claims is less defined in Asia-Pacific compared to North America and Europe, yet consumer preference for transparency and natural ingredients is rapidly influencing local brands and multinationals to offer clean label options.
Latin America
Latin America holds a smaller share, accounting for approximately 15% of the global market. However, the region's market is growing steadily as consumers become more health-conscious and aware of clean label options. Brazil, Argentina, and Mexico are key markets where clean label starch adoption is rising, particularly in the food and beverage sector. Limited regional production capacity and higher import dependence are challenges that influence market growth, but the demand for natural and non-GMO products is creating growth opportunities.
Middle East & Africa
The Middle East & Africa currently represents the smallest share of the clean label starch market, approximately 10%. Consumer awareness about clean label products is gradually increasing, especially in urban areas, but regulatory frameworks supporting clean label claims remain limited. Despite these challenges, an emerging trend of health-conscious consumers in regions like South Africa and the UAE points toward gradual market growth as consumer preferences shift toward natural and minimally processed ingredients.
Key Player Analysis:
- Cargill, Incorporated
- Ingredion Incorporated
- Tate & Lyle PLC
- Archer Daniels Midland Company
- Roquette Frères S.A.
- BENEO GmbH
- MGP Ingredients, Inc.
- AGRANA Beteiligungs-AG
- Avebe U.A.
- KMC Kartoffelmelcentralen A.M.B.A
Competitive Analysis:
The Clean Label Starch Market is highly competitive, with major players focusing on product innovation, expansion, and strategic partnerships to strengthen their market positions. Companies like Cargill, Ingredion, and Tate & Lyle are investing in research and development to enhance the functional properties of clean label starches, aligning with the rising consumer demand for minimally processed, transparent ingredients. Global players such as Archer Daniels Midland and Roquette Frères are also expanding their production capacities and exploring sustainable sourcing to meet regional regulatory standards and consumer expectations. Smaller players, including BENEO and Avebe, are leveraging their specialized expertise in non-GMO and gluten-free starches to differentiate themselves in the market. Strategic acquisitions and joint ventures are common as companies seek to broaden their portfolios and geographic reach, fostering an increasingly competitive landscape where innovation and sustainability are pivotal to gaining a competitive edge.
Recent Developments:
- In April 2022, Ingredion launched two functional native rice starches designed to improve color and flavor release, catering to the growing demand for clean label ingredients.
- In 2023, Cargill expanded its portfolio by introducing a new line of clean label starches derived from non-GMO corn, aiming to meet the increasing consumer preference for transparent and natural food ingredients.
- In 2024, Tate & Lyle announced the opening of a new production facility dedicated to clean label starches, enhancing their capacity to supply high-quality, clean label solutions to food manufacturers globally.
- In 2022, Roquette invested in research and development to create a new range of pea-based clean label starches, addressing the rising demand for plant-based and allergen-free ingredients in the market.
Market Concentration & Characteristics:
The Clean Label Starch Market is moderately concentrated, with a few major players holding significant market share alongside several regional and niche companies. Industry leaders such as Cargill, Ingredion, and Tate & Lyle dominate the market through extensive product portfolios, strong distribution networks, and consistent investment in innovation. This market exhibits characteristics of high product differentiation, with companies focusing on various starch sources-such as corn, potato, and tapioca-and specialized processing technologies to cater to diverse applications across food, pharmaceutical, and personal care sectors. The emphasis on sustainable sourcing and transparent labelling aligns with evolving consumer expectations, positioning clean label starches as premium alternatives to traditional modified starches. Overall, market competition is driven by the need for continuous innovation, adherence to regulatory standards, and responsiveness to regional consumer preferences, making adaptability and R&D investment crucial for maintaining market positioning.
Report Coverage:
The research report offers an in-depth analysis based on Source, Application, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for clean label starches is expected to rise as consumers increasingly prioritize transparency and natural ingredients in food products.
- Innovations in processing technologies are anticipated to improve the functionality and performance of clean label starches, broadening their application across diverse industries.
- Regulatory pressure to reduce artificial additives in food products will likely drive further adoption of clean label starches, especially in regions with stringent food safety standards.
- Plant-based and allergen-free starch options, such as pea and tapioca starches, are forecasted to gain traction to meet the needs of health-conscious and allergen-sensitive consumers.
- Companies are likely to expand their portfolios with region-specific clean label starch variants to cater to local tastes and regulatory requirements.
- Growing interest in gluten-free and non-GMO ingredients is expected to bolster demand for alternative starch sources within the clean label segment.
- Strategic partnerships and acquisitions are anticipated to increase as companies seek to enhance their geographic presence and production capabilities.
- Sustainability will remain a key focus, with companies investing in eco-friendly sourcing and production processes to appeal to environmentally conscious consumers.
- Rising demand from the personal care and pharmaceutical sectors is expected as these industries adopt clean label starches as binders and stabilizers.
- Enhanced R&D investment will likely drive advancements in clean label starch formulations, helping companies meet diverse industry requirements and strengthen competitive positioning.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Clean Label Starch Market?
What factors are driving the growth of the Clean Label Starch Market?
What are some challenges faced by the Clean Label Starch Market?
Who are the major players in the Clean Label Starch Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Clean Label Starch Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Clean Label Starch Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,710 million → 2032: USD 2,604.47 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Clean Label Starch Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Clean Label Starch Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Clean Label Starch Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Clean Label Starch Market Drivers
- 3.3 Clean Label Starch Market Restraints & Challenges
- 3.4 Clean Label Starch Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Clean Label Starch Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Clean Label Starch Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Clean Label Starch category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Clean Label Starch Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Clean Label Starch Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Clean Label Starch. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Clean Label Starch Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Clean Label Starch Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Clean Label Starch Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Clean Label Starch (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Clean Label Starch
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Clean Label Starch Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Clean Label Starch Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Clean Label Starch Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Clean Label Starch Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Clean Label Starch Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Clean Label Starch Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Clean Label Starch Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Clean Label Starch Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
