
Market Overview
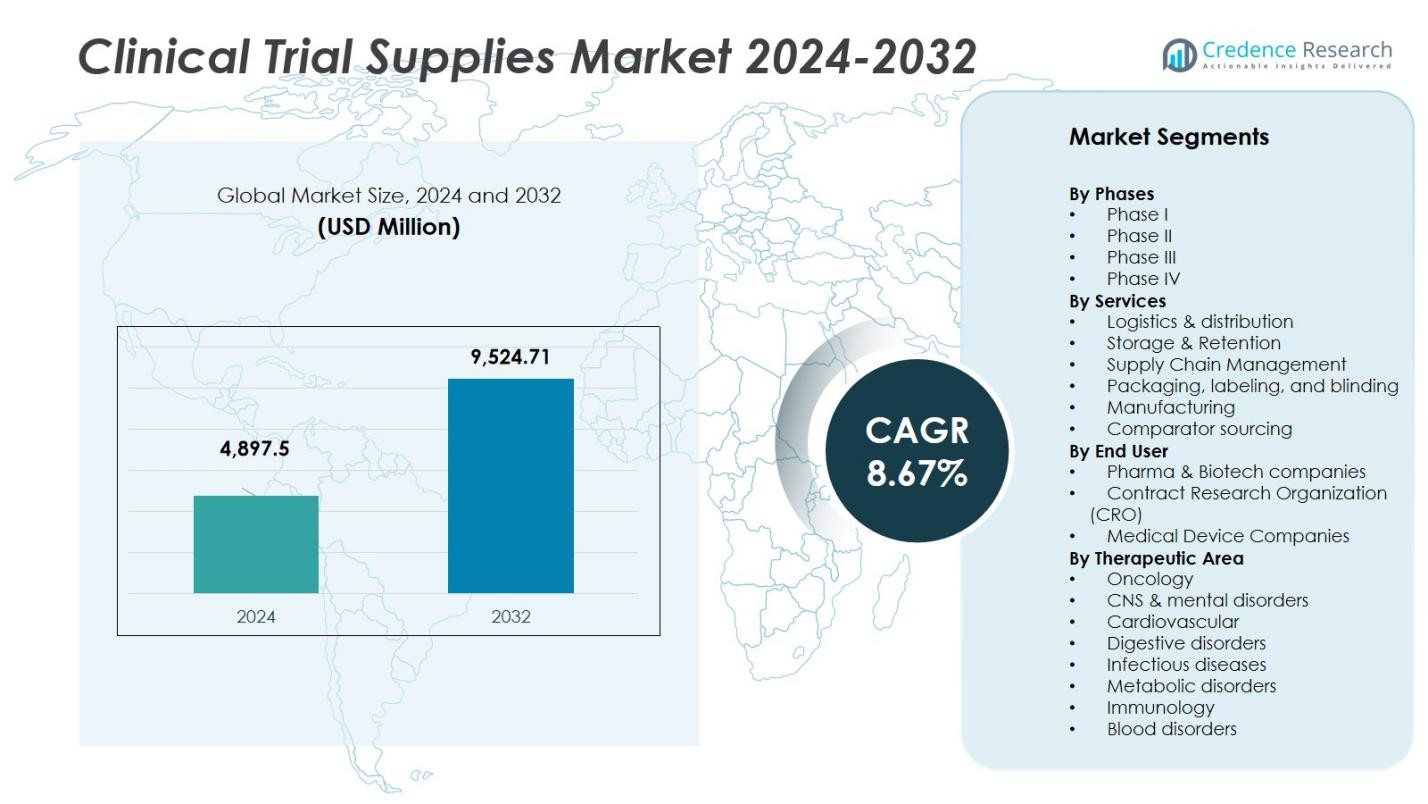
The Clinical Trial Supplies Market size was valued at USD 4,897.5 million in 2024 and is anticipated to reach USD 9,524.71 million by 2032, at a CAGR of 8.67% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Clinical Trial Supplies Market Size 2024 | USD 4,897.5 Million |
| Clinical Trial Supplies Market, CAGR | 8.67% |
| Clinical Trial Supplies Market Size 2032 | USD 9,524.71 Million |
The Clinical Trial Supplies Market includes key players such as Thermo Fisher Scientific, Inc., Catalent Pharma Solutions, Almac Group Ltd., PAREXEL International Corporation and Movianto GmbH, each driving service innovation and geographic expansion. The market is strong in North America, with a market share of about 55 % in 2024, reflecting the region’s advanced logistics and major trial activity. Europe holds approximately 25 % of global share, benefiting from robust pharmaceutical clusters and cross‑border trial structures. Asia‑Pacific captures around 15 % of the market, with rapid growth supported by cost‑efficient sites and expanding trial infrastructure. These regional distributions shape how the leading companies allocate resources and plan expansions.
Market Insights
- The Clinical Trial Supplies Market was valued at USD 4,897.5 million in 2024 and is projected to reach USD 9,524.71 million by 2032, growing at a CAGR of 8.67 %.
- Phase III holds the largest segment share at around 45 %, reflecting high demand for large‑scale efficacy trials.
- The logistics & distribution service segment leads with roughly 35 % share, driven by the complexity of global drug shipments and temperature‑sensitive therapies.
- North America dominates regional share at about 55 %, followed by Europe at ~25 % and Asia‑Pacific at ~15 %, with emerging regions making up the remainder.
- The market faces restraints from stringent regulatory requirements across multiple countries and supply chain disruptions that delay trial material delivery and increase costs.
Market Segmentation Analysis:
By Phases:
In the Clinical Trial Supplies Market, Phase III holds the largest market share, accounting for approximately 45% of the total market. This phase involves large-scale clinical trials aimed at assessing the efficacy and safety of new treatments. The dominance of Phase III is driven by the growing demand for advanced therapeutics and the need for extensive data before regulatory approval. Additionally, increasing investments in research and development by pharmaceutical companies contribute significantly to the growth of this segment, driving market expansion during this critical stage of clinical trials.
- For instance, Pfizer’s Phase III CREST trial demonstrated that their investigational drug sasanlimab combined with BCG significantly improved event-free survival in patients with high-risk non-muscle invasive bladder cancer, highlighting the impact of extensive data generation in this phase.
By Services:
The logistics & distribution segment leads the Clinical Trial Supplies Market, capturing around 35% of the total market share. This service is crucial for ensuring the timely and efficient delivery of clinical trial supplies to global sites. The growing trend of multi-site international clinical trials and the increasing complexity of trial logistics, including temperature-sensitive drugs, are key drivers for this segment's growth. Logistics companies are increasingly leveraging technology and supply chain management platforms to optimize operations, further contributing to the expansion of the logistics & distribution segment.
- For instance, Parexel expanded its clinical trial supplies and logistics depot in Suzhou, China, to enhance local distribution capabilities for complex global trials.
By End User:
Pharma & Biotech companies dominate the Clinical Trial Supplies Market, with a market share of approximately 60%. This segment is primarily driven by the rising number of drug development pipelines and the ongoing research into biologics and novel therapeutics. Pharmaceutical and biotech firms are increasing their focus on expanding their portfolios through clinical trials, which fuels the demand for clinical trial supplies. As a result, this end-user segment is expected to continue driving the market's growth, with significant investments in R&D and clinical trials in both developed and emerging markets.
Key Growth Drivers
Increasing Demand for Biologics
The growing demand for biologics is a significant driver for the Clinical Trial Supplies Market. As the biopharmaceutical sector expands, especially with the rise of monoclonal antibodies and gene therapies, there is an increasing need for clinical trial supplies tailored to biologic drugs. These treatments often require specialized packaging, storage, and distribution services due to their temperature sensitivity and complex manufacturing processes. The surge in biologic drug development is expected to continue fueling market growth as more companies invest in the development of innovative therapies.
- For instance, Thermo Fisher Scientific has developed advanced packaging solutions tailored for biologic drugs that maintain required storage conditions and ensure compliance with regulatory standards.
Rising Number of Clinical Trials Globally
The number of clinical trials conducted worldwide has been rising steadily, which is directly boosting the demand for clinical trial supplies. As more new drug candidates enter the clinical development pipeline, pharmaceutical companies, CROs, and research institutions are conducting a higher volume of trials across various phases. With a growing focus on personalized medicine and the expansion of trials into emerging markets, the demand for reliable, efficient clinical trial supply chain solutions is poised for continued growth, thereby driving the overall market expansion.
- For instance, ClinicalTrials.gov reports over 556,000 registered studies worldwide as of October 2025, with more than 313,000 conducted outside the U.S., highlighting the global expansion of trials.
Advancements in Supply Chain Technology
Advancements in supply chain management and logistics technologies are enhancing the efficiency and reliability of clinical trial supplies. Innovations such as temperature-controlled shipping, real-time tracking systems, and automated inventory management are improving the delivery of clinical trial materials. These technological advancements help reduce delays and enhance the accuracy of supply chains, ensuring that materials are delivered on time and under optimal conditions. As the industry becomes more globalized and trials become more complex, these technological improvements are key to supporting the market's expansion.
Key Trends & Opportunities
Growth of Personalized Medicine
Personalized medicine is emerging as a key trend in the Clinical Trial Supplies Market, offering significant opportunities for growth. As treatments become more individualized, clinical trials are increasingly focusing on targeted therapies based on genetic, molecular, and environmental factors. This trend is creating demand for highly specialized trial supplies, including those for precision drugs and diagnostics. Personalized medicine’s expansion is expected to open new avenues for market players to provide tailored solutions, ranging from advanced packaging to temperature-sensitive logistics and tracking, aligning with the trend toward more patient-specific treatments.
- For instance, Illumina Inc., a key player in genomic sequencing technologies, has been instrumental in advancing personalized medicine by enabling more cost-efficient genetic profiling critical for targeted therapy trials.
Expansion in Emerging Markets
Emerging markets are presenting a growing opportunity for the Clinical Trial Supplies Market. As pharmaceutical and biotech companies increasingly expand their clinical trials into regions like Asia-Pacific, Latin America, and the Middle East, there is a rising need for supply chain solutions that cater to diverse regulatory requirements and logistical challenges. The ongoing shift toward global trials in these regions, coupled with economic growth and improvements in healthcare infrastructure, is driving demand for clinical trial supplies. Companies focusing on these regions can tap into an expanding market as clinical research becomes more geographically diverse.
- For instance, PAREXEL International expanded its depot in Santiago, Chile, to enhance supply chain management for trials in Latin America, exemplifying focused investments to support emerging markets.
Key Challenges
Regulatory Complexity
One of the key challenges facing the Clinical Trial Supplies Market is navigating the complex and varied regulatory environments across different countries. Different regions have specific regulations regarding the storage, transportation, and handling of clinical trial materials. Compliance with these regulations can be costly and time-consuming for companies operating globally. The need to adhere to strict regulatory standards while conducting international trials complicates supply chain management, requiring market players to invest in expertise and infrastructure to ensure compliance across different jurisdictions.
Supply Chain Disruptions
Supply chain disruptions continue to be a major challenge for the Clinical Trial Supplies Market. Factors such as natural disasters, geopolitical instability, and the COVID-19 pandemic have highlighted the vulnerability of global supply chains. These disruptions can lead to delays in the delivery of critical clinical trial materials, affecting trial timelines and patient safety. The increased complexity of clinical trials, with multi-site and international operations, further exacerbates these challenges. Companies must develop more resilient supply chain strategies to mitigate the impact of unforeseen disruptions and ensure continuity in clinical trials.
Regional Analysis
North America
The North America region held a market share of around 55% in 2024 for the clinical trial supplies industry. The dominance reflects a high concentration of clinical trial activity, advanced logistics infrastructure, and strong regulatory frameworks in countries like the US and Canada. Sponsors increasingly run decentralized and globalised studies from this region, driving demand for specialised packaging, temperature‑controlled storage and rapid distribution. Further investment in cold‑chain logistics and digital supply‑chain tracking systems supports this lead, while the large number of contract research organisations (CROs) in the region strengthens the supply service network.
Europe
Europe accounted for approximately 25% of the global clinical trial supplies market in 2024. Robust biotech and pharmaceutical ecosystems in the UK, Germany and France drive this share, supported by favourable regulatory policies and cross‑border clinical trial initiatives. European stakeholders increasingly adopt integrated supply‑chain models and advanced packaging technologies to support specialised biologics trials. Growing partnerships between CROs and local logistics providers enhance readiness across multiple trial phases. However, competition from Asia‑Pacific for cost‑efficient trials and emerging regulatory demands keep European players focused on value‑added services rather than volume alone.
Asia‑Pacific
The Asia‑Pacific region captured roughly 15% of the clinical trial supplies market in 2024, and is forecasted to grow faster than other regions. Major growth drivers include lower per‑patient trial costs, large treatment‑naïve populations, and improving regulatory regimes in countries such as India and China. In addition, global sponsors increasingly establish regional supply hubs and direct‑to‑patient models in Asia‑Pacific to optimise timelines and costs. Investment in cold‑chain infrastructure and digitised trial logistics is gaining momentum. As multinational trials expand in this region, the share of clinical trial supplies procured, packaged and shipped locally is expected to rise significantly.
Latin America, Middle East & Africa (MEA)
The combined Latin America and MEA region represented the remaining 5% of the global clinical trial supplies market in 2024. Growth in these regions is driven by emerging trial sites, regulatory reforms and expanding health‑care infrastructure in countries such as Brazil, Mexico, South Africa and the UAE. Sponsors are tapping into these markets for patient‑diverse and cost‑efficient trial populations. Logistics firms are setting up regional depots and tailored supply services. Despite current small share, the region presents strong future opportunity as infrastructure improves and global trials increasingly target non‑traditional geographies.
Market Segmentations:
By Phases
- Phase I
- Phase II
- Phase III
- Phase IV
By Services
- Logistics & distribution
- Storage & Retention
- Supply Chain Management
- Packaging, labeling, and blinding
- Manufacturing
- Comparator sourcing
By End User
- Pharma & Biotech companies
- Contract Research Organization (CRO)
- Medical Device Companies
By Therapeutic Area
- Oncology
- CNS & mental disorders
- Cardiovascular
- Digestive disorders
- Infectious diseases
- Metabolic disorders
- Immunology
- Blood disorders
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the clinical trial supplies market includes major players such as Thermo Fisher Scientific Inc., Catalent Inc., Almac Group Ltd., PAREXEL International Corporation, and Movianto GmbH. These firms compete primarily through global infrastructure investment, service portfolio expansion, and strategic acquisitions. They aggressively build temperature‑controlled distribution networks, integrated packaging and labeling services, and end‑to‑end supply chain management solutions. The market features moderate concentration: the top five players collectively capture an estimated 40‑50% of industry share. Competitive intensity remains high, driven by expanding biologics trials and global site proliferation, which compel firms to differentiate via specialized services and geographic coverage. Continuous innovation in logistics, tracking technology, and client partnerships remains central to maintaining market leadership.
Key Player Analysis
- Parexel International Corporation
- Thermo Fisher Scientific, Inc.
- Almac Group Ltd.
- UDG Healthcare
- Movianto GmbH
- Patheon, Inc.
- Piramal Pharma Solutions
- Sharp Packaging Services
- Biocair International Ltd.
- Catalent Pharma Solutions
Recent Developments
- In March 2025, DHL Group completed its acquisition of CRYOPDP (Cryoport), a specialist in clinical trial logistics for biopharma and cell & gene therapies. The move strengthens DHL’s presence in temperature‑controlled and specialised courier services for trial materials.
- In September 2025, Catalent, Inc. and Science 37 announced a partnership to enhance the investigational medicinal product (IMP) supply chain and enable at-home trial participation.
- In March 2025, DHL Group acquired CRYOPDP (a subsidiary of Cryoport Inc.), strengthening its specialty logistics services for biologics and clinical trial materials.
- In July 2025, Aptar Pharma acquired the clinical-trial materials manufacturing capabilities of Mod3 Pharma (formerly Enteris Biopharma).
Report Coverage
The research report offers an in-depth analysis based on Phase, Services, Therapeutic Area, End User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand as the number of global clinical trials increases, including trials in Asia‑Pacific and emerging regions.
- Demand will grow for specialized supplies supporting biologics, gene therapies, and cell‑based treatments, driving complexity in packaging and logistics.
- Direct‑to‑patient (DTP) and decentralized trial models will become more common, boosting demand for flexible supply chain solutions.
- Real‑time tracking, blockchain, and digital monitoring technologies will be further adopted to enhance supply chain visibility and control.
- Cold‑chain and temperature‑controlled logistics capacity will need expansion due to biologics and complex therapies requiring tight thermal management.
- Emerging markets will gain a larger share as clinical research shifts to cost‑efficient geographies with growing healthcare infrastructure.
- Strategic alliances and mergers among supply‑chain service providers, CROs, and pharma firms will increase to build end‑to‑end capabilities.
- Regulatory harmonisation and streamlined approval pathways will support faster trial set‑up and supply deployment.
- Environmental and sustainability pressures will lead firms to adopt greener logistics, packaging materials, and supply‑chain models.
- Resilience planning will become critical as supply chains face disruptions from pandemics, geopolitics, and global logistics constraints.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Demand for Biologics
The rise of biologics, including monoclonal antibodies and gene therapies, requires specialized clinical trial supplies such as temperature-controlled packaging and distribution. This complexity drives demand for advanced logistics and supply chain solutions tailored to biologic drugs.
Rising Number of Global Clinical Trials
The steady increase in the number of clinical trials worldwide, especially in emerging markets, is boosting the need for reliable and efficient clinical trial supply chains. Expansion into new geographies and the proliferation of multi-site studies further fuel market growth.
Advancements in Supply Chain Technology
Innovations such as real-time tracking, temperature-controlled shipping, and automated inventory management are improving the efficiency and reliability of clinical trial supply delivery. These technologies help reduce delays and ensure compliance with regulatory standards.
Growth of Personalized Medicine
The shift toward personalized and precision medicine is increasing the need for highly specialized clinical trial supplies, including custom packaging and logistics for targeted therapies. This trend is opening new opportunities for market players to provide tailored solutions.
Expansion in Emerging Markets
Pharmaceutical and biotech companies are increasingly conducting trials in Asia-Pacific, Latin America, and the Middle East, driving demand for supply chain solutions that address diverse regulatory and logistical challenges. Investments in local infrastructure and regional depots are supporting this growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Clinical Trial Supplies Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Clinical Trial Supplies Market projected to grow between 2025 and 2032?
Which Clinical Trial Supplies Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Clinical Trial Supplies Market?
Who are the leading companies in the Clinical Trial Supplies Market?
Which region commanded the largest share of the Clinical Trial Supplies Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Phase
- 1.2.1 Phase I
- 1.2.2 Phase II
- 1.2.3 Phase III
- 1.2.4 Phase IV
- 1.3 By Service
- 1.3.1 Logistics & distribution
- 1.3.2 Storage & Retention
- 1.3.3 Supply Chain Management
- 1.3.4 Packaging, labeling, and blinding
- 1.3.5 Manufacturing
- 1.3.6 Comparator sourcing
- 1.4 By End User
- 1.4.1 Pharma & Biotech companies
- 1.4.2 Contract Research Organization (CRO)
- 1.4.3 Medical Device Companies
- 1.5 By Therapeutic Area
- 1.5.1 Oncology
- 1.5.2 CNS & mental disorders
- 1.5.3 Cardiovascular
- 1.5.4 Digestive disorders
- 1.5.5 Infectious diseases
- 1.5.6 Metabolic disorders
- 1.5.7 Immunology
- 1.5.8 Blood disorders
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 4,897.5 million → 2032: USD 9,524.71 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Clinical Trial Supplies Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Clinical Trial Supplies Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Clinical Trial Supplies Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Clinical Trial Supplies Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Clinical Trial Supplies Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Clinical Trial Supplies Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Clinical Trial Supplies Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Clinical Trial Supplies Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 4,897.5 million → 2032: USD 9,524.71 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Clinical Trial Supplies Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Phase - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Phase I
- 12.3.7.2 Phase II
- 12.3.7.3 Phase III
- 12.3.7.4 Phase IV
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Service - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Logistics & distribution
- 12.4.7.2 Storage & Retention
- 12.4.7.3 Supply Chain Management
- 12.4.7.4 Packaging, labeling, and blinding
- 12.4.7.5 Manufacturing
- 12.4.7.6 Comparator sourcing
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End User - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Pharma & Biotech companies
- 12.5.7.2 Contract Research Organization (CRO)
- 12.5.7.3 Medical Device Companies
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Therapeutic Area - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Oncology
- 12.6.7.2 CNS & mental disorders
- 12.6.7.3 Cardiovascular
- 12.6.7.4 Digestive disorders
- 12.6.7.5 Infectious diseases
- 12.6.7.6 Metabolic disorders
- 12.6.7.7 Immunology
- 12.6.7.8 Blood disorders
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Clinical Trial Supplies End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Clinical Trial Supplies Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Clinical Trial Supplies Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Clinical Trial Supplies Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Thermo Fisher Scientific, Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Catalent Pharma Solutions
- 18.4 Almac Group Ltd.
- 18.5 PAREXEL International Corporation
- 18.6 Movianto GmbH
- 18.7 UDG Healthcare
- 18.8 Patheon, Inc.
- 18.9 Piramal Pharma Solutions
- 18.10 Sharp Packaging Services
- 18.11 Biocair International Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

